Wednesday, October 23, 2019

If you want to boost the economy, big infrastructure projects won't cut it: new Treasury boss

Treasury secretary Steven Kennedy – in the job for for just weeks after moving across from the department of infrastructure last month – has dismissed talk of spending big on infrastructure in order to escape an economic downturn.

Such calls “sound straightforward, but in practice are difficult to achieve”, he told a Senate hearing on Wednesday.

The timing requirements of fiscal stimulus are hard to give effect to while ensuring large projects are well planned and executed, and cost and capacity pressures are managed. There are some opportunities though, usually related to smaller projects and maintenance expenditure. The Commonwealth and state Governments are currently actively exploring these opportunities.

More broadly he made it plain that it was the role of the Reserve Bank rather than the Treasury to provide economic stimulus.

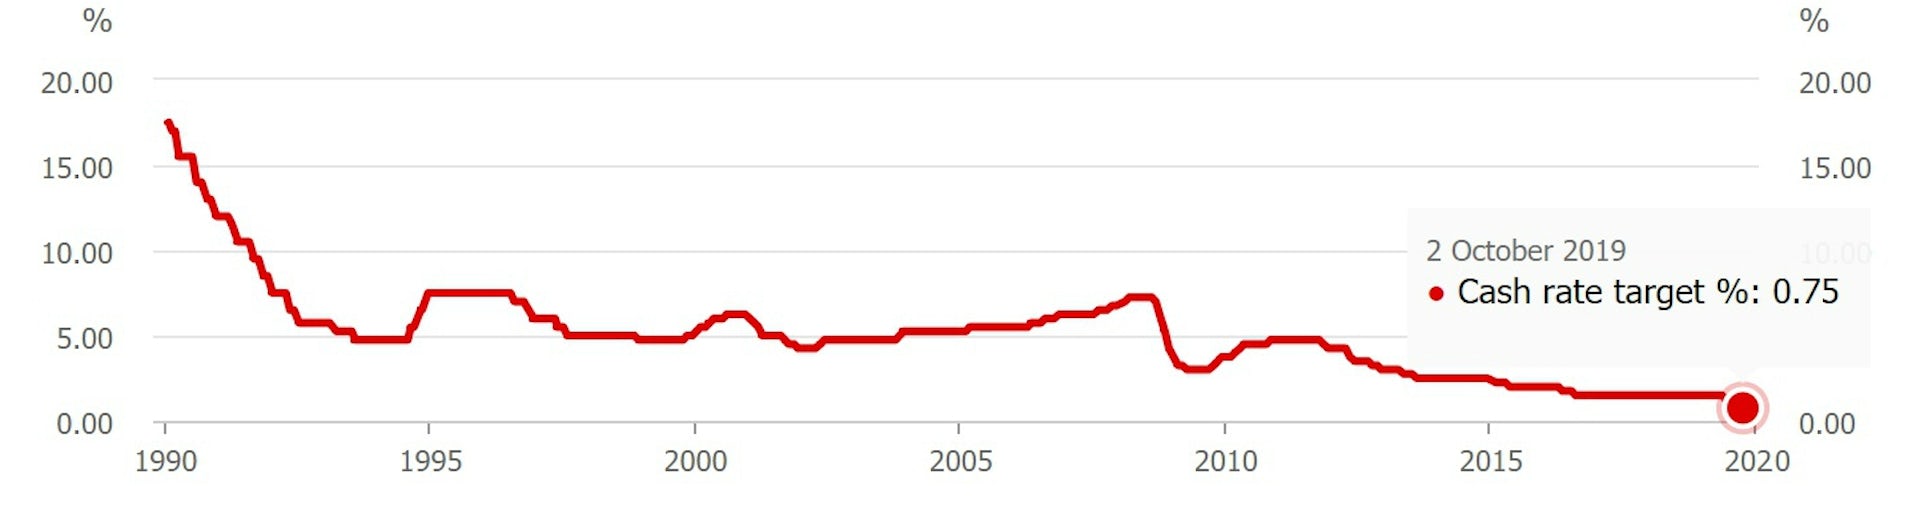
The bank has already cut its cash rate to a record low of 0.75% and has indicated it is prepared to consider unconventional monetary policy measures that would have the effect of cutting a wider range of rates.


Read more: 0.75% is a record low, but don't think for a second the Reserve Bank has finished cutting the cash rate


However, bank Governor Philip Lowe said last week such tools would be most effective “when used together with a broader set of policies”, including government spending and tax policies.

Without crisis, no need to spend more
Kennedy rejected the idea of extra spending except in an emergency, saying Treasury could best serve Australia’s interests by a “stable and predictable” policy framework that kept the budget near balance over time.

There would be times when a downturn cut revenue and increased spending on support payments, pushing the budget into deficit, but beyond allowing those so-called automatic stabilisers to operate there wasn’t normally a case for doing more.

The exceptions were “periods of crisis”.

“It is important to consider separately broader policy objectives and temporary responses to crisis,” Kennedy said.

“The circumstances or crisis that would warrant temporary fiscal responses are uncommon.”

Although Australia’s economy is not in crisis, Brexit, the US-China trade war and turmoil in Hong Kong have slowed economic and trade growth worldwide, as businesses opt to stay on the sidelines.

No crisis, but weak growth worldwide

In Australia, economic growth had been unusually weak, weighed down by weak household spending which was itself the result of weak income growth, weak house prices, weak housing investment, and weaker than expected non-mining investment.

Mining investment was down sharply, as was to be expected after the completion of several large liquefied natural gas projects.

Given low interest rates, it was “somewhat of a puzzle” that business investment was not growing faster. Partly that might be because the “hurdle rates” businesses use to assess projects have not been adjusted down as they should have been. Partly it might be because of uncertainties surrounding the global economy and technological change.

Structural factors may also be at play — it is not clear what business investment looks like in a world where more than two thirds of our economy is now services based.

The budget tax cuts that flowed into returns from July have not yet led to a “particularly large improvement” in household spending.

Wages, investment “somewhat of a puzzle”

“We will continue to assess the data on consumption as it becomes available, but it is worth noting that even if households initially use the tax cuts to pay down debt faster, this will still bring forward the point at which households could increase their spending,” Dr Kennedy said.

It is possible that spending might have been even weaker without the tax cuts.

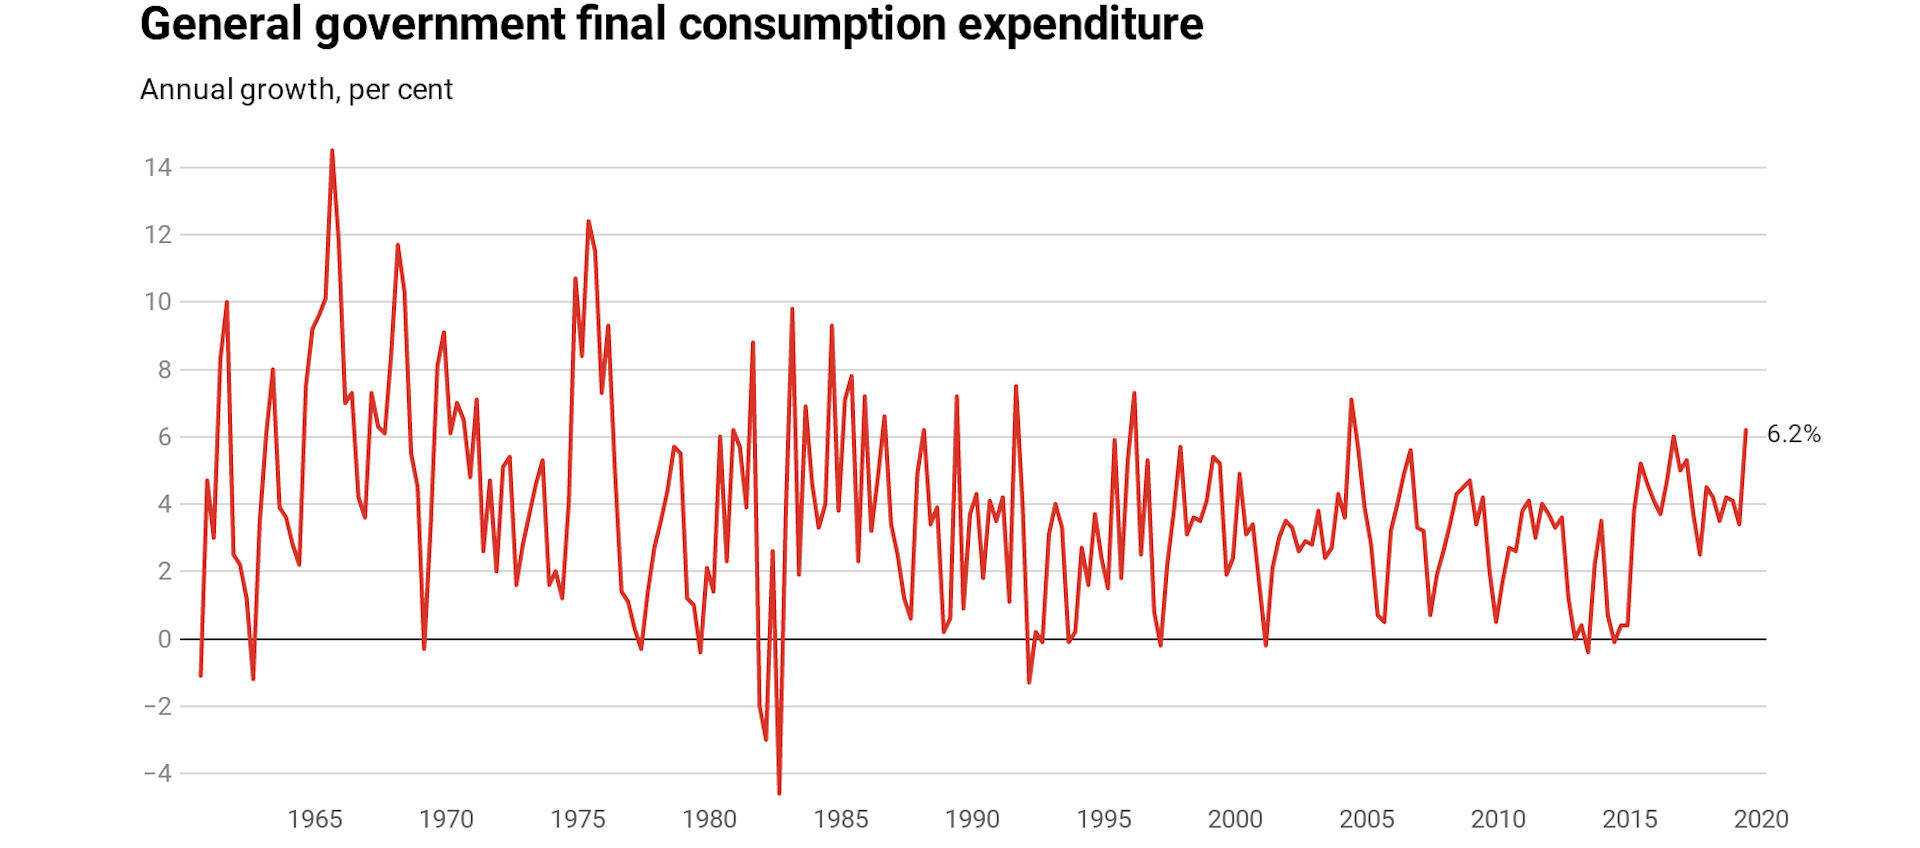
Holding back the economy during the year to June has been drought and dry weather which knocked 0.2 percentage points of the economic growth. Holding it up has been larger than normal growth in government spending that contributed 0.2 percentage points more to economic growth than was normal.


Read more: Why we've the weakest economy since the global financial crisis, with few clear ways out


No one had been able come up with a complete explanation for Australia’s unexpectedly low rate of wage growth. One explanation might be that even though the unemployment rate of 5.2% was unusually low, increases in employment were drawing in older workers and women rather than pushing up wages.

Ultimately what was needed to sustain higher wage growth was productivity growth, and that would be difficult to achieve while business investment was weak. The Productivity Commission had come up with a set of recommendations state and federal ministers were working their way through.

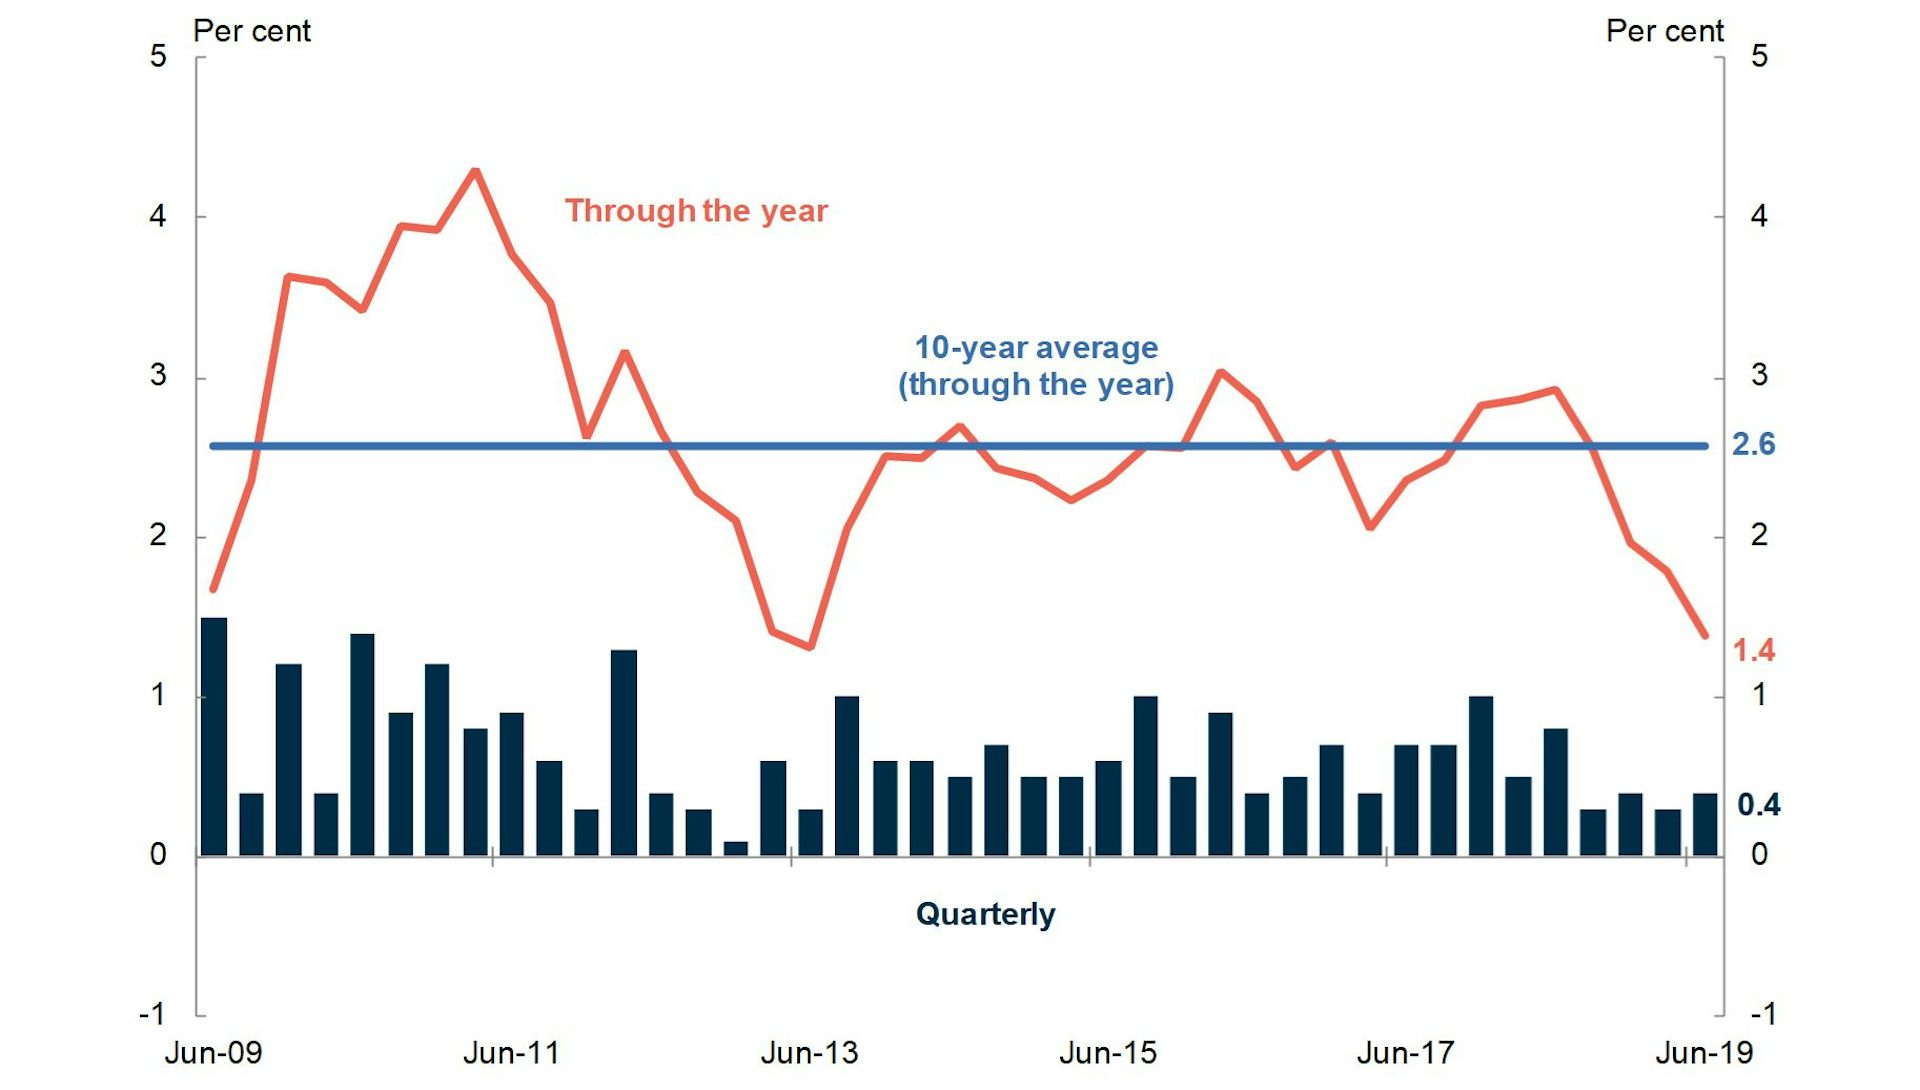
Although economic growth has been very low - just 1.4% in the year to June – it grew more strongly in the last half of that year than the first. It might be “strengthening from here”.The Conversation


Peter Martin, Visiting Fellow, Crawford School of Public Policy, Australian National University

This article is republished from The Conversation under a Creative Commons license. Read the original article.

Read more >>

Tuesday, October 01, 2019

0.75% is a record low, but don't think for a second the Reserve Bank has finished cutting the cash rate

Anyone who thought that with the Reserve Bank’s cash rate now close to zero, its run of interest rate cuts was over, needs only to read the last sentence of Governor Philip Lowe’s announcement after Tuesday’s cut:

The Board will continue to monitor developments, including in the labour market, and is prepared to ease monetary policy further if needed to support sustainable growth in the economy, full employment and the achievement of the inflation target over time.

For the longest time, the run of cuts was over.

Lowe’s immediate predecessor, Glenn Stevens, cut the cash rate to a record low of 1.5% in August 2016 as something of a “parting gift”, allowing Lowe to take over and keep it steady, unchanged for a record 34 months.

For most of those three years he made it clear the rate was unlikely to fall further. Six times he said the next move in rates was likely to be up, “rather than down”, pointing to rate increases overseas and progress on jobs and returning Australia’s unusually low inflation rate to his target band.

By February this year he was backtracking. Although it wasn’t apparent in the published figures, the unemployment rate was about to begin climbing. Wage growth had been far weaker than forecast, inflation showed no sign of returning to the centre of his target band, and forecasts for global growth were falling.


Reserve Bank cash rate


More importantly, consumer spending, which accounts for six in every ten dollars spent in Australia, was extraordinarily weak, growing at less than half the usual rate, as households “responded to this extended period of weaker income growth by progressively downgrading their spending plans”.

The probabilities of next move being up and down had become “more evenly balanced”.


Read more: RBA update: Governor Lowe points to even lower rates


Two weeks after the May election he cut the cash rate, then cut it again, taking it to a new record low of 1%, anticipated by only two of the 19 economists surveyed by The Conversation just six months earlier.

The extra cut announced on Tuesday is because the last two didn’t do enough.

House prices have begun to move up (as would be expected with lower rates) but borrowing is growing only slowly, and home building is weak. The Australian dollar is low (in part because of the lower rates), which should help make Australian businesses competitive, but they are not keen to borrow.

Since the last Reserve Bank board meeting we have learned that economic growth is shockingly low, just 1.4% over the past year, the weakest since the global financial crisis. Household spending is barely keeping pace with population growth.

Lowe would like to believe the economy has reached “a gentle turning point”. He told a community dinner in Melbourne on Tuesday night the board thinks it might have.

There are a number of factors that are supporting this outlook. These include the low level of interest rates, the recent tax cuts, ongoing spending on infrastructure, signs of stabilisation in some established housing markets, and a brighter outlook for the resources sector.

But they will need help. The bank believes the economy is capable of producing an unemployment rate of 4.5%. Instead it has been climbing, to 5.3%.

How the cuts will help

The cash rate is determined by the rate the Reserve Bank pays banks who deposit with it overnight. It drives almost every other rate, including the rates banks pay retail depositors, which help determine their cost of lending.

They don’t have to cut their mortgage and business rates in line with cuts in the Reserve Bank cash rate, but they usually do.

The big banks played a game of chicken yesterday, each waiting for the other to move. The Commonwealth Bank moved first, offering just 0.13 of the 0.25 points, followed by the National Australia Bank, which offered 0.15 points.

The real action is in the discounted rates that target borrowers for whom they matter. Before Tuesday they averaged 3.46%. Some were much lower. HSBC Australia wanted just 3.17%. If it passes on Tuesday’s cut in full it will charge only 2.92%, offering the first Australian mortgage rate in history beginning with the number “2”.

There’s every reason to believe the cuts will help. Even if Australians don’t borrow more to buy houses, they will be able to use the historically cheap credit embodied in their house loans to buy other things, such as solar panels whose payoff period will have shortened dramatically.

Since June many mortgage-holders will have saved A$150 on monthly payments.

Sure, confidence and decent wage growth would help, but given how indebted many Australians are, low mortgage rates will do quite a bit on their own.

Why they’ll continue

Governor Lowe made it clear on Tuesday that they will have to stay low for “an extended period”. A signed agreement with the treasurer requires him to keep them low until unemployment falls and inflation and economic growth return to return to normal levels.

He would like the government to help by boosting spending. He often mentions spending on infrastructure. But his employment contract requires him to use the cards he has been dealt. If the economy is weak, he is required to boost it using the instruments he has.


Read more: Below zero is ‘reverse’. How the Reserve Bank would make quantitative easing work


That’s why he says he is prepared “to ease monetary policy further”.

If needed, he’ll do it as soon as next month, cutting the cash rate to 0.5%. If more is needed beyond that, he will get ready to use so-called unconventional measures of the kind being used overseas, buying government and corporate bonds in order to force even more money into Australian’s hands.

There’s no reason to believe that the tools he has won’t work, and every reason to believe he’ll keep using them.The Conversation


Peter Martin, Visiting Fellow, Crawford School of Public Policy, Australian National University

This article is republished from The Conversation under a Creative Commons license. Read the original article.
Read more >>

Monday, September 30, 2019

5 questions about superannuation the government's new inquiry will need to ask

The government’s new retirement incomes review will need to work quickly.

On Friday Treasurer Josh Frydenberg said he expected a final report by June, just seven months after the issues paper he wants it to deliver by November.

The deadline is tight for a reason. In recommending the inquiry in its report on the (in)effeciency of Australia’s superannuation system this year, the Productivity Commission said it should be completed “in advance of any increase in the superannuation guarantee rate”.

In other words, in advance of the next leglislated increase in compulsory superannuation contributions, which is on July 1, 2021.


Read more: Government retirement incomes inquiry puts superannuation in the frame


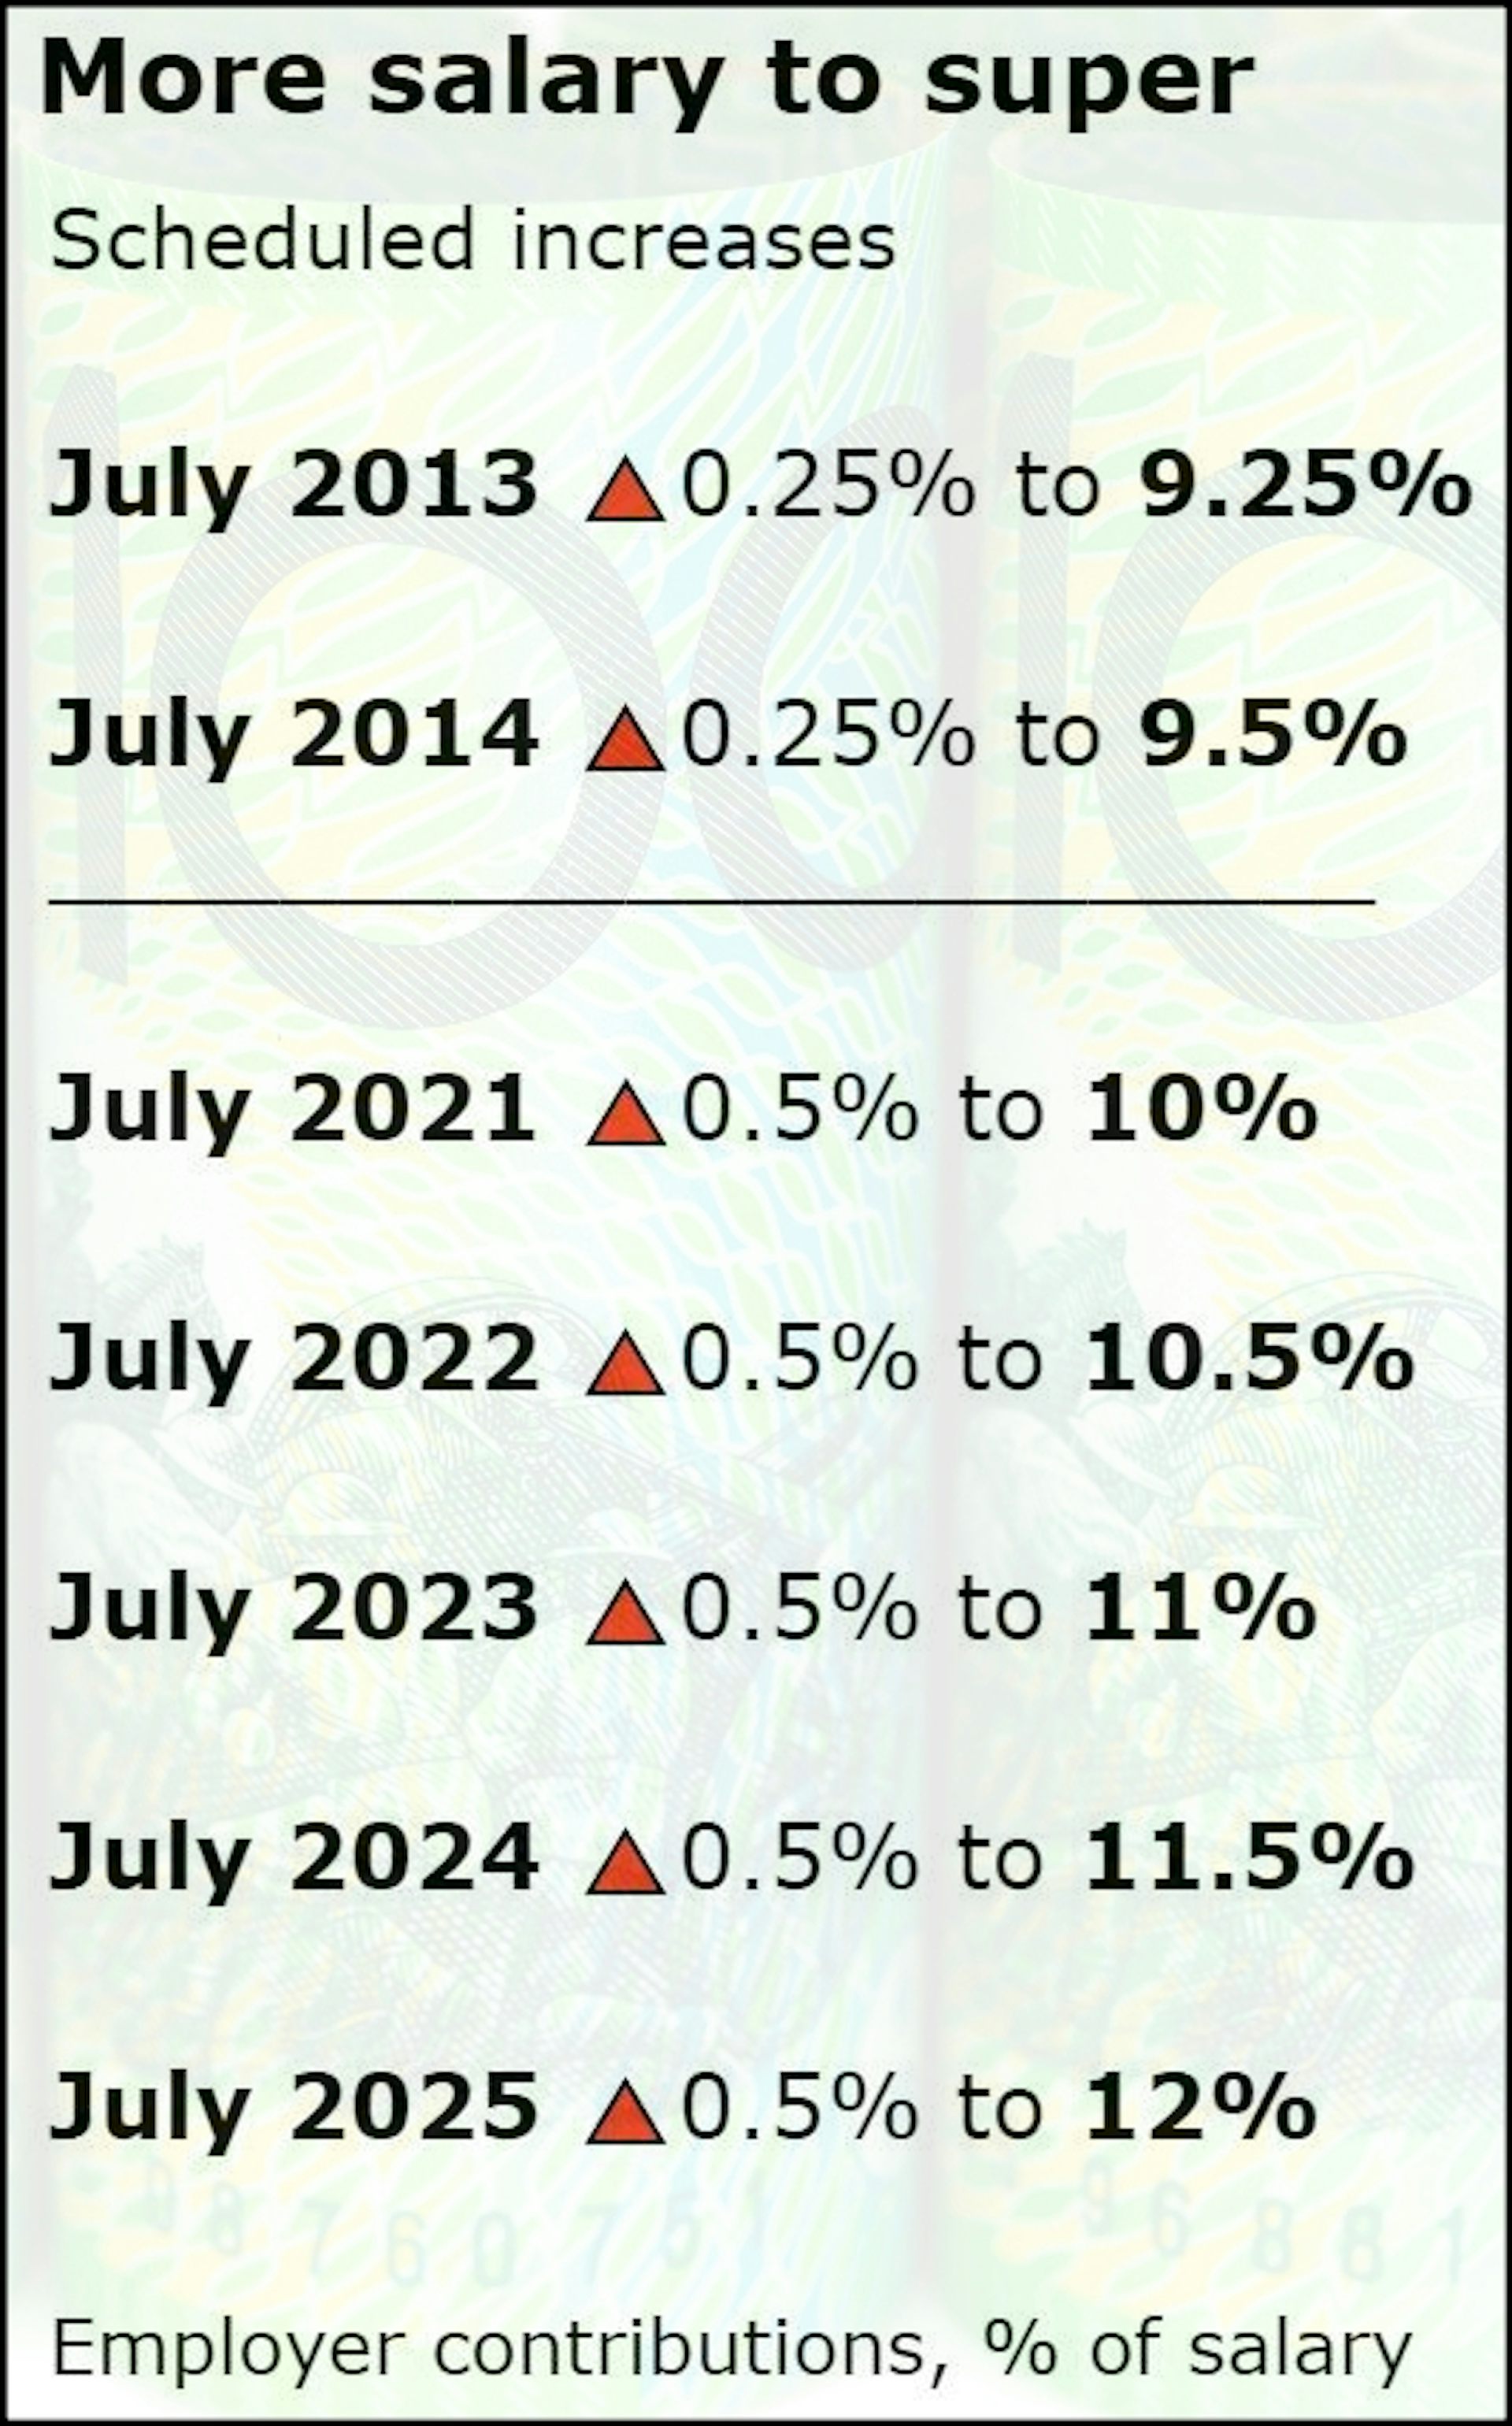
The next increase (actually, the next five increases) will hurt.

The last two, on July 1 2013 and July 1 2014, took place when wage growth was stronger. In 2013 wages growth was 3% per year.

And they were small – an extra 0.25 per cent of salary each.

The next five, to be imposed annually from July 1 2021, are twice the size: 0.5% of salary each.

If taken out of wage growth, they’ve the potential to cut it from its present usually low 2.3% per annum to something with a “1” in front of it, pushing it below the rate of inflation, for five consecutive years.

If we were going to do that (even if we thought the economy and wage growth could afford it) it would be a good idea to have a good reason why. After all, compulsory superannuation is the compulsory locking away of income that could otherwise be spent or used to pay down debt or saved through another vehicle, regardless of the wishes of the person whose income it is.

Question 1. What’s it for?

Fortunately, the new inquiry doesn’t need to do much work on this one.

For most of its life compulsory super hasn’t had an agreed purpose. At times it has been justified as a means of restraining wage growth, at times as means of restraining government spending on the pension, at times as means of boosting national savings.

In 2014, more than 20 years after compulsory super began, the Murray Financial System Review asked the government to set a clear objective for it, and two years later the government came up with one, enshrined in a bill entitled the Superannuation (Objective) Bill 2016.

The bill lapsed, but the objective at its centre lives on as the best description we’ve come up with yet of what compulsory super is for:

to provide income in retirement to substitute or supplement the age pension

Which raises the question of how much we need. For compulsory super, the answer is probably none. People who want more than the pension and their other savings can save more through voluntary super. People who don’t want more (or can’t afford to save more) shouldn’t.

Question 2. How much do people need?

Assuming for the moment that how much people need in retirement is relevant for determining how much compulsory super they need, the inquiry will need to examine what people need to live on in retirement.

The “standards” prepared by the Association of Superannuation Funds of Australia are loose. The more generous of the two allows for overseas travel every two or so years, A$163 per couple per fortnight on dining out, $81 on alcohol “or equivalent spent with charity or church”.


Read more: Why we should worry less about retirement - and leave super at 9.5%


It isn’t a reasonable guide to how much people need to live on, and certainly isn’t a reasonable guide for how much the government should intervene to make sure they have to live on. They are standards it doesn’t intervene to support while people are working.

And there’s something else. Super isn’t what will fund it. Most retirement living is funded outside of super, either through the age pension, private savings, or the family home (which saves on rent). Most 65 year olds have more saved outside of super than in it, and a lot more than that saved in the family home.

It’s a slight of hand to say that retirees need a certain proportion of their final wage to live on and then to say that that’s how much super should provide.

Question 3: Does it come out of wages?

The best guess is that, although paid by employers in addition to wages, compulsory super comes out of what would otherwise have been their wage bill.

Treasury puts it this way:

Though compulsory superannuation guarantee contributions are paid by employers, wage setting generally takes into account all labour costs. As such, it is widely accepted that employees bear the cost of higher superannuation guarantees in the form of lower take home pay.

The inquiry will probably make its own determination. If it finds that extra contributions do indeed come out of what would have been pay rises, it will have to consider the tradeoff between lower pay rises (and they are already very low) and the compulsory provision of more superannuation in retirement.

Question 4: Does it boost private saving?

It’d be tempting to think that the compulsory nature of compulsory superannuation meant that each extra dollar funnelled into it increased retirement savings by an extra dollar. But it doesn’t, in part because wealthy Australians who are already saving a lot have the option of offsetting it by saving less in other ways.

For them, the increase in saving isn’t compulsory.

For financially stretched Australians unable to afford to save (or for Australians at times in times life when they can’t afford to save) the compulsion is real, and unwelcome.

The inquiry will have to make its own assessment, updating Reserve Bank research which found in 2007 that each extra dollar in compulsory accounts added between 70 and 90 cents to household wealth.

Question 5: Does it boost national saving?

Boosting private saving (at the expense of people who are unable to escape) is one thing. Boosting national savings (private and government) is another. The tax concessions the government hands out to support superannuation are expensive. The concession on contributions alone is set to cost $19 billion this year and $23 billion in 2022-23, notwithstanding some tightening up. It predominately benefits high earners, the kind of people who don’t need assistance to save.


Read more: Myth busted. Boosting super would cost the budget more than it saved on age pensions


On balance it is likely that the system does little for national savings, cutting government savings by as much as it boosts private savings. But because the question hasn’t been asked, not since the Fitzgerald report on national saving in 1993 shortly after compulsory super was introduced, we don’t know.

It’ll be up to the inquiry to bring us up to date.The Conversation


Peter Martin, Visiting Fellow, Crawford School of Public Policy, Australian National University

This article is republished from The Conversation under a Creative Commons license. Read the original article.

Read more >>

Friday, September 27, 2019

The dirty secret at the heart of the projected budget surplus: much higher tax bills

The budget is bouncing out of deficit and is set to stay in surplus for the decade to come.

That’s what the April budget and the final budget outcome for 2018-19 tell us, and Thursday’s report from the Parliamentary Budget Office doesn’t say any different.

It doesn’t have much choice. The Parliamentary Budget Office is required to take the government’s surplus and deficit projections for the next four years as given, and to take its economic forecasts and tax and spending announcments for the next ten years as given, whether realistic or not.

What it is allowed to do, and does once a year in a publication entitled medium-term fiscal projections, is to set out the implications of those projections.

Those implications, spelled out on Thursday, show the projected budget surplus to be so fragile as to be unrealistic, except the parts that rely on much higher personal income tax collections.

That’s right: much higher income tax collections per person, even after taking into account the coming decade of legislated tax cuts.

Middle earners hit hardest

But it won’t be higher for all of us.

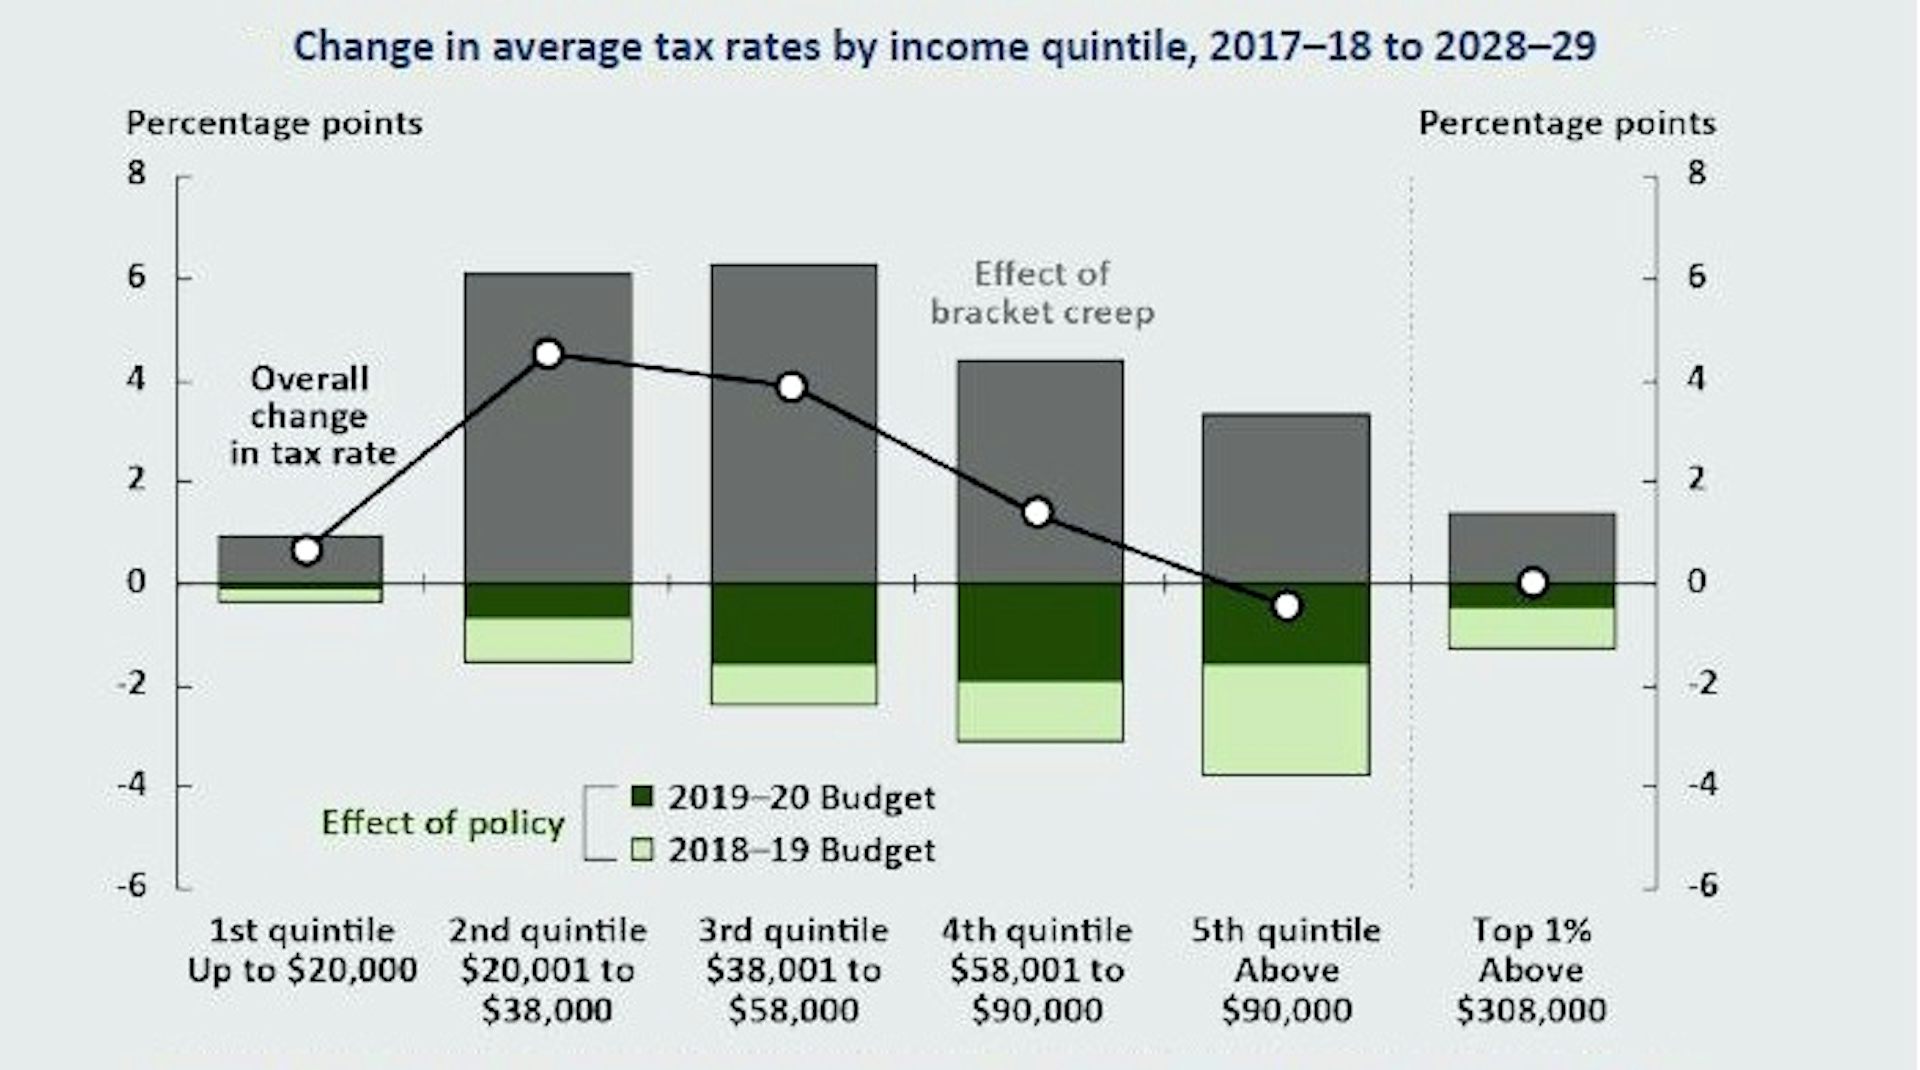
The middle fifth of earners will pay far more of their income in tax in ten years’ time under the government’s projections, according to the PBO’s calculations. Instead of paying 14.9% of their income in tax, by 2028-29 they will pay 18.8%.

That’s after taking into account the long-term tax cuts the government pushed through parliament in May and went to the election on.

Without those legislated tax cuts, they would have been paying an extra 6.3% of their income in tax. With the legislated cuts (and others pencilled in by the PBO to keep the government’s tax take within its promised ceiling) they will be paying an extra 3.9%.

Put another way, the government’s tax cuts will undo some of the damage caused by bracket creep as more of each pay packet climbs into higher brackets, but not most of it.

It’s the same for pattern for the second-lowest fifth of earners. They will move from paying 5.3% of their income in tax to 9.9%, a near doubling, which is taken is taken into account in the surplus projections.


Read more: Those future tax cut promises... they're nowhere near as big as you'd think


The second-highest fifth will move from paying 22% of their income in tax to 23.4%, even after the tax cuts. The bottom fifth, who don’t pay much tax, will move from paying 0.6% to 1.2%.

Highest earners escape

But workers in the top fifth, which at the moment is workers earning above A$90,000, won’t pay a cent more, at least not on average.

The government’s projections, as spelled out by the PBO, have them paying less of their income ten years from today than they do today.

Put another way, they are the only fifth of the population that won’t be expected to wear pain to keep the budget surplus.

There are other contributors to the budget surplus. One is a pretty hefty assumed decline in growth in government spending over the next decade, amounting to 1% of GDP, taking government spending from around 24.9% of GDP to around 23.9%.

Much of it is projected to come from tighter eligibility criteria for payments, and measures to constrain their growth, something the PBO believes might be difficult to maintain:

The spending restraint seen over the past few years may be increasingly difficult to maintain over coming years given the length of time over which restraint has been applied, the pressures emerging in some spending areas, and the potential need for fiscal stimulus, noting that the projected improvement in the budget balance is mildly contractionary.

What it is saying, gently, is that it the longer the government attempts to restrain spending (for instance by imposing tough conditions on access to benefits and using debt collectors to recover alleged overpayments), the harder it will get.

And it is saying the government might need to spend in ways it hasn’t accounted for, including on measures to support the economy in the event of a downturn.

Budget conventions to the rescue

The projections assume the opposite of a downturn.

No blame should attach to this government for them, but our rather odd budget conventions dictate that the worse the economy is, the better the budget’s projections for economic growth. That’s right: the weaker our current economic growth, the stronger the budget’s projections for future economic growth.

The thinking is that over the long term, the economy should grow at roughly its long-term average growth rate. To get there when the economy is weak, as it is now, the budget assumes several years of stronger than normal economic growth to catch up.


Read more: Their biggest challenge? Avoiding a recession


In this case it’s five years of stronger than normal economic growth.

The PBO contents itself with the observation that economic growth that was merely normal (or worse, remained weaker than normal) for some of those years would have a “significant and compounding effect on the budget position over time.”

The surplus is far from assured, and it shouldn’t be. The government might well find that it can’t and shouldn’t restrain spending on payments as much as is projected in the decade ahead, and it might find it needs to spend to support the economy.

It will almost certainly find that lifting the tax take on middle Australians from 14.9% of income to 18.8% is intolerable.The Conversation


Peter Martin, Visiting Fellow, Crawford School of Public Policy, Australian National University

This article is republished from The Conversation under a Creative Commons license. Read the original article.
Read more >>

Friday, September 20, 2019

It's Newstart pay rise day. You're in line for 24 cents, which is peanuts

Newstart recipients and other Australians on benefits get their half-yearly pay rise today (and also on March 20). This one is vanishingly small.

Announced very quietly by Social Services Minister Anne Ruston earlier this week, it amounts to just A$3.30 per fortnight for someone on the Newstart unemployment benefit.

That’s $1.65 per week, less than 24 cents per day.

It’s enough to buy about 36 peanuts – or more if you buy them in bulk.

More galling still for Australians on Newstart, age and disability pensions will increase by twice as much - $6.80 per fortnight, an increase the government was keener to highlight in its press release than the increase in Newstart.

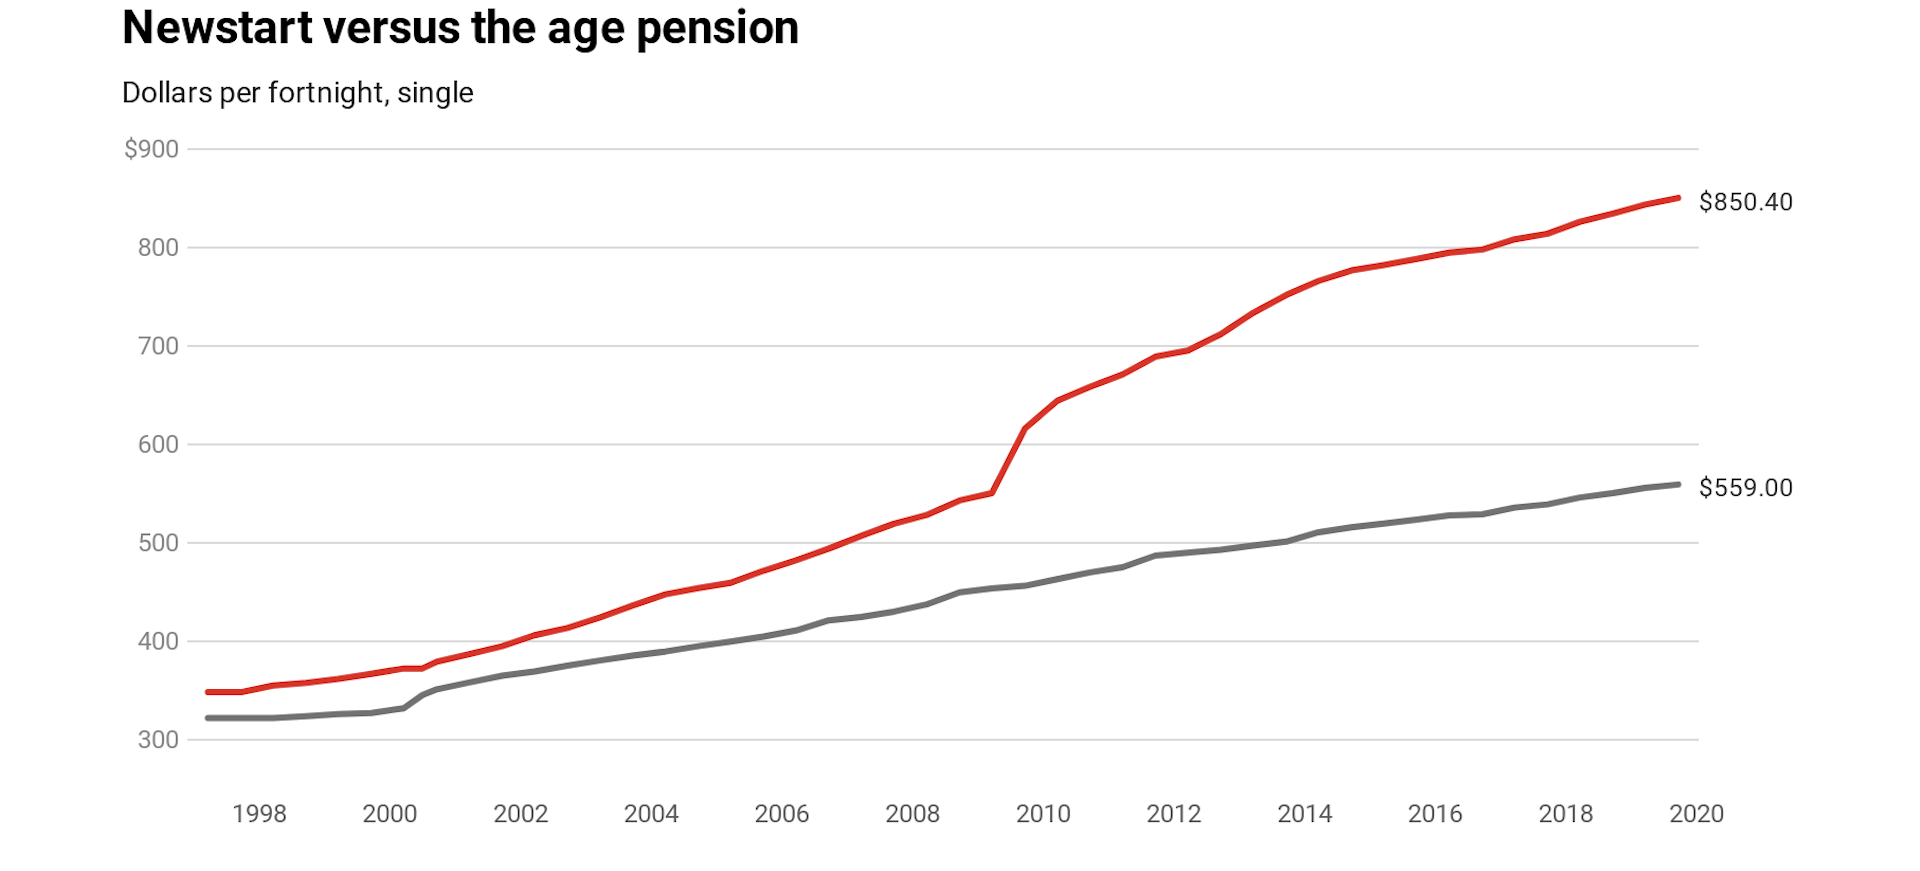
It is hard to comprehend how it could have come to this. Back in 1997 Newstart and the pension were about the same in dollar terms. Each was probably somewhat less than a single person needed to live on.

How did it come to this?

Then the Howard government effectively froze Newstart, forevermore increasing it only in line with inflation (which back then was typically 2.5% per year) while using a formula that lifted pensions in line with wage growth or inflation, whichever was the bigger (back then wages were growing by more than 3% per year).

The difference wasn’t big, but over the past two decades it has compounded. Prime Minister Kevin Rudd helped it along in 2009 by a one-off $64 per fortnight increase in the single pension, unmatched by an increase in Newstart.


It means that from today the single pension will be $850.40 per fortnight, while the single Newstart payment will be $559 – a mere two-thirds of the pension.

And it’ll get worse.

Because inflation is low, and each low increase is off what is now a much lower base than the pension, Newstart increases are small while pension increases are twice as big.


Read more: FactCheck: do 99% of Newstart recipients also receive other benefits?


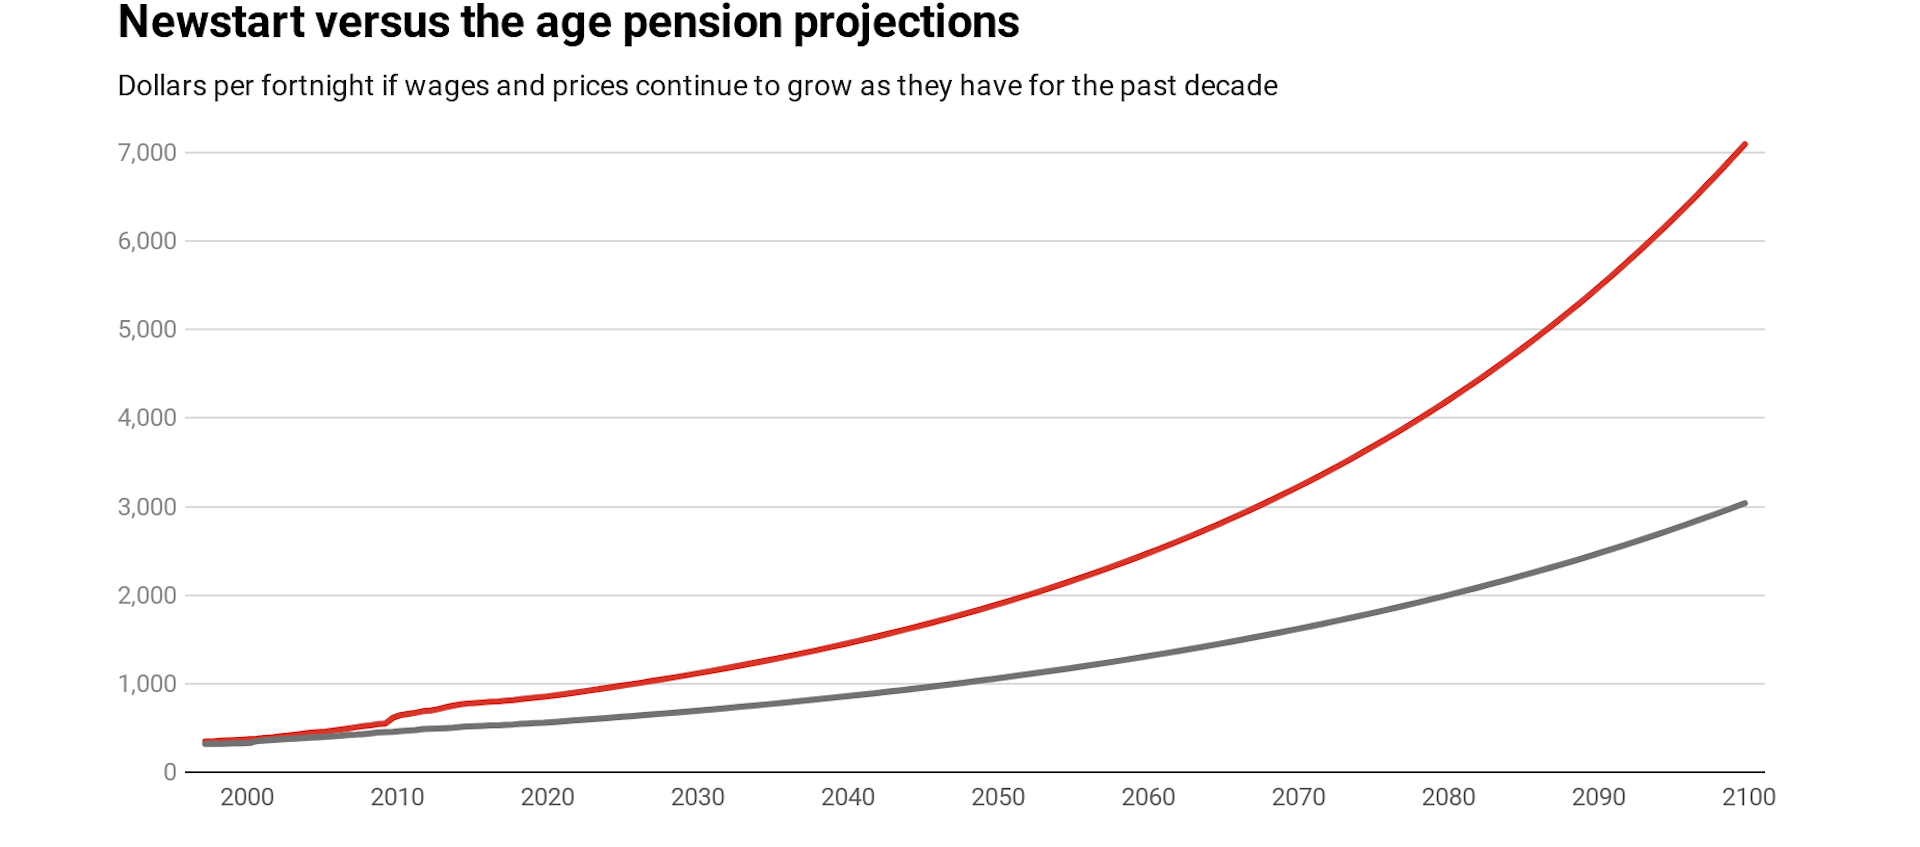
If prices and wages continue to grow at the rates they have over the past decade (2.1% per year for prices, 2.7% for wages) by 2070 Newstart will be just half of the pension. By the end of the century it’ll be just two fifths of the pension.


If it can’t continue, it won’t

Herbert Stein was an economic advisor to US presidents Nixon and Ford. These days he is best remembered among economists for Stein’s Law, which says pithily:

If something cannot go on forever, it will stop.

It’s a warning against the dangers of extrapolations of the kind I have just done, and also a guide to the future. A Newstart rate of just two fifths of the pension, way below everyone else’s standard of living, would be intolerable.

The formula will change well before it gets that bad. It’ll have to.

John Howard himself said so last year:

I was in favour of freezing when it happened, but I think it has probably gone on too long.

The question is how it will change. Labor promised a review and an increase during the last election.

The Coalition is holding firm, although it can’t if it continues to remain in office.

A decade ago the Organisation for Economic Co-operation and Development warned that Newstart was low enough to raise “issues about its effectiveness in providing sufficient support for those experiencing a job loss, or enabling someone to look for a suitable job”.

The budget surplus will help

The Australian Council of Social Service wants the government to lift Newstart by $150 per fortnight to $709, still well short of the pension, and afterwards to lift it in line with the pension and wages, so that it never falls further behind.

It wants the same for Youth Allowance, Austudy, Abstudy, Sickness Allowance, Special Benefit, Widow Allowance and Crisis Payment, which all move in line with Newstart.

The hit to the budget would be $3.3 billion per year, small enough to be funded by projected surpluses.


Read more: Are most people on the Newstart unemployment benefit for a short or long time?


And it would get smaller. Deloitte Access Economics says that after some years about $1.5 billion per year would return to the budget in extra tax as Newstart recipients and the other beneficiaries spent what they were given and boosted economic growth.

They’d have to.The Conversation


Peter Martin, Visiting Fellow, Crawford School of Public Policy, Australian National University

This article is republished from The Conversation under a Creative Commons license. Read the original article.

Read more >>

Wednesday, September 04, 2019

GDP. Why we've the weakest economy since the global financial crisis, with few clear ways out

The Australian economy is tepid, with consumer spending the weakest in ten years, business investment shrinking, and economic growth too weak to cover population growth.

Were it not for very strong growth in export income and the biggest surge in government spending in 15 years, the economy would have shrunk.

The Treasury believes the Australian economy is capable of growing at a sustained annual pace of 2.75%. The growth rate in the past financial year of 1.4% reported on Wednesday is only half that.

Not since September 2009 has the gap between what the Australian economy is capable of and what it has been delivering been so wide. 2009 was the year of the global financial crisis.


Real GDP growth


Economic growth has rarely been as low as 1.4% outside of a recession.

When account is taken of population growth, income and production per citizen went backwards. The last time that happened was during the financial crisis. The last time before that was during the early 1990s recession.

Household spending, which accounts for more than half of total spending, also failed to keep pace with population growth. The inflation-adjusted growth rate of 1.4% was also the lowest since the financial crisis.


Growth in household consumption


Other figures released on Tuesday show retail spending dipped a further 0.1% in July.

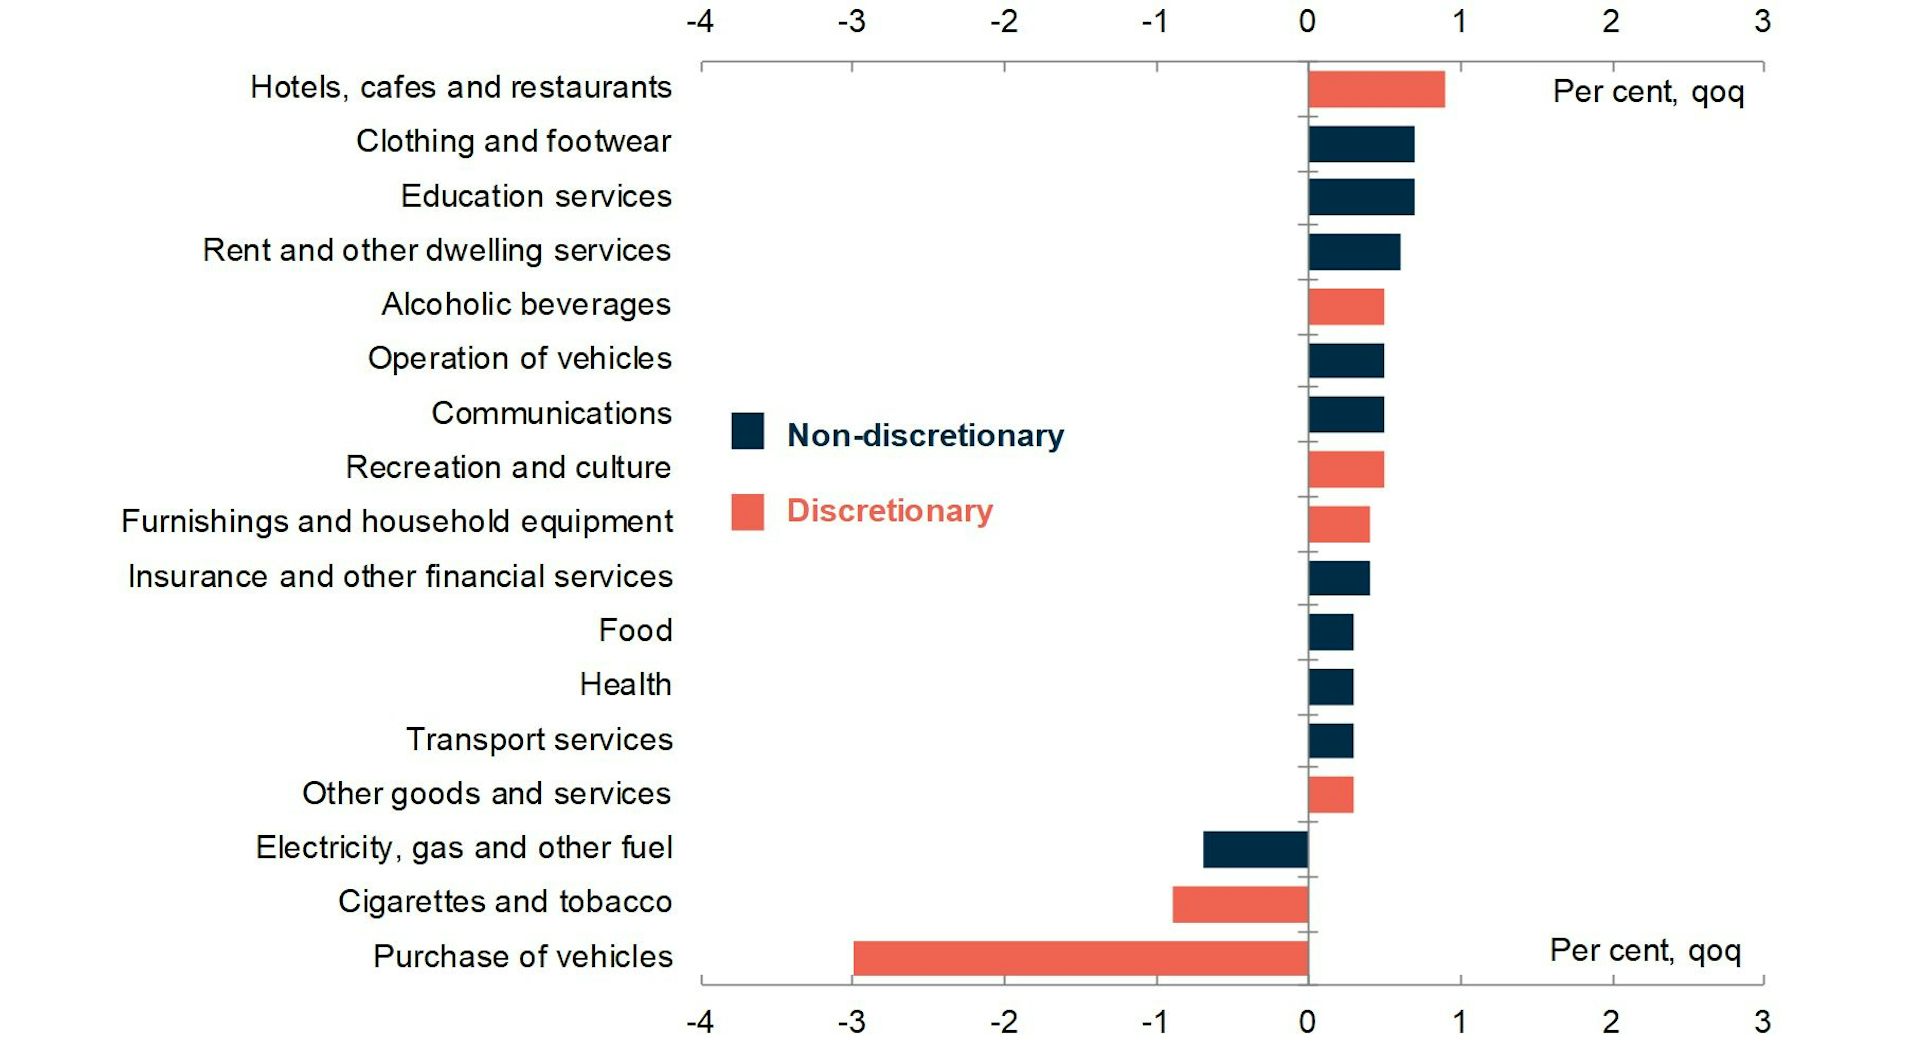
Hardest hit in the 2018-19 financial year was spending on cars. Updated figures released at the same time as the national accounts show sales of new cars down 10% over the year to August.

Treasurer Josh Frydenberg said he preferred to think that households were delaying rather than abandoning purchases of cars, waiting until the economic outlook was clearer.


Growth in consumption by category


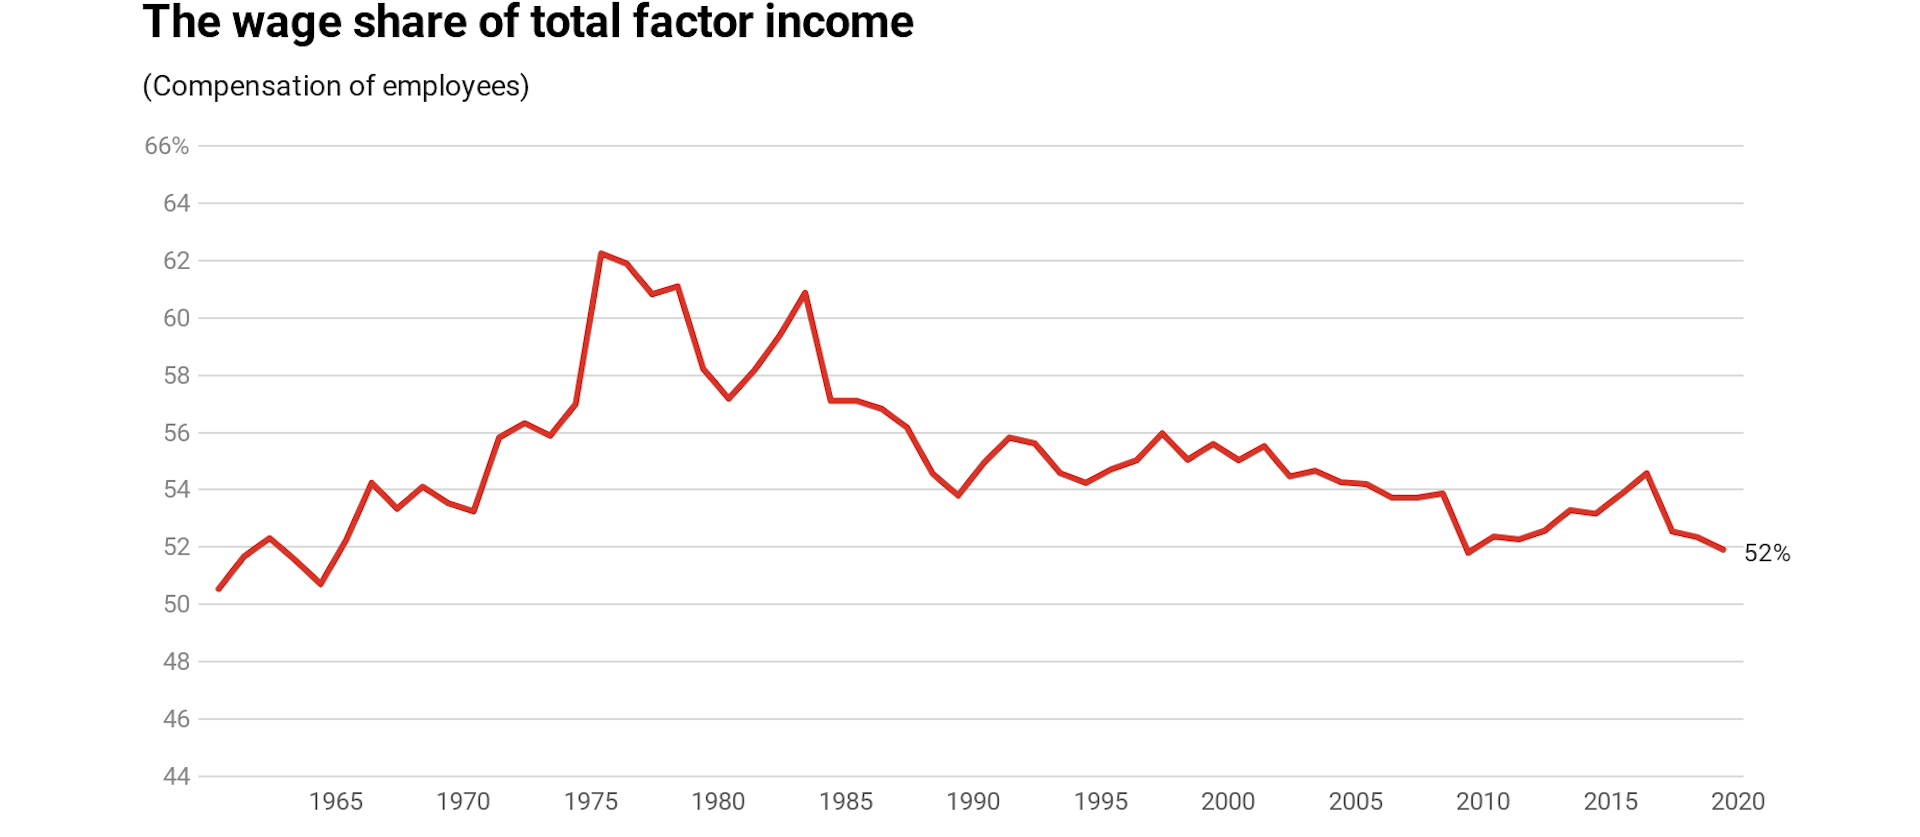
Weighing on consumers is an extended period of unusually low wage growth that the national accounts show has brought the share of national income paid out as wages down to just about its lowest point since 1964.

Although the wage and superannuation bill increased, climbing 5% over the year as employment grew, the share of national income paid out as wages and super fell to 52% – the lowest since the global financial crisis, and before that the lowest since the Beatles toured Australia and Donald Horne published The Lucky Country.


Also weighing on consumers has been housing. Investment in housing (including alterations and additions) was down 9.1% over the year. Business investment fell 10%.

Company profits grew 12.8%, but leaving aside mining companies, whose profits grew strongly on the back of higher prices and export volumes, other profits grew only weakly, climbing 1.8%.

Mining income pushed up nominal GDP (the raw dollars unadjusted for prices that drive nominal incomes) up a healthy 5.4%, probably delivering the government a budget surplus one year earlier than promised, in 2018-19. Frydenberg said he already knew the result and would unveil it in a fortnight. His smiles suggested it’s one he likes.


Nominal GDP growth


Mining income also pushed up what the Reserve Bank regards as the best measure of actual living standards, which (perhaps surprisingly) is not GDP per capita, which is going backwards, but a lesser known and purpose-designed measure known as “real net disposable income per capita”. It grew a healthy 2.65% over the year and a very healthy 1% over the quarter.

It is true that much of it was paid out in mining profits, but it is also true that it isn’t necessarily right to latch on to the cruder measure of GDP per capita and say that living standards are going backwards.

Helping maintain living standards was a very healthy growth in government spending, the highest for some time – not government infrastructure spending, that actually fell over the year as some state projects wound up, but day-to-day spending on things such as the National Disability Insurance Scheme.


Oddly, because of the way the national accounts work, economic growth was also helped by a slump in imports, down 2.8% over the year due largely to a slump in imports of consumer goods.

The economy is in a bad way. Aside from mining and government spending, the only real bright spot is employment growth, and as the Reserve Bank often points out, employment growth doesn’t tell us much about what’s going to happen.

It tends to lag everything else in the economy, by up to nine months. By the time it turns down, other things already have.

Few clear ways out

Frydenberg doesn’t seem too worried. For now he is banking on the tax cuts and the interest rate cuts in June and July to lift investment and spending.

The treasurer has two Plan Bs. One is an aggressive investment allowance for business. He spoke about introducing one last week, but on Wednesday he indicated that he wasn’t planning to do so until next year’s May budget. If needed, he could bring the date forward.

The other is another Reserve Bank rate cut, most likely at the board’s meeting on Melbourne Cup Day, by which time it will have before it an updated set of inflation figures.


Read more: 'Back yourself' Treasurer Frydenberg tells business. But it's not that simple


Frydenberg revealed on Wednesday that he is taking a close look at the government’s contract with the Reserve Bank, a formal written agreement which is renewed after each election.

He has asked the Treasury to look at it to see whether it needs to be tightened to make the bank more responsive to the state of the economy. This would mean more boldly cutting or pushing up rates.

In Britain, if inflation is 1 percentage point above or below the Bank of England’s target, it has to write to the government to explain why.The Conversation


Peter Martin, Visiting Fellow, Crawford School of Public Policy, Australian National University

This article is republished from The Conversation under a Creative Commons license. Read the original article.
Read more >>

Tuesday, September 03, 2019

After 44 years of deficits, we've a current account surplus. What went so right?

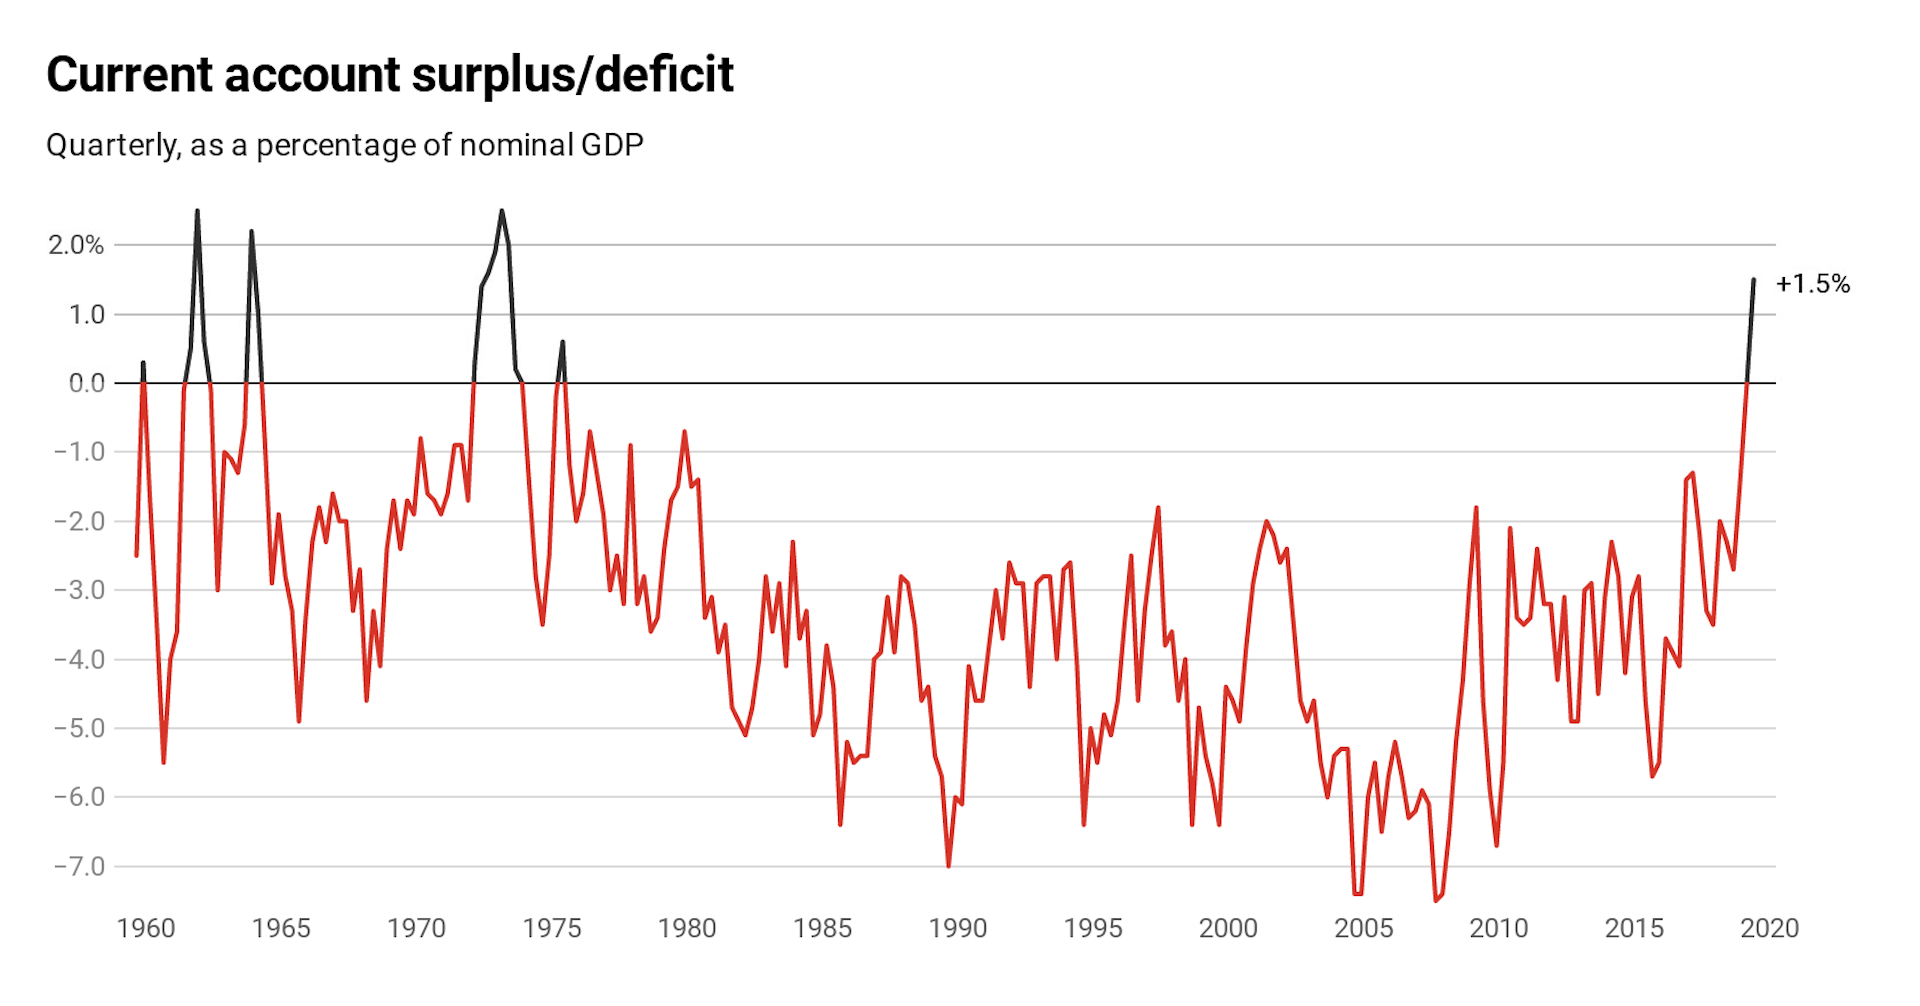
Australia has been in a current account deficit – paying more money out to the rest of the world than it took in – for 44 straight years, since September 1975.

Until today. The update from the Bureau of Statistics released on Tuesday shows that in the three months to June Australia actually took in more from the rest of the world than it paid out: A$5.9 billion more, after what for most Australians (most are under the age of 40) was a lifetime of paying out more.


Why has it happened, and how did we get away with doing the opposite for so long?

First, the long-term story. It couldn’t happen to an individual. No one person can get away with taking more in from the rest of the world than they pay out for long.

It was the idea that a nation is like an individual that allowed the then treasurer Paul Keating to spend a good deal of the 1980s arguing that Australia was living beyond its means.

As the drumbeat of a steadily growing current account deficit grew louder and it approached 5-6% of GDP, on May 14, 1986, he infamously told radio presenter John Laws that Australia was in danger of becoming a banana republic:

I get the very clear feeling that we must let Australians know truthfully, honestly, earnestly, just what sort of international hole Australia is in. It’s the prices of our commodities — they are as bad in real terms (as) since the Depression.

If this government cannot get the adjustment, get manufacturing going again, and keep moderate wage outcomes and a sensible economic policy, then Australia is basically done for. We will just end up being a third-rate economy … a banana republic.

To get spending down, and thus reduce the current account deficit, he tightened the budget and encouraged the Reserve Bank to push interest rates to stratospheric levels. The cash rate hit 18% before helping push Australia into recession .

And for what? The current account deficit continued. It averaged 4% of GDP throughout the 1990s and 2000s. But life went on. The economy recovered, the Bureau of Statistics stopped publishing monthly current account figures (moving to quarterly), the figures became little watched and the pundits and politicians turned their attention elsewhere.


Read more: Cabinet papers 1990-91: lessons from the recession we didn’t have to have


With the benefit of hindsight it is clear that the deficits weren’t because of any deficiency on the part of Australians. Reserve Bank deputy governor Guy Debelle explained last week that Australians weren’t spending an unusual amount compared to what they earned. They were “about on par with many other advanced economies”.

The current account deficits were largely the result of money flowing out as returns on investments in Australia. Australia had “a lot of profitable investment opportunities”. Foreigners either lent to Australian businesses or invested in Australian businesses and returns flowed out each month, as they should have.

It came to be known as the “consenting adults” theory of international finance. It’s practical message was: “nothing to see here, move along”.

So what’s changed?

In 2017 and 2018 the current account deficit shrank to around 2% of GDP. We now know that in the three months to June this year it moved into surplus.

Much of it is because we’ve been earning more from mining exports. We’re both exporting more tonnes and getting paid more for each one.

And just lately mining has helped in another way. The so-called mining investment boom is winding up. We are no longer importing enormously expensive machines to build gas terminals and the like.

And it’s more than mining. Export income from services such as education and tourism now accounts for 21% of all exports, up from 17% in the 1980s. Purists will complain that education and tourism aren’t actually exported, but as far as the national accounts are concerned, they are. Even though the teaching and hospitality takes place in Australia, it is paid for in foreign dollars that bring more money into the country relative to what is going out.

And there’s something else.

We are becoming like the US

As popular as Australia remains as a destination for foreign investment, since 2013 Australians have been investing even more in foreign businesses than foreigners have been investing in Australian businesses.

It is superannuation that’s done it: a record A$2.9 trillion worth.

Debelle put it this way:

This largely reflects the significant allocation to foreign equity by the Australian superannuation industry together with the fact that the superannuation sector is relatively large as a share of the Australian economy.

Australia has become a net foreign investor rather than a net recipient of foreign investment, almost certainly for the first time ever.

Debelle says it has made Australia come to resemble the United States. We receive more in dividends from overseas than we pay out in dividends to overseas share holders.

We’re still a magnet for foreign dollars

We are still a huge destination for foreign lending, increasingly in the form of lending to the Australian government rather than to Australian companies, as safety-conscious foreigners push locals out of the way to buy more and more Australian government bonds.

Foreign ownership of Australian government bonds has climbed from around 40% to 60% since the early 2000s.

The interest rate foreigners are prepared to accept in order to hold Australian 10 year bonds has fallen below 1% (which in its own way assists in keeping the current account deficit low).


Read more: Revisiting the banana republic and other familiar destinations


How long the current account surplus lasts will depend on the investment policies of our super funds (the better the prospects are overseas, the higher the surplus will be), the strength of our economy (the weaker is consumer spending, the higher our current account surplus will be) and export prices and volumes (which are mainly beyond our control).

Yes, we’ve current account surplus. It would have once been a cause for celebration. Now that we’ve got it, it’s not looking that special.The Conversation


Peter Martin, Visiting Fellow, Crawford School of Public Policy, Australian National University

This article is republished from The Conversation under a Creative Commons license. Read the original article.
Read more >>

Friday, August 23, 2019

Book review. Banking Bad, A Wunch of Bankers

Banking Bad, Adele Ferguson, ABC Books, $34.99
A Wunch of Bankers, Daniel Ziffer, Scribe, $32.99
It’s Your Money, Alan Kohler, Nero, $34.99


Inertia can be deeply unhelpful. On those rare occasions when important parts of our world really do change, as they did in the 1980s when our banks suddenly started behaving monstrously, we react as if they haven’t, as if each new piece of bad news is isolated and our financial institutions remain on the whole "world class", as one leading commentator infamously claimed while warding off calls for a royal commission.

Each time an insider from the Commonwealth Bank approached journalists from The Australian and The Sydney Morning Herald before he found Adele Ferguson, they'd tell him the story was "too complicated, too risky, too much work, too this, too that".

Australia's most venerable bank – the one we let into our schools – couldn't be completely rotten.

I thought that myself, even while spending time with the first wave of bank victims who'd been plied with foreign-currency loans whose repayments had exploded to more than their businesses and properties had been worth, taking everything they had.

I put them on PM and AM on ABC radio. But I kept my equilibrium. Surely the banks were still trustworthy institutions that had themselves been victims of currency gyrations just as their customers were. They can't have intended to make them destitute.

David Murray
The first inkling I had that the banks might no longer care about their customers came in a conversation with David Murray, then the head of, or about to become head of, the Commonwealth Bank, and for me the most intriguing person in Ferguson's book, Banking Bad.

He told me the victims of currency loans must have known the risks. One was a maths teacher. But my mother had been a maths teacher and she wouldn't have known the risks unless they had been carefully pointed out to her.

I put it down to an unfortunate lack of empathy on Murray's part, not to a change in the nature of the institution he led.

Ferguson documents the change, while unintentionally documenting her own repeated struggles with inertia as she came to realise the banks were not only selling loans that couldn’t be repaid, not only earning fat commissions and a healthy margin on the currency each time those customers tried to trade their way out of trouble, not only ordering staff to sell products they had no reason to believe were right for their customers (playing happy tones into their ears when they made phone sales and sad tones when they did not), not only deducting fees for advice from the accounts of customers who had died or no longer had advisers, not only allowing crime syndicates to launder money through high-tech automatic machines that whisked it overseas before it could be checked, but also – heartbreakingly – refusing to pay out insurance claims in the face of medical advice that they should, and dragging out cases until their terminally ill customers died or ran out of money (which they could determine by checking their accounts).

Murray was 42 when he was offered the top job at the newly part-privatised Commonwealth Bank. He'd joined it as a teller when it was a public institution with a public-service culture. "It's a bit early, isn't it, for me?" he told the chairman, before transforming it – closing branches, sacking staff, rewarding tellers for sales rather than service, buying an insurer whose products they could upsell, setting up a stockbroker and financial planning arms whose products they could upsell, and imposing relentless never-ending targets. The bank manager at Goulburn in rural NSW was told to sell 150 loans a week. Goulburn had only 10,000 income-earning adults, and four big banks.

It would be tempting to think it was only the bank's staff who cut corners, because of the pressure placed on them. But time after time Ferguson details what happened when their bosses found out.

"Dodgy Don", a financial planner whose legendary ability to sign customers up for almost anything put him at the top of the Commonwealth's league table, was suspended when the bank discovered he had been charging improper fees, putting clients into products for which they were totally unsuited and slipping back-handers to tellers who sent victims his way. Then he was reinstated and promoted to "senior planner".

Staff who tried to help victims were discouraged. At least one was made to sign a legal agreement not to.

Ignorance on the part of the victims, each one believing he or she was alone, was essential if they were to keep quiet and the good public image of the bank maintained.

That's why when Ferguson's Four Corners program (same title as the book) exploded onto the screens in 2014 she was inundated with emails and calls from victims who'd paid up or kept quiet, not knowing they had been part of something systematic.

In Parliament, it was the Nationals who pushed hardest for the royal commission. Several had been victims themselves. Labor, perhaps less in touch with voters, was cautious. The Liberal Party was either profoundly ignorant about the behaviour of the banks or thought it was OK. It blocked just about every move to treat customers better, including (bizarrely) attempting to remove a legislated requirement that financial planners act in the "best interests" of their clients.

When the Liberal Party succumbed, it made the commission's time-frame short and added in a reference to trade union-associated industry super funds, about which there had been hardly any complaints and to which the commissioner gave a clean bill of health.

Ferguson, who covered the hearings for The Age and The Sydney Morning Herald, was astounded by what she heard (some of it was new even to her), but disappointed by the result.

"Vertical integration" of the kind pioneered by Murray at the Commonwealth Bank will be allowed to continue, although for the moment the Commonwealth and two of the other big banks have abandoned it. Murray himself had gone on to chair the Future Fund and then the government’s financial system inquiry, in which he warned against the dangers of vertical integration. During the royal commission AMP appointed him as its chairman, to "lead the redevelopment of governance processes".

Daniel Ziffer doesn't suffer from inertia.

His book, A Wunch of Bankers, is a super-charged flight through the absurdity of the year he spent reporting from the commission for ABC TV.

He gives us the good bits: the Commonwealth Bank might have charged dead people for financial advice, but AMP charged dead people for life insurance.

National Australia Bank flicked commissions to "introducers": gym instructors, architects and other trusted non-experts who pushed $24 billion in loans its way.

The financial services firm IOOF, whose website says it has been "helping Australians achieve financial independence since 1846", decided against putting its members into better products on the grounds they were generally disengaged and wouldn't know the difference.

An unnamed director protested, using caps for emphasis: "In what circumstances would it NOT be in a client's best interest to transfer to the new pricing if it was lower than their existing pricing?"

The unnamed hero later asked, in an observation Ziffer describes as "meta": "How would this look on the front page of The Age?"

Alan Kohler offers practical advice about how not to get ripped off by the finance industry, enlivened with insights from the commission and the inquiries that went before it.

It’s Your Money is an extraordinarily valuable book, but only for people able to take control of their money. As he concedes, many people can't, and it's up to the authorities to protect them. The authorities have failed in that job for the best part of 40 years.

The government has before it recommendations that would help, not only from the royal commission (and unfortunately the government has already backed away from the commission's recommendation regarding mortgage brokers), but also from the Productivity Commission, whose plan to put every new worker into a good super fund is being opposed by an unholy coalition of retail and industry funds.

It's up to those of us who can to keep up the pressure. The financial services industry will. It's been shamed, but never remains shamed for long. Among people who weren't paying attention, it still has a good public image.

In The Age and Sydney Morning Herald
Read more >>

Friday, August 09, 2019

RBA update: Governor Lowe points to even lower rates

Reserve Bank Governor Philip Lowe has said two things about unemployment in the past few weeks. Together, they lead to an inescapable conclusion.

The first was in a speech in May, expanded on in a speech in June. At both times the published unemployment rate was 5.2%.

Lowe said in May that while the Reserve Bank had long thought an unemployment rate of 5% was the best that could be achieved without generating worrying inflation, that view has now changed:

From today’s perspective, I think we can do better than this. My judgement of the accumulating evidence is that the Australian economy can support an unemployment rate of below 5% without raising inflation concerns.

It was good news. And then it got better.

In June he put a number on how low the unemployment rate could go before inflation became a concern:

While it is not possible to pin the number down exactly, the evidence is consistent with an estimate below 5%, perhaps around 4.5%. Given that the current unemployment rate is 5.2%, this suggests that there is still spare capacity in our labour market.

The Reserve Bank should be able to cut interest rates until unemployment fell below 5% and approached 4.5% without worrying about inflation, Lowe argued.

And in May, in a report back from a board meeting, he made it clear that’s what he would do:

At that meeting, we discussed a scenario in which there was no further improvement in the labour market and the unemployment rate remained around the 5% mark. In this scenario, we judged that inflation was likely to remain low relative to the target and that a decrease in the cash rate would likely be appropriate.

It would likely be appropriate to cut interest rates and keep cutting until the unemployment rate was driven below 5%, continuing to cut until it approached 4.5%.

Today, appearing before the House of Representatives economics committee in Canberra with the unemployment rate still stuck at 5.2% despite two consecutive rate cuts, he delivered what on the face of it was bad news.

He said the bank’s central forecast was that the unemployment rate would stay above 5% again until 2021. That’s right, 2021.

But taking the two statements together, it is reasonable to conclude that the Reserve Bank will keep cutting rates until unemployment does fall below 5%. In other words, it will keep cutting rates until 2021.

Lowe ain’t done cutting…

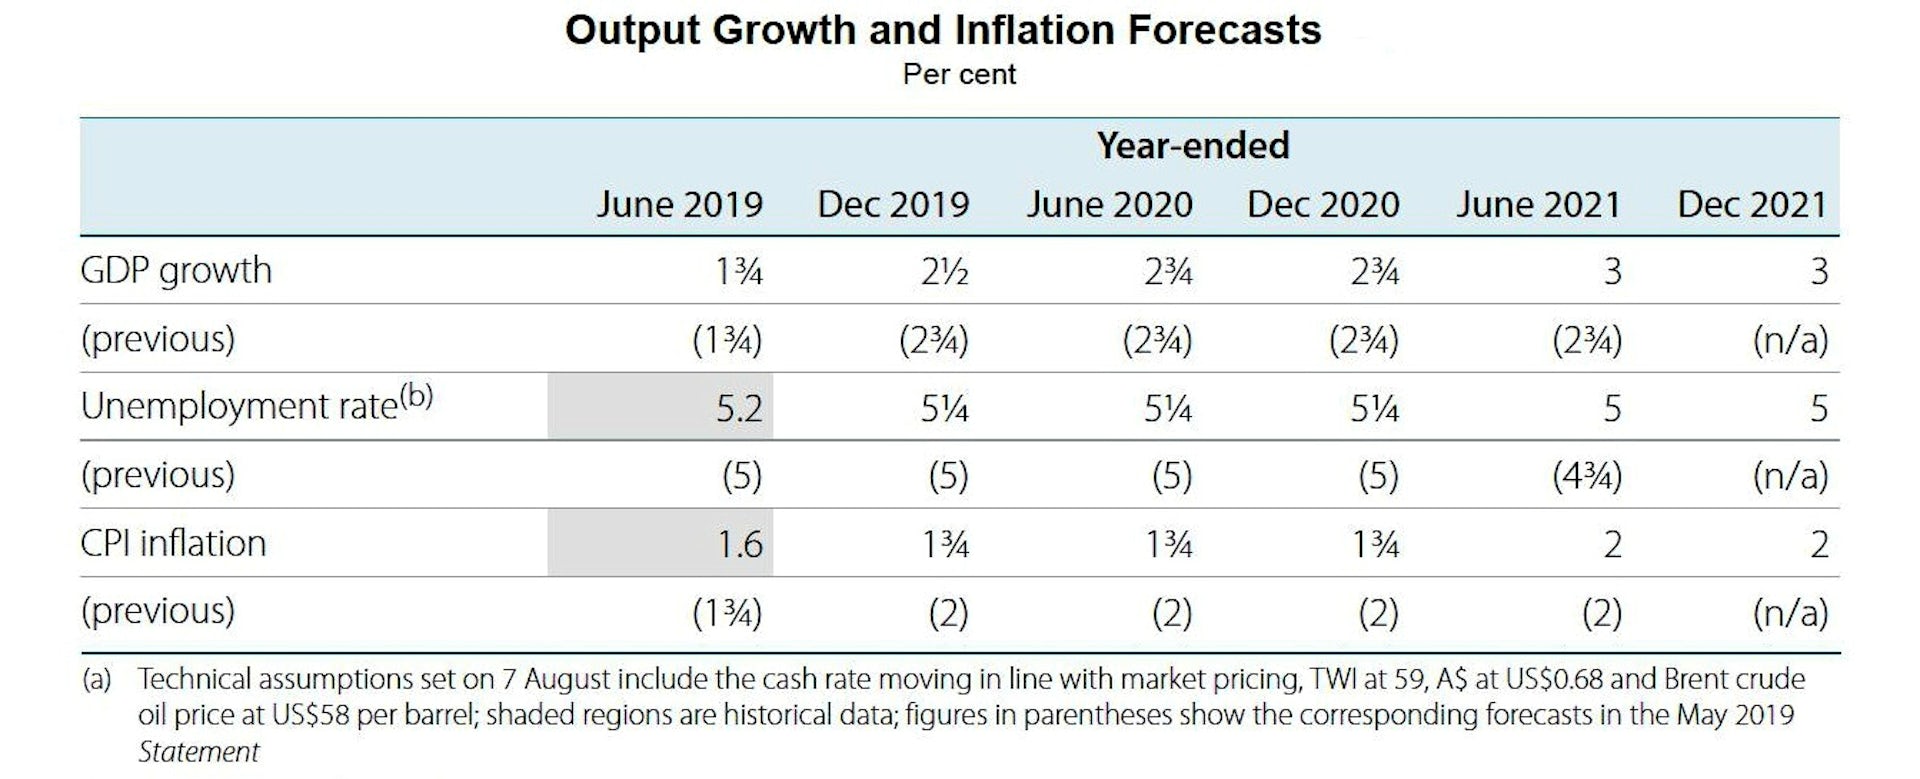
Indeed, the Reserve Bank’s quarterly forecasts update, released as Lowe spoke, countenances that happening. As foreshadowed by the governor, it forecasts that the unemployment rate won’t fall back to 5% until June 2021.

And it contains several other unwelcome forecasts: economic growth of just 2.5% this year, down from a previously forecast 2.75%, and very weak inflation this year of just 1.75%, down from a previously forecast 2%.


But here’s the thing. All of those forecasts were compiled, as is the Reserve Bank’s custom, by taking into account not only the two interest rate cuts that have already happened (and have taken the bank’s cash rate down to an all-time low of 1%), but also two more yet to be delivered.

It is explained in the footnote:

Technical assumptions set on 7 August include the cash rate moving in line with market pricing.

The “market pricing” is the consensus of the bets placed on the futures market for what the Reserve Bank is going to do to its cash rate.

The consensus is for another cut of 0.25% in October and then another cut of 0.25% in February, taking the cash rate down to yet another all-time low of just 0.5%.


The Reserve Bank is normally at pains to point out that this is a mere technical assumption, not a guarantee of how it will move rates. But the awful truth is that its forecasts imply that unless it cut rates two more times in coming months, unemployment won’t fall to 5% by 2021, and inflation will be even weaker than the incredibly weak 1.75% it is forecasting.

…and he might not stop at zero

Two more cuts in its cash rate will take it to 0.5%, close to zero.

Lowe revealed that the Reserve Bank is investigating so-called “unconventional” monetary policy or quantitative easing that would have the same effect as taking the cash rate below zero.

“It is prudent for us to have done the work in advance to see what we would do – it’s really contingency planning,” he said.

Rates might go to zero, or below, worldwide because right now there is a worldwide glut of savings, and not enough investment.

The reality we face is that, if a lot of people want to save and not many people want to use those savings to build new capital, savers are going to get low returns. We can move our interest rates around this new structurally lower level,but we can’t escape the fact that global interest rates are low.

The Reserve Bank’s best case is that its Australian forecasts are wrong - that unemployment actually falls and that inflation, wage growth and economic growth climb.

There’s a respectable view within the bank that this might happen. Its forecasts take into account a range of positive influences, including lower interest rates, the recent tax cuts, the depreciation of the Australian dollar, a brighter outlook for investment in the resources sector, some stabilisation in the housing market, and ongoing high levels of investment in infrastructure.


Read more: Below zero is ‘reverse’. How the Reserve Bank would make quantitative easing work


But they are the result of a mechanical model that takes them into account individually. The governor’s hope is that, taken together, they will achieve more than is forecast.

He would like governments themselves to push things along, starting with the wages they pay their own employees, and he is becoming ever more bold about saying so:

Most public sectors have wage caps of 2.5%, some have 1.5%, I think in Western Australia it’s probably even lower. I can understand why governments are doing that. On the other hand, the wage caps in the public sector are cementing low wage norms across the country. Over time, I hope the whole system, including the public sector, could see wages rising at three point something.

He is as good as powerless to stop what he regards as a worldwide investment strike caused by the trade and technology disputes between the United States and China.

These disputes pose a significant risk to the global economy. Not only are they disrupting trade flows, but they are also generating considerable uncertainty for many businesses around the world. Worryingly, this uncertainty is leading to investment plans being postponed or reconsidered.

Lowe doesn’t believe further interest rate cuts would to do much to encourage businesses to invest, or to encourage home buyers to borrow.

But he is certain they will help in other ways.

They will lower the exchange rate, making Australian goods and services more competitive, and that they will free up the cash of Australians who already have home loans, what he calls the “cash flow” channel:

There is no evidence that has become less effective. It is certainly true that in the current environment, at least in my view, monetary policy is less effective than it used to be. In today’s environment people don’t run off to the bank to borrow more when interest rates fall; they are more likely to pay back their mortgage more quickly. So that dynamic is different than it used to be.

When he last appeared before the parliamentary committee in February he said the probabilities of rates going up and rates going down were evenly balanced. He didn’t say that today.


Read more: Buckle up. 2019-20 survey finds the economy weak and heading down, and that's ahead of surprises The Conversation


Peter Martin, Visiting Fellow, Crawford School of Public Policy, Australian National University

This article is republished from The Conversation under a Creative Commons license. Read the original article.
Read more >>

Tuesday, July 30, 2019

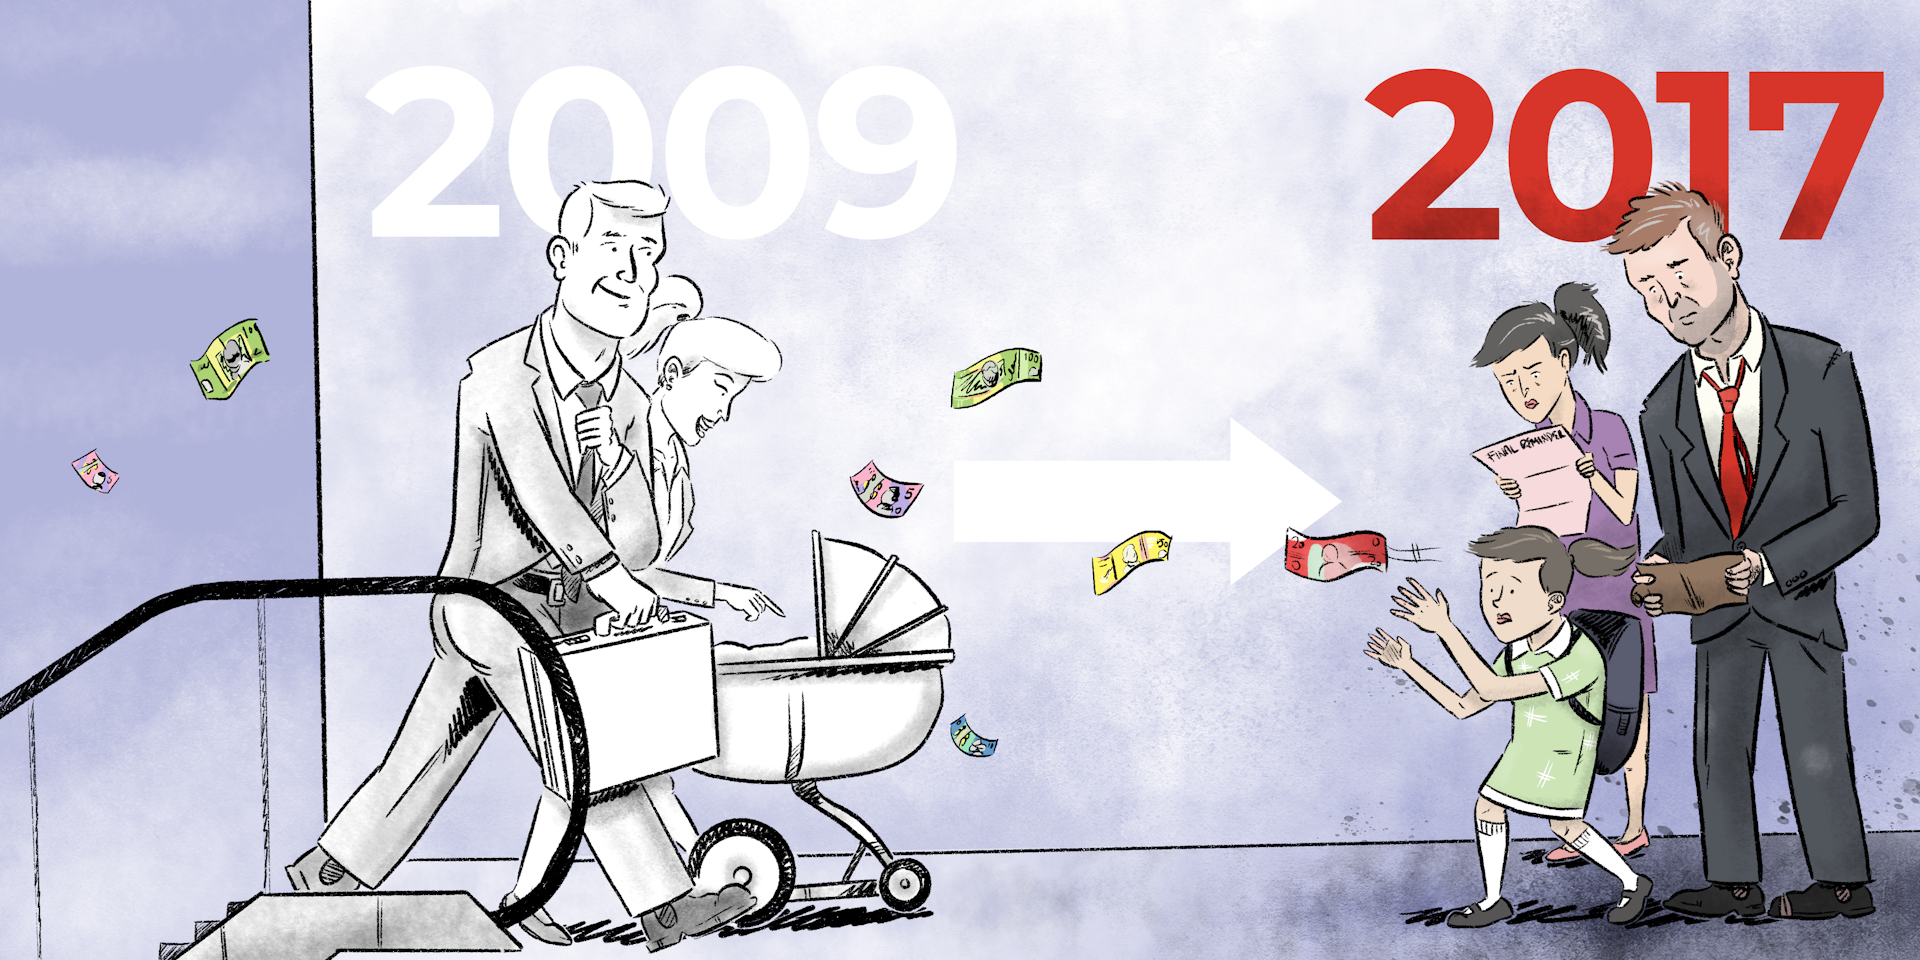
There's a reason you're feeling no better off than 10 years ago. Here's what HILDA says about well-being

During the election campaign then-opposition leader Bill Shorten repeatedly claimed that everything was going up.

“Childcare is up 28%, out of pockets to see the doctor up 20%, specialists … up nearly 40%,” he said. And then the punchline: “everything is going up, except your wages.”

Statistically, it wasn’t true. The official rate of inflation was just 1.3%. The official rate of wage growth was 2.3%.

I haven’t asked him, but I wouldn’t be surprised if he kept saying it because his focus groups told him that’s what people felt.

Today’s release of the 17th wave of Australia’s Household, Income and Labour Dynamics Survey (HILDA) tells us that despite the official statistics, people were right to feel they were going backwards.

Funded by the Australian government and managed by the Melbourne Institute of Applied Economic and Social Research, HILDA is one of the most valuable tools Australian social researchers have.

It examined the lives of 14,000 Australians in 2001 and then kept coming back to them each year to discover what had changed. By surveying their children as well, and in future surveying their children, it will be able to build up a long-term picture of how circumstances change over the course of lives and generations.

It can be thought of as Australia’s Seven Up!, the British TV series that keeps going back for updates on the lives of 14 children it first examined when they were seven. Except that HILDA’s results have statistical significance, and the questions are detailed, asking among other things about depression and anxiety, work-life stress, stress in relationships, and illicit drug use.

We are right to feel no better off…

The Australian Bureau of Statistics does indeed find that wages are climbing faster than prices, as they almost always have, but because it doesn’t examine what happens to a particular household over time it can tell us little about whether an individual’s experience of things is getting better or getting worse.

HILDA gets a handle on each household’s disposable income by asking each member of the household about their gross income from wages, benefits, investments and other sources and then deducting its estimate of taxes. It gets a handle on the real (inflation-adjusted) changes by adjusting its totals for changes in the consumer price index.

It finds that for the thousands of households it interviewed, real disposable income grew strongly during the first nine years of the survey, between 2001 and 2009. Then, after the global financial crisis, for the eight years between 2009 and the 2017 results released today, that growth stalled.


Expressed in today’s dollars, the average annual real disposable income of those households climbed by A$19,773 between 2001 and 2009, about $2,472 per year.

But most of the growth was during the mining boom that stretched from 2003 to 2009 when the average annual real disposable household income climbed about $3,000 per year, as did the income of the more representative median (or middle) household.

Since 2009 and the global financial crisis, the average and the median have moved in different directions.

The average houshold’s annual real disposable income has climbed a further $3,156. The median (or typical) household’s income has fallen $542, although not steadily. The graph shows it falling between 2009 and 2011, climbing in 2012, and changing little thereafter.

…and as if it’s harder to get ahead…

It has also become harder to “get ahead”, in the phrase used often by the prime minister.

Between 2001 and 2005, 40% of the households in the bottom fifth of earners (the bottom qunitile) moved out of it into a higher one. In more recent years, between 2012 and 2016, a lower 38.5% moved up.

Between 2001 and 2005, 44% of the households in the top qunitile had to move down to let other households take their place. In more recent years, between 2012 and 2016, only 41.5% have moved down.

Getting a long way out of the income circumstances you were born in is a long-shot, according on HILDA’s early attempt at measuring intergenerational mobility.

People who were 32-34 years old in 2015-17 are highly likely to be in the same household income quintiles as those people found themselves in when they were 15-17 back in 2001-03.


There’s only a one in ten chance of moving from the bottom quintile as a teenager to the top quintile in your early thirties. There’s a 37% chance you’ll stay put.

Even among teenagers who grew up in the middle quintile, there’s only a 17% chance of making it to the top, along with a 19% chance of moving one rung up.

Interestingly, women turn out to be more tied to the income their families had when they were children than men, and both men and women tend to stay more closely tied to their mother’s income than their father’s.

…yet we are less reliant on welfare, even pensions…

When HILDA began in 2001, 39% of Australians aged 18 to 64 were living in a household that received government welfare of some kind. By 2017, that proportion had fallen to 31%, but almost all of the drop happened before the global financial crisis in 2009.

Most of us are still in households that have received something from the government over a 10-year period: 58% of working age Australians in 2017, down from 64% in 2010.

Among older Australians aged 65 and over, reliance on the age pension and other benefits for more than half of income needs has dropped from 60% to 51%.

Among new retirees aged 65 and over, the proportion receiving the age pension has fallen from 76% of men and 74% of women to just 60% of men and 55% of women.


Read more: More people are retiring with high mortgage debts. The implications are huge


But while the growth of compulsory superannuation is likely to be part of the story, almost all of the decline happened before the financial crisis in 2009, suggesting that the destruction of wealth in the crisis kept people on the pension who otherwise might not have needed it.

…and gender roles are changing

Before the financial crisis, almost three quarters (73%) of men of traditional working age were employed full-time. After the crisis, the rate slipped to a much lower 67% and stayed there.

Female full-time employment was also hit by the crisis but has since almost totally recovered to be just a fraction below its pre-crisis peak of 39.6%.

Women’s hourly earnings are also climbing faster than men’s, up 24% between 2001 and 2017, compared to 21% for men’s.

While women have always been more likely than men to be employed casually, since the crisis male casual employment has climbed while female casual employment has declined.

The two are now as close as they have ever been, with women now only six percentage points more likely than men to be employed causally.


Read more: HILDA findings on Australian families' experience of childcare should be a call-to-arms for government


In dual-earner male-female couples, the proportion in which the woman earns more than the man has climbed from 22% to 25%.

The woman being the main breadwinner is more common in couples that aren’t legally married and don’t have children. It is also far more common in the regions than in cities and among couples in which the man doesn’t have a university degree.

Men in predominantly female breadwinner households are somewhat less happy with their lives and with their relationships, as (perhaps surprisingly) are women.

Fathers tend to agonise more about work-family conflict than mothers, notwithstanding the much greater amount of housework and childcare work performed by mothers. The men who worry the most work long hours, have irregular shifts and very young children. A mother working the same hours as a father will typically be more conflicted.


Read more: Language of love: a quarter of Australians are in inter-ethnic relationships


Most parents suffering high work-family conflict get out of it within a year or two, often by managing things better and sometimes by changing jobs. Those suffering high work-family conflict are 50% more likely than others to separate the next year.

HILDA’s great strength is that it will be able to follow those parents and their children and all the other families it surveys and tell us what happens next. Rather than being an Australian version of Seven Up!, it might be better described as Australia’s never ending story. Its co-director Roger Wilkins says its design allows it to be “infinitely lived”.


Read more: Australian city workers' average commute has blown out to 66 minutes a day. How does yours compare? The Conversation


Peter Martin, Visiting Fellow, Crawford School of Public Policy, Australian National University

Wes Mountain/The Conversation, CC BY-ND

This article is republished from The Conversation under a Creative Commons license. Read the original article.

Read more >>