Tuesday, May 16, 2023

4 ways to bring down rent and build homes faster than Labor’s $10 billion housing fund

Treasurer Jim Chalmers is the first in decades to declare war on what he calls the “pain of rising rents”.

His first budget, in October, and his second, this month, contained a suite of measures designed to stop rents going “through the roof”. By far the biggest of those – the blockbuster – was a A$10 billion Housing Australia Future Fund to finance social and affordable housing.

If you think the idea of building a fund rather than building houses sounds odd, you probably think the same way about the Medical Research Future Fund, the Future Drought Fund, the Disaster Ready Fund or the $250 billion Future Fund itself, which was set up to pay public service and defence pensions.

Those were all previous Coalition government ideas – the likes of which were satirised by ABC TV’s The Hollowmen which in 2008 came up with the idea of a $150 billion National Perpetual Endowment Fund, created for no particular purpose other than “to meet the future challenges of this nation”.

I can think of at least four things that would do more to restrain rents than Labor’s $10 billion fund – and one of them would do it a lot quicker.

$10 billion, but off-budget and largely unspent

The (political) genius of these sorts of funds is they make it look as if you are spending a lot, without the need to spend much at all.

The $10 billion (or whatever that goes into the fund) isn’t actually “spent” as far as the budget is concerned. It doesn’t come off the budget surplus, or add to the budget deficit, because it remains in the government’s hands.

The fund can be thought of as a fiction. The money stays in the government’s hands until some of it is spent, except that while in the government’s hands it is invested in the stock market and other places to try and earn a return. It doesn’t always work. During 2022 the usually successful Future Fund went backwards.


“Rear Vision”, The Hollowmen, ABC.

When Labor came up with the idea of the Housing Australia Future Fund in 2021, it looked a surer bet. Governments could borrow at “ultra-low interest rates” and the returns on investments were good.

To “protect the balance of the fund”, the government has limited withdrawals to $500 million per year, meaning a less-grand-sounding commitment to spend up to $500 million a year would have achieved just as much.

Housing Minister Julie Collins’ counter to that criticism is to say that creating a fund – an “enduring promise” – will protect housing spending from the “whims of future governments”

And yet the legalisation says every piece of spending from the fund will require formal government approval.

Another reason for limiting the amount that can be spent each year (apart from protecting the balance of the fund) is that there are practical limits on how quickly homes can be built.

Limits on how quickly new homes can be built

A truly bizarre and long-established fact of Australian home building is that it never gets done more quickly. If you went back to the 1990s, the 1980s or even the 1970s, you would find that the number of houses completed per quarter was roughly what it is today, between 22,000 and 29,000.


The number of houses under construction varies wildly; at times it has been low, late last year it reached an all-time high. But the number of houses completed seems to chug along at the same rate regardless. All that commencing more builds does is push out construction times.

It’s the same for units, which the Bureau of Statistics classifies as “other residential”. The number being completed per quarter is no higher than it was a decade ago, but the number under construction has climbed much higher.


All that funding more than a small number of extra builds per year would do is push construction costs higher and push out completion times.

The Australian Greens might well be right to oppose the artifice of a “fund,” but they are probably wrong to propose much more spending per year than the $500 million the government is promising and the 30,000 extra homes over five years it says it will deliver.

I can think of at least four things that would restrain rents more than the fund, one of which Chalmers has delivered in the budget, albeit in a small dose.

1. Boost rent assistance

The “largest increase in more than 30 years” in Commonwealth Rent Assistance amounts to $16 per week.

It’ll help the 1.3 million concession card holders who receive it. But it is not much, and not much more in the future, because Chalmers has not acted on the recommendation of his economic inclusion advisory committee to increase it in line with rents actually paid, rather than the consumer price index.

Chalmers might well have been concerned that a bigger increase in rent assistance would have pushed up rents, but there’s a way of dealing with that.

2. Limit rent increases

Price control is anything but uncommon. In most states, increases in the prices we can be charged for electricity, gas and water are limited by regulation. In the Australian Capital Territory, increases in rents are limited by regulation.

The maximum permitted increase is 110% of the most recent annual increase in Canberra rents reported to the Bureau of Statistics. In the year to March, Canberra rents climbed 5.54%, making the maximum permissible increase 6.1%.

It works well, and Canberra landlords don’t seem to have withdrawn from the market. Among Australia’s capitals, Canberra’s rental vacancy rate is the highest.

3. Bribe states and councils to rezone land

Another option is to provide incentive payments to state and local governments that free up their planning systems and build more housing.

Conditional payments are not novel. The Commonwealth provided special payments to states that fell in line with its deregulation agenda for about a decade from the mid-1990s.

4. Restrict negative gearing to new builds

Negative gearing and the concessional rate of capital gains tax that accompanies it drive Australians into becoming landlords. But if they buy existing homes to do it, they do no more than turn owner-occupied homes into rented homes.

Limiting negative gearing to newly-built homes – as Labor promised in 2019 – would get them to fund new builds.

While it’s true that getting more Australians into affordable homes is anything but easy, some of what we need to do is straightforward. We can do better than a grand-sounding big-bucks fund.The Conversation

This article is republished from The Conversation under a Creative Commons license. Read the original article.

Read more >>

Tuesday, May 09, 2023

Budget 2023: budgeting for difficult times is hard – just ask Chalmers

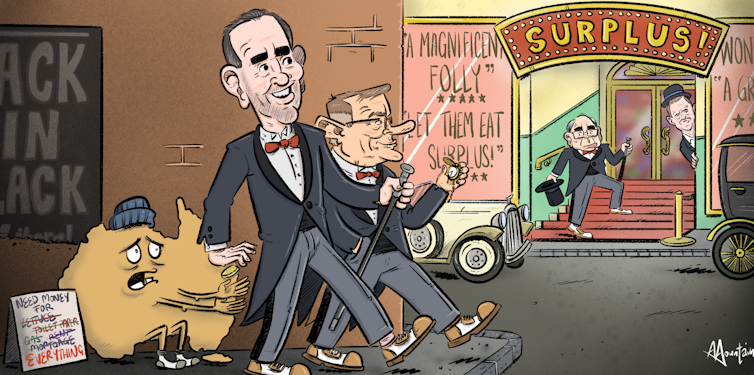
Wes Mountain, CC BY-ND

Surplus or not, the budget papers show us living through pretty awful times.

Living standards measured by the buying power of wages are set to go backwards again in 2023-24 as wages grow by 3.75% while prices rise by 6%.

Separate figures released by the Bureau of Statistics as Treasurer Jim Chalmers was preparing to deliver his speech show the volume of goods and services bought from Australian retailers has shrunk for the past six months.


Living standards measured by gross domestic product are set to go backwards in 2023-24 as total GDP grows by an unusually low 1.5% while Australia’s population grows by 1.7%, producing a so-called “per capita recession”.

The good news on the government’s finances is largely historical.

The good news is old news

The budget positions for 2022-23 and 2023-24 have been improved by $42 billion each because of measures largely outside the government’s control (so-called “parameter and other variations”).

Chief among these has been an unexpectedly big increase in the number of Australians in work and subject to income tax (as the unemployment rate has fallen to a half-century low), and much higher prices for exports than expected (roughly twice as high for case of iron ore), producing more profits to tax.

The government has chosen to spend just $1 billion of the $42 billion bounty in 2022-23 and just $12 billion in 2023-24, which has allowed the rest of the bounty to produce a small budget surplus of $4.2 billion in 2022-23 and a much smaller than expected deficit of $13.9 billion in 2023-24.


Beyond 2022-23, it will be deficits again for at least a decade on the budget’s projections, as the unusual circumstances that delivered the boost fall away.

The unemployment rate is set to climb from its long-term low of 3.5% to 4.25% by mid next year and to 4.5% by mid-2025. The number of Australians in work and in the income tax system is expected to grow by just 1% in 2023-24 and 2024-25 after growing by 2.5% in 2022-23. The iron ore price is expected to halve within a year.

Government income is set to grow 8.8% in 2022-23 and 5.1% in 2023-24. After that, it is scheduled to barely grow in 2024-25, climbing just 0.5%, before returning to growth of 4.4% and 4.9 in 2025-26 and 2026-27.

Given that the costs of some government programs are expected to grow by a lot (the cost of National Disability Insurance Scheme is expected to grow by an average of 10.4% per year and the cost of funding hospitals by 6.5% per year), it looks as if the government is going to have to find more money.

Spending on defence is set to climb 22% over the next four years, and doubtless by more beyond, as spending on building and buying the nuclear-powered submarines under the AUKUS agreement ramps up.


Chalmers has sensibly abandoned the Coalition’s quaint commitment to keep the tax to GDP ratio to 23.9%, which is just as well because the influx of revenue scheduled for 2023-24 will to take it to 23.9% (25.9% including non-tax revenue) before it falls back.


Longer term, Chalmers will have to raise more tax or cut government services. The increases in the tax on large superannuation balances, tobacco excise and the petroleum resource rent tax are a sign of what’s to come.

The ultra-expensive Stage 3 income tax cuts deliver a hard-to-defend $2,000 per year to high earners on $120,000 per year. Although legislated back before COVID, they are not due to take effect until mid next year, meaning there’s still time (and another budget) in which to wind them back and reorientate them to Australians who need them more.

Where Chalmers has supported Australians hit by ultra-high inflation in this budget, he has tried to do it cheaply.

Boosting JobSeeker and related payments by the $128 per week Chalmers’ economic inclusion advisory committee wanted would have cost $5.7 billion per year. Instead, Chalmers will lift it by $20 per week (and slightly more for most Australians on it aged 55 and over) at a cost of $1.3 billion per year.

As important as extending parenting payments to single parents with children up to 14 years of age will be those who need it. The measure is budgeted to cost just half a billion per year.

Boosting Commonwealth rent assistance by up to $16 per week (the “largest increase in more than 30 years”, Chalmers says) will cost a tad more, around $700 million per year.

Boosting Medicare, primarily by boosting payments to general practitioners who bulk bill children and patients on low incomes will cost $1.3 billion per year.

The cost of the energy package (which the treasurer says will take $500 per year off some power bills and three-quarters of a percentage point off inflation) is marked in the budget as “not for publication”, presumably in deference to negotiations with the states which will co-fund it.

Chalmers’ budgets will get harder

Chalmers said during his press conference this budget had been much harder to put together than his first. What he could have added is that his next budget is shaping up to be even harder.

Economic growth has been revised down. So convinced are financial markets the economy is weakening, that ahead of the budget they were pricing in no further Reserve Bank interest rate increases in this year and one interest rate cut, by December.

The economic forecasts in the budget suggest the coming per-capital recession won’t turn into an actual recession. Economic growth is expected to climb from an ultra-low 1.5% in 2023-24 to a still-low 2.25% in 2024-25 and then to 2.75%.


Inflation, which was 7% in the year to March, is forecast to fall to 6% in the year to June, and then to a less-worrying 3.25% by June 2024.

Although the forecasts move in the right direction, they are not good. Chalmers said getting things right this time required a “fine balance”. Future budgets are shaping up to require just as much.


The Conversation

This article is republished from The Conversation under a Creative Commons license. Read the original article.

Read more >>

Tuesday, May 02, 2023

Presented with a JobSeeker finding too clear to ignore, he changed the subject: how Jim Chalmers is shaping the budget

What was Treasurer Jim Chalmers thinking?

Late last year he set up a committee he specifically asked to tell him how bad JobSeeker was.

The exact words in its terms of reference required it to advise him on the “adequacy, effectiveness and sustainability of income support payments”.

It is true that he was sort of forced to. Independent Senator David Pocock made the committee a condition of supporting an unrelated industrial relations bill in the Senate. Its findings had to be published a fortnight before each budget.

Yet Chalmers chose to set a group whose findings would be hard to ignore. He put on it one of Australia’s pre-eminent experts in the adequacy of payments, Professor Peter Whiteford; one of Australia’s pre-eminent experts in labour markets, Professor Jeff Borland; and one of Australia’s pre-eminent experts in calculating disadvantage, Associate Professor Ben Phillips.

To give the “interim economic inclusion advisory committee” extra heft, he added the head of the trade union movement, the head of the Businesses Council, the head of the Council of Social Service and the head of the Treasury.

In short, Chalmers set up a committee he couldn’t ignore. So why is he now so keen to talk about everything but its number one recommendation?

Impossible to ignore

Sometimes committees like these end up making so many recommendations that a minister can pick and choose from them.

And this committee did make 37 recommendations, as Finance Minister Katy Gallagher noted this week saying she was “not going to be able to do everything”.

But, unusually, this committee went out of its way to make sure one recommendation stood out above all others.

It reported that, given its short timeframe, it had:

decided to concentrate on the needs of the largest number of Australians experiencing poverty and disadvantage today, namely people on JobSeeker, Youth Allowance and related working-age payments.

It found every available indicator showed the current rates of JobSeeker and related payments were seriously inadequate, whether measured against payments overseas, against the minimum wage, against pensions, or against poverty lines.

Measured against other members of the Organisation for Economic Co-operation and Development, Australia’s JobSeeker payment for a newly-unemployed single was the third worst.

When the higher rates of rent assistance available overseas were taken into account, it became the absolute worst.

Whereas a quarter of a century ago Australia’s unemployment payment was roughly in line with the pension, decades of lifting one in line with prices and the other in line with wages have left us with a base JobSeeker rate of $347 a week ($49.50 per day), compared to a base age pension of $485 a week ($69 per day).

Too little to get medicines or work

Job seekers told the committee that $347 per week is so low, they kept looking around their homes for things to sell. Some had to choose between medicines and electricity. Some could fill only some of their prescriptions. Others could barely afford the petrol to get to medical appointments.

The committee’s findings echoed those of the OECD, which found 12 years ago Australia’s unemployment payment had fallen so low compared to costs as to raise “issues about its effectiveness” in helping the unemployed find jobs.

The committee’s number one recommendation – more important than any other – was that the government

as a first priority, commit to a substantial increase in the base rates of the JobSeeker Payment and related working-age payments

It didn’t ask for JobSeeker and associated payments to be lifted to the pension rate straight away, although it did suggest that the ultimate goal should be 90% of the pension. Ben Phillips has calculated that would cost $5.7 billion per year, which is less than 1% of total government spending.

What the committee didn’t want was a tiny increase along the lines of the $25 a week ($3.60 per day) the Coalition delivered when the coronavirus payments ended in 2021, without a commitment to build to something substantial.

So what is the government now doing in response? Chalmers and Gallagher appear to have decided it’s best to talk about something else.

Changing the subject

Seven News has reported that, while it won’t touch the base rate of JobSeeker and associated payments, the Albanese government will increase the rate for Australians aged 55 and over who have been out of work for some time.

That’s even less of a commitment than it seems.

There are 920,640 Australians on JobSeeker and Youth Allowance (which is a lower rate of JobSeeker for young Australians and is also paid to apprentices and students). Only 236,280 of them are aged 55 and over.

Many of those 236,280 are aged 60 and over, and already get a boosted JobSeeker payment; an extra $26 per week ($3.70 per day) after they have been out of work for nine months.

If all Chalmers is planning is to extend the extra for the long-term unemployed aged 60 and over to the long-term unemployed aged 55 and over, it will cost little, and deny the vast bulk of those on $49.51 per day hope that things will improve.

Chalmers appeared to verbal his committee on Tuesday by saying it had found women over 55 are the most vulnerable group amongst unemployed Australians.

While the committee did say that (and while 56% of the Australians on JobSeeker in that age group are women), it could not have been clearer in recommending that the base rate of JobSeeker and associated payments be lifted for all Australians.

Chalmers says we ought to wait to see what is in the budget, which is fair enough. But if a commitment to do what his personally-selected expert committee has recommended isn’t in this budget, that committee is likely to recommend it again two weeks before the next budget, and again two weeks before the next.

The treasurer has put himself on notice.The Conversation

This article is republished from The Conversation under a Creative Commons license. Read the original article.

Read more >>

Tuesday, April 11, 2023

What made rents soar? It might have been COVID, and pairing off

So, you think you know why rents climbed.

You probably think was skyrocketing interest rates and a tsunami of migration.

It’s true that interest rates have jumped more over the past year than at any time on record, and it’s true that migration has roared back – in the six months to September 2022 (the latest month for which we’ve official figures) arrivals exceeded departures by 170,000.

But here’s the thing. Advertised rents began climbing sharply in late 2021 – six months before the Reserve Bank began pushing up interest rates, and at a time when it was forecast not to.

And “net migration” was negative back when rents were taking off – meaning the number of arrivals didn’t even match the number of departures.

It’s supply and demand

Something else made rents move.

As it happens, there’s no particular reason to think interest rates would have quickly affected rents even if they had been climbing. If higher rates force some landlords to sell, and they sell to other landlords, the number of properties for rent won’t change. If those landlords sell to owner occupiers who would otherwise rent, they cut both the number of rental properties and the number of renters.

What matters for rents, as for any price, is the demand for and the supply of the product being priced. More demand (more renters wanting properties) and the price climbs. More supply (more properties available for rent) and the price falls.

On the face of it, neither demand nor supply was changing much during COVID as rents started climbing. Australia’s population was growing more slowly than at any time in modern history. And, as best as we can tell, the number of properties available for rent was climbing, albeit weakly.

What did change during COVID, according to the research department of the Reserve Bank, was the average number of people per household.

The change doesn’t sound big – the average fell from a bit above 2.6 residents per household to a bit below 2.55 – but applied to millions of households it meant about 140,000 more houses and apartments were needed than would have been.


Average household size (capital cities)
Average number of persons usually resident in an occupied private dwelling, trend and actual. RBA, ABS

The sudden change was awfully for hard for the building industry to respond to, especially when it was laid low by COVID.

Why did we suddenly want to live with fewer people?

The head of the Bank’s economic division, Luci Ellis, thinks it was COVID itself, and lockdowns. We suddenly became more precious about sharing space.

‘Love the one you’re with’

Ellis says proportion of Australians living in group houses declined and stayed low. Faced with the choice of living with a large number of housemates and just one other person, perhaps a romantic partner, a lot of renters left group houses and shacked up with each other.

As she put it last year:

On the question of who you would rather be locked down with, at least some Australians have voted with their removalists’ van, by moving out of their share house and in with their partner.

There’s more to it of course, but where the supply and demand for anything are roughly in balance (rents had been increasing by less than 1% per year in the four years before COVID, and fell in the first year of COVID) any sudden change in either supply or demand can move prices quickly.

Advertised rents aren’t typical …

Having said that, for most renters prices are still moving slowly. Advertised capital city rents are up 13% over the past year, and advertised regional rates up 9%. But average rents (the average of what all renters pay) are up only 4.8%.

The rents charged to ongoing tenants climb much more slowly than the rents charged to new tenants, in part because landlords often like their tenants, and in part because for the first year renters are usually on fixed contracts.

But over time as renters move home, and landlords become less squeamish, more and more renters tend to pay the rents advertised. It makes the increase in advertised rents an unwelcome sign of what’s to come.

… but they’re a sign of rents ahead

And it might get worse. Reserve Bank Governor Philip Lowe says population growth is set to climb to 2% – near the peak reached during the resources boom.

We won’t be able to build houses anything like that fast. Lowe says the last time Australia’s population surged it took about five years for housing supply to fully respond to housing demand.

We’ve ways of dealing with it of course. One is to re-embrace group homes, another is to delay moving out of our partents’ homes, or to move back in.

But even if this does happen, Lowe says, with typical understatement, that rent inflation – ultra-low before COVID – is likely to stay “quite high” for some time.The Conversation

This article is republished from The Conversation under a Creative Commons license. Read the original article.

Read more >>

Tuesday, April 04, 2023

Sure, the RBA froze interest rates this time, but there’s plenty of pain to come

Australia’s Reserve Bank has hit pause on interest rates after ten successive hikes, but for many Australians, the pain it has inflicted is about to begin.

The Bank says more than one million households will come off ultra-low fixed-rate mortgages this year and the next, some of those rates fixed for as low as 1.95%. They will be pushed onto loans as high as 5%, meaning that if they borrowed $600,000, instead of paying $2,500 per month they’ll be paying $3,500.

That’s an extra $1,000 those borrowers will need to find each and every month – an extraordinary $250 they will need to find each week. The Bank says 880,000 fixed-rate mortgages will expire this year and another 450,000 next year.

How much harm will that do to the economy? Quite a lot. The Bank said the full effect of its interest rate increases to date was “yet to be felt”.

Fixed-rate borrowers face trouble

The Bank’s research finds fixed-rate borrowers are more likely to have larger loans relative to their incomes than other borrowers, and more likely to have high loan-to-valuation ratios, in part because they tend to be more recent borrowers.

Its rule of thumb is that borrowers who spend more than 30% of their income on scheduled payments run the risk of having problems paying. At the moment only one in ten fixed-rate borrowers is in such a situation. When those fixed loans expire and they switch to the higher variable rates, it will be one in four of them.

Which is a good reason for taking stock. The Bank may well increase interest rates again. It said it expected to on Tuesday. But it knows a lot of the damage from what it has already done is yet to come.

After its last meeting in March, the board produced a checklist of the things it said it would consider in April in deciding whether to hit pause. On this list were inflation, jobs, retail spending, business conditions and developments overseas.

Inflation easing

On inflation, the board says a range of information suggests the rate has peaked.

The official figures only come out four times a year, and the next ones aren’t due for some weeks. But since the last lot we have had two new readings of the quasi-experimental monthly index, and they have both been down.

On that monthly measure (which excludes 30% of the items in the quarterly measure, among them gas and electricity) inflation fell from 8.4% in the year to December to 7.4% in the year to January, to 6.8% in the year to February.


A further indication that price pressures are moderating is what trade unions asked for in the minimum wage case before the Fair Work Commission. They didn’t ask for the official inflation rate of 7.8%, but for 7%, which suggests they accept the monthly figures and believe inflation is coming down.

On employment (the second item on the Bank’s checklist), the official figures showed a jump in February after declines in December and January, but the Bank says this is more likely to reflect changing seasonal hiring patterns than a genuine surge. Job vacancies have been falling for six months.

Economy weakening

Retail spending (the third item on the checklist) grew just 0.2% in February, much less than price growth of 0.6%, at a time when Australia’s population grew quickly, suggesting what was bought per person went backwards. ANZ card data for the first two weeks of March shows a further weakening.

The Bank says the combination of higher interest rates, cost-of-living pressures and a decline in housing prices is leading to a “substantial slowing in spending”. While some households have savings buffers, others are experiencing a “painful squeeze on their finances”.

Business conditions (the fourth item of the checklist) remained healthy in February according to the National Australia Bank survey, although confidence slipped into negative territory (meaning pessimists outweighed optimists).

So weak was Australia’s overall economy on the last reading that gross domestic product (spending and income) grew just 0.5% in the three months to December, by about as much as population, meaning GDP per person didn’t grow.

The Bank says it expects “below trend” growth for the next couple of years.

Overseas headwinds

Overseas developments (the last item on the checklist) have been grim since the last board meeting.

The Bank says the international outlook is “subdued” with below-average growth likely in the years ahead, weighed down by bank crises in the US and Switzerland.

Lowe’s moment of truth

Governor Philip Lowe will address the National Press Club on Wednesday.

It’s likely to be his last chance to explain what he is doing before Treasurer Jim Chalmers releases the report of the independent review of the Bank he received in March.

That report is likely to suggest big changes to the organisation of the bank (such as more experts and fewer business figures on the board) and a more open culture.

But in something of a vindication for Lowe, it is set to find little reason to change either the Bank’s targets (2–3% inflation and full employment) or the single tool it uses to achieve them, which is adjusting the so-called cash rate.

After Chalmers makes changes as a result of the review, The Bank is likely to continue attempting to do what it is attempting to do now, which is using monthly (or perhaps less frequent) reviews of the cash rate to try to get inflation and employment somewhere near where it wants them. It won’t be easy.The Conversation

This article is republished from The Conversation under a Creative Commons license. Read the original article.

Read more >>

Wednesday, March 29, 2023

Inheritance taxes, resource taxes and an attack on negative gearing: how top economists would raise $20 billion per year

Asked to find an extra A$20 billion per year to fund government priorities like building nuclear submarines and responding to climate change, Australia’s top economists overwhelmingly back land tax, increased resource taxes, an attack on negative gearing and extending the scope of the goods and services tax.

The 59 leading economists surveyed by The Conversation and the Economic Society of Australia were asked to pick from a list of 13 options (many of them identified in the government’s 2022-23 Tax Expenditures and Insights Statement) and reply as if political constraints were not a problem.

The economists chosen are recognised as leaders in their fields, including economic modelling and public policy. Among them are former International Monetary Fund, Treasury and OECD officials, and a former member of the Reserve Bank board.

Asked to choose tax measures on the basis of efficiency – minimising the economic damage the extra taxes or tightening of tax concessions would do – 40% chose increased or new taxes on land, while 39% choose increased resource taxes.


International consultant Rana Roy said every major economist in every strand of modern economics had found taxes on the use of land and natural resources to be the least damaging way of raising money.

This was confirmed in Hong Kong, which charged for the use of crown land; in Norway, which heavily taxed oil and gas resources; and in countries such as Australia, which charge for the use of broadcast spectrum.

Former OECD official Adrian Blundell-Wignall said Australia’s natural resources were the birthright of every Australian. It was time for a resource rent tax along the lines of the one introduced by the Rudd and Gillard governments and abolished by the Abbott government in 2014.

Blundell-Wignall said politicians should ignore the usual hysteria that arose whenever the idea was discussed.

Centre for Independent Studies economist Peter Tulip said he would lump income from inheritances in with income from changes in land value. In both cases the income was unexpected, undeserved, and not compensation for sacrifice. And it disproportionately went to the already fortunate.

Negative gearing an ‘easy win’

A quarter of those surveyed backed winding back the ability to negatively gear (write off against tax) expenses incurred in owning investment properties, a concession costed by Tax Expenditures Statement at $24.4 billion per year.

Blundell-Wignall said negative gearing should have been wound back years ago. Few other countries allowed it, and it contributed to the build up of exposure to property in Australia’s banking system and financial risk as interest rates climbed.

University of Sydney economist James Morley described getting rid of negative gearing as an “easy win”. There were better ways to support home building.

Independent economist Saul Eslake said while he was inclined to extend capital gains tax to the sale of high-end family homes, the problem with the idea was that it might allow owners to write off against tax their mortgage payments (as is the case for investors who negatively gear), encouraging even larger mortgages.

One quarter of those surveyed wanted to broaden the scope of the goods and services tax (at present it excludes spending on education, health, childcare and fresh food) and one fifth wanted to increase the rate, pointing out that a 10%, it was low by international standards.

‘Unfair’ super concessions and tax-free inheritances

Asked to choose measures on the basis of equity – not treating similar people differently – 52% backed inheritance taxes, 37% backed winding back superannuation tax concessions and 32% backed increased resource taxes.

None would broaden the GST on equity grounds, and only 3.4% would increase its rate on equity grounds.


Grattan Institute chief executive Danielle Wood said two-thirds of the value of super tax breaks went to the top fifth of income earners, who are already saving enough for their retirement and would do so without tax concessions.

Wood said the government should go further than the measures taken against super accounts worth more than $3 million announced in February.

The University of Adelaide’s Sue Richardson said super concessions had a negative impact on budget revenue, amounting to tens of billions per year. They were used for tax minimisation by high earners who obtained expensive advice.

Missing fixes: Stage 3 and a carbon tax

Guyonne Kalb of the University of Melbourne said the most important tax measure for fairness was one not listed as an option: scrapping the legislated “Stage 3” tax cuts for high earners, due to take effect in 2024.

The tax cuts scheduled for people earning between $120,000 and $200,000 would not have much or any positive impact on Australia’s labour supply and would cost the budget more than $100 billion in their first seven years.

Three panellists, Frank Jotzo, Michael Keating and Stefanie Schurer, said they would have selected “carbon pricing to raise revenue” had it been an option.

Jotzo said if Australia fully taxed emissions at $100 per tonne, the revenue would be around $15 billion per year from electricity, $18 billion from industry, and $9 billion from transport – very large sums in relation to other options.

Schurer would also take away all subsidies to fossil fuel industries. In 2021-22 measures that wholly, primarily or partly assisted fossil fuel industries cost federal, state and territory governments $11.6 billion.

If the government needed $20 billion per year, it could raise around half from fossil fuel subsidies alone.


Individual responses:

The Conversation

This article is republished from The Conversation under a Creative Commons license. Read the original article.

Read more >>

Tuesday, March 21, 2023

How can Australia pay $368 billion for new submarines? Some of the money will be created from thin air

Australia’s decision to buy three nuclear-powered submarines and build another eight is so expensive that, for the A$268 billion to $368 billion price tag, we could give a million dollars to every resident of Geelong, or Hobart, or Wollongong.

Those are the sort of examples used by former NSW treasury secretary Percy Allan on the Pearls and Irritations blog, “in case you can’t get your head around a billion dollars”.

Such multi-billion megaprojects almost always go over budget.

For instance, when Prime Minister Malcolm Turnbull announced the Snowy Hydro 2.0 pumped hydroelectricity project in 2017, it was supposed to take four years and cost $2 billion. The latest guess is it’ll actually take 10 years and cost $10 billion.

So to pay for those two megaprojects alone, there’s an awful lot of money we will need to find from somewhere. Or will we?

‘No simple budget constraint’

In the first year of the pandemic, Australians were given a glimpse of a truth so unnerving that economists and politicians normally keep to themselves.

It’s that, for a country like Australia, there is “no simple budget constraint” – meaning no hard limit on what we can spend.

“No simple budget constraint” is the phrase used by Financial Times’ chief economics commentator Martin Wolf, but he doesn’t want it said loudly.

The problem is, he says, “it will prove impossible to manage an economy sensibly once politicians believe there is no budget constraint”.

A quick look at history shows he is correct about there being no simple budget constraint, despite all the talk about the need to pay for spending.

As you can see below, Australia’s Commonwealth government has been in deficit (spent more than it earned) in all but 17 of the past 50 years. The US government has been in deficit for all but four of the past 50.


Commonwealth government surpluses and deficits since 1901

Ashley Owen, Stanford Brown

There is no hard limit on how the Commonwealth can spend over and above what it earns, just as there’s no hard limit on how much you and I can spend. But whereas you or I have to eventually pay back what we have borrowed, governments face no such constraint.

Because the Commonwealth lives forever, it can keep borrowing forever, even borrowing to pay interest on borrowing. And unlike private corporations, it can borrow from itself – borrowing money it has itself created.

Governments create money

That’s what the Morrison government did in 2020 and 2021, in the early days of COVID.

To raise the money it needed for programs such as JobKeeper, the government sold bonds (which are promises to repay and pay interest) to traders, which its wholly-owned Reserve Bank then bought, using money it had created.

The government could have just as easily cut out the traders and borrowed directly from its wholly-owned Reserve Bank, using money the bank had created – effectively borrowing from itself. But the Reserve Bank preferred the appearance of arms-length transactions.

And there’s no doubt the Reserve Bank created the money it spent, out of thin air.

Asked in 2021 whether it was right to say he was printing money, Governor Philip Lowe said it was, although the money was “created”, rather than printed.

People think of it as printing money, because once upon a time if the central bank bought an asset, it might pay for that asset by giving you notes, you know, bank notes. I’d have to run my printing presses to do it. We don’t operate that way anymore.

These days the Reserve Bank creates money electronically. It credits the accounts of the banks that bank with it.

One way to think about it (the way so-called modern monetary theorists think about it) is that none of the money the government spends comes from tax.

The government creates money every time it gets the Reserve Bank to credit the account of a private bank (perhaps in order to pay a pension), and destroys money every time someone pays tax and the Reserve Bank debits the account.

If it creates more money than it destroys, it’s called a budget deficit. If it destroys more than it creates, it’s called a budget surplus.

Too much spending creates problems

Can the government create more money than it destroys without limit? No, but where it should stop is a matter for judgement.

If it spends too much money on things for which there is plenty of demand and a limited supply, it’ll push up prices, creating inflation.

Where to stop will depend on how much others are spending.

If there’s little demand (say for builders, as there was during the global financial crisis) the government can safely spend without much pushing up prices (as it did on builders during the global financial crisis).

If it wants to spend really big (say on building submarines), it might have to restrain the spending of others, which it can do by raising taxes.

What matters is what others are spending

But it’s not a mechanical relationship. The main function of tax is not to pay for government spending, but to keep other spenders out of the way.

If the economy is weak in the decades when the subs are being built, the burst of government spending will be welcome, and needed to create jobs. There will be no economic need to offset it by raising tax.

But if the economy is strong, so strong the government would have to bid up prices to get the subs built, it might have to push up tax to wind other spending back.

This truth means there’s no simple answer to the question “how they are going to pay for subs?” – just as there was no simple answer to questions about how to pay for a much-needed increase in the JobSeeker, or anything else.

The deeply unsatisfying answer is that, from an economic perspective, it depends on who else is spending what at the time.The Conversation

This article is republished from The Conversation under a Creative Commons license. Read the original article.

Read more >>

Tuesday, March 14, 2023

Working Australians pay tax in real-time – now the richest Australians making capital gains should too

In drawing up his plans to more effectively tax large superannuation accounts, Treasurer Jim Chalmers might have stumbled upon a really good idea.

If applied more broadly, it could at last tax rich Australians in something like the same way as the rest of us.

The wealthiest Australians are taxed differently from other Australians, because they earn much of their money in a different way.

Most of us get taxed at standard rates on the only income we have: income from working, and interest on savings in bank accounts.

High-wealth Australians make a lot of their money in other ways: from investments in shares and properties. And while the dividends from shares and the rental income from properties are taxed at standard rates, what happens to profits made by selling those shares and properties is anything but standard.

How capital gains are taxed differently

The profits made from buying and selling shares and properties are called “capital gains”. Until 1985, most of them were untaxed.

Sure, a section of the Tax Act said if you made a profit selling an asset after less than a year you would pay tax – but you could avoid that by waiting for more than a year. It also said if you sold something for the purpose of making a profit you could be taxed, but you could avoid that by saying profit wasn’t your purpose.

The capital gains tax, introduced in 1985, changed that.

Income from the profits made from buying and selling shares and properties was taxed as income – but with two important exceptions.

Rewriting one exception to the rules

One of those exceptions was that less of the income would be taxed than for other types of income. At the moment only half of each capital gain is taxed.

(During its unsuccessful 2016 and 2019 election campaigns, Labor promised to halve the discount, meaning 75% of each gain would be taxed.)

The other exception – the one Chalmers is breaking ground by winding back when it is used by super funds – is that the tax is only due when the asset is sold.

This is quite different to the way tax is charged on interest earned in bank accounts. We pay as the interest accumulates, not years or even decades later when the money is withdrawn.

The 2010 Henry Tax Review saw this special treatment as a problem.

A better deal than most Australians get

The Henry Review said collecting tax only on “realisation” (when assets were sold) rather than “accrual” (as they grew in value) encouraged investors to hold on to shares and property to delay paying tax – a response it called “lock-in”.

All the better for the investors if, when they eventually sold, they had retired and were on a much lower tax rate, meaning they would scarcely pay any tax on decades worth of gains.

During financial crises when prices fell, the rules encouraged investors to do the reverse – to sell quickly to realise tax losses, destabilising markets.

Henry would have preferred tax to be collected as the gains accrued, but said back then that wasn’t practical.

While improvements in technology might improve things, in 2010 it was hard to get a good read on changes in the value of buildings or rental properties until they were sold.

Real-time collection has become easier

Not now. Firms such as CoreLogic revalue property daily, and not just in the general sense. If you want to know what has happened to the value of a three-bedroom home with two bathrooms, on a particular size block of land, in a particular street, CoreLogic can tell you.

And real-time values are being used for all sorts of purposes. Pensioners owning rental properties get their value updated annually for the pension assets test. Services Australia doesn’t wait until they are sold to declare they are worth more.

It is the same with council rates. Property values are updated annually, rather than down the track when they change hands. There’s no longer a practical impediment to doing this, and there’s never been a practical impediment to valuing shares. They are valued daily on the stock exchange.

Finally taxing super funds in real time

That’s the simple approach Chalmers has now taken to valuing super fund income for the purpose of imposing the 15% surcharge on high balances, as announced a fortnight ago.

Rather than taxing capital gains only when assets are sold (as will still happen for the bulk of what’s in super accounts), the surcharge will be calculated by applying a 15% tax rate to the increase in the value of the relevant part of each fund. Super funds are already valued quarterly.

Chalmers isn’t talking about doing it more broadly. But what he is doing shows it would be fairly easy.

An option for Australia

Denmark is planning to do it this year, becoming the first country in the world to introduce what it calls the “mark to market” taxation of real estate capital gains.

Adopting the same approach in Australia would create difficulties that would have to be worked through, perhaps by providing loans. Some property owners wouldn’t have enough ready cash to pay an annual capital gains tax, just as some don’t have enough ready cash to pay rates.

But mark to market taxation of real estate capital gains would have benefits.

It would make investment properties less attractive, putting downward pressure on prices and making it easier for homeowners to buy. And it would make the tax system fairer by preventing wealthy Australians from postponing tax until their tax rate was low, raising much-needed money.

Following Denmark’s lead is not going to happen in a hurry – if at all. But by moving in that direction, Chalmers has brought fairer taxation of capital gains for all Australians a little closer than before.The Conversation

This article is republished from The Conversation under a Creative Commons license. Read the original article.

Read more >>

Tuesday, March 07, 2023

Why RBA interest rate hikes could end by September – but brace for at least one more

Tuesday’s tenth successive Reserve Bank interest rate hike is the culmination of a process that has added $1,080 to the monthly cost of payments on a $600,000 variable mortgage.

I’ve calculated this increase in payments – which amounts to $12,960 per year – by comparing payments on the National Australia Bank’s base variable mortgage rate before the Reserve Bank started its series of hikes in May 2022 with payments after the NAB lifts its rates in accordance with Tuesday’s decision.

Before the Reserve Bank started hiking in May 2022, the NAB rate was 2.19%. After nine Reserve Bank hikes, ahead of Tuesday’s meeting, it was 5.24%.

It will soon be 5.49%, meaning the monthly payment on a 25-year $600,000 NAB base variable mortgage will have climbed from $2,600 to $3,680.

And Tuesday’s statement from the Reserve Bank indicates there’s more to come.

But an end to these rate rises is within sight – possibly as soon as mid-September.

Bank on at least 1 more rate rise

The best guide to what the Reserve Bank has in mind is usually the first few words of the final paragraph of its statement.

Last time, in February, those words referred to further interest rate “increases”, making it clear the bank expected more than one.

This time, there’s no plural. The sentence refers merely to “further tightening”, which could mean as little as one more increase, and not necessarily next month.

The statement, like the last, says rate hikes work “with a lag, and that the full effect of the cumulative increase in interest rates is yet to be felt in mortgage payments”. That’s a reference to the large number of borrowers who are about to be hit with higher payments as they come off low fixed rates.

And, unlike the last statement, this one says inflation may have peaked.

So there are reasons for easing off, but also – as I’ll explain shortly – important institutional forces propelling Governor Philip Lowe to keep going.

Reasons for easing off on further rate hikes

The whole point of the dramatic interest rate hikes has been to make sure Australia’s sudden reemergence of high inflation is only temporary.

Inflation hit 7.8% in December, well outside the Reserve Bank’s 2-3% target zone and the most since 1990.


The good news is to the extent that inflation comes from overseas in the prices for fuel and other imports, it seems to be easing.

US inflation has been falling for seven months now, from a high of 9.1% in June to 6.4% in January. UK inflation has been falling for three months, from 10.1% to 9.1%.

To the extent that inflation is driven by a surge in spending at home, that surge has stopped. Retail spending has been flat (unchanged) for four months notwithstanding a growing population and growing prices.

We’re winding back spending

This means what’s bought per person is falling, as would be expected if we were tightening our belts in response to higher interest rates and higher prices.

In February consumer confidence, as measured by Westpac and the Melbourne Institute, dived to its lowest point since the 2020 COVID recession.

Asked whether now was a good time to buy a major household item, only 17% of Australians surveyed said yes. Twice as many – 39% – said no.

Last week’s national accounts showed gross domestic product, the official measure of everything earned, bought and sold in the economy, climbing only 0.5% in the three months to December.

But buried in the fine print was something worse. Were it not for a fall in imports in the December quarter, GDP would have gone backwards.

It is one of the truly bizarre mathematical oddities of the way the GDP is calculated that a fall in imports boosts measured GDP, even though it is a sign we are tightening our belts.

And we’ve been having to tighten our belts. Wage figures released since February’s board meeting show growth of just 3.3% in the year to December, way below the increase in prices, and way below the entrenched growth of 5% the governor has said would concern him.

One of the reasons wages aren’t yet climbing particularly fast is that (unusually) wage earners expect inflation to fall. Throughout most of its life, the Melbourne Institute survey of inflation expectations has pointed to higher inflation than was actually experienced. At the moment it is pointing to lower inflation.

Nevertheless, the RBA board “remains alert to the risk of a prices-wages spiral” according to Tuesday’s statement. This implies it isn’t yet reassured by the official figures and that its liaison program with 600 or so business operators has identified increases yet to come.

6 months left to leave a legacy

That’s the economics, which points to taking things gently on rate rises from here on. But as I mentioned, there’s something else at play that might propel Governor Lowe to keep going a little further.

Governor Lowe’s five-year term expires on September 17. As his predecessor did, he would like to hand over the bank in good order.

That means having clearly broken the back of runaway inflation. It might mean going harder for longer on interest rate rises than he otherwise would to get things in order. It’s what his predecessor did for him in August 2016.

Glenn Stevens cut interest rates one last time before he left office to make sure Lowe didn’t take over the bank having to do it himself. Lowe left rates unchanged for almost three years. He had been handed the keys to a car in working order.

Seen this way, Lowe’s determination to be sure inflation is on the way down before leaving office is a matter of etiquette. He has six months left to get his house in order.

It’s a consideration that might mean more mortgage rate pain than would have been the case had Lowe not been near the end of his term.The Conversation

This article is republished from The Conversation under a Creative Commons license. Read the original article.

Read more >>

Tuesday, February 28, 2023

Tax-free super for the super rich is a bad deal for the rest of us – and Morrison said it first

You’d be forgiven for thinking Treasurer Jim Chalmers had done something dramatic.

From 2025 he will double the tax rate on earnings from superannuation balances above A$3 million, lifting it from 15% to 30%.

Only 80,000 Australians have accounts that large, and many of them who have retired have shoved the maximum permissible $1.7 million into a separate so-called retirement account whose earnings are entirely tax-free.

That’s right. Retirees with $1.7 million in retirement accounts pay nothing whatsoever on what those accounts earn, which in normal years amounts to $85,000.

By way of comparison, wage earners on $85,000 get taxed $18,000.

But though you’d never know it from some of the “socialist tax grab” commentary around this week, Chalmers isn’t the first treasurer to act on this rort. Scott Morrison got there first.

Howard’s super deal for the richest 1%

In 2006, in what economist Saul Eslake describes as one of the worst taxation decisions in modern times (an honour for which he says there’s a fair bit of competition), then Prime Minister John Howard exempted from tax withdrawals from super for Australians aged 60 and over.

By itself, this was unremarkable. We don’t tax withdrawals from bank accounts, because the interest they earn has been taxed within the account.

But Howard left in place a preexisting exemption from tax for earnings within the retirement accounts of Australians aged 60 and over.

This meant the earnings on the sometimes very large accounts of retirees aged 65 and over weren’t taxed at all. Not at the normal super tax rate of 15%, not at any rate – without limit, no matter how much was earned, merely because the person owning the account was aged 65 or over and had retired.

Morrison wound Howard’s policy back

In office, the Labor governments of Kevin Rudd and Julia Gillard didn’t touch the open-ended opportunity to earn unlimited amounts from super tax-free. Instead, we had to wait a decade, until Prime Minister Malcolm Turnbull and his Treasurer Scott Morrison wound it back in 2016.

Facing off against critics in his own party, Morrison cut the amount that could be transferred from an ordinary super account into a tax-free “retirement” super account to $1.6 million, a ceiling that is adjusted every few years with inflation.

“If you’ve got more than $1.6 million in a superannuation account, you’re in the top 1% and you’ve worked hard to get there, that’s fabulous,” Morrison said at the time. “But that $1.6 million is the limit.”

The seeds of Chalmers’ new plan

They were words echoed by Chalmers on Tuesday, who said his change would only affect half of the top 1%. If people had done well, that was “a good thing”.

But Chalmers said the system should be fairer.

And I think for any objective observer, the idea that ordinary working people subsidise incredibly generous tax breaks for people with millions and millions of dollars in superannuation doesn’t stack up.

Chalmers did more than channel Morrison’s language. The idea of a 30% super tax rate isn’t new.

Most Australians pay 15% on contributions, but in 2016 then treasurer Morrison expanded a 30% contributions rate from Australians with combined incomes and super contributions exceeding $300,000 to Australians with incomes and contributions exceeding $250,000.

And Chalmers received encouragement from another source.

In last year’s pre-budget submission, the Association of Superannuation Funds (ASFA) pointed the new treasurer to 11,000 super accounts holding more than $5 million, some of them holding hundreds of millions, “well in excess of retirement needs”.

The peak body for super funds called on the then Morrison government to end super tax concessions when accounts grew to $5 million, an amount it said could not “reasonably be justified as necessary to support a comfortable lifestyle in retirement”.

On Tuesday Chalmers picked up the idea – an idea that came from the super industry itself – but made the limit $3 million, instead of $5 million.

As ASFA proposed, that ceiling won’t climb over time with inflation, meaning over time more and more Australians will be taxed at 30%.

You don’t need millions for a comfortable retirement

There are two points worth noting. One is that the quoted tax rate of 30% won’t work out at 30%. The best guess within the industry is that few pay anything like 15%. They are able to use concessions on capital gains and dividend imputation to drive down the tax actually paid to something nearer 7%.

The other is most Australians don’t need anything like what $3 million would buy in retirement – or even the $1.7 million they are allowed to use tax-free.

The ASFA retirement income standard has a “comfortable” retirement costing $48,266 per year (or $68,014 for a couple).

ASFA defines comfortable to mean $90 per month on broadband, $80 in alcohol, $46 in Netflix-like services, $258 dining out, top-flight private health insurance, and one domestic flight per year and an international flight every seven years.

It’s a level of largess not bestowed on many of us while working. If it was felt necessary in retirement (and doubtless many wealthy retirees do feel it is necessary) there’s no reason to expect them to get it all from super.

The government’s 2020 retirement income review found high-income Australians earned as much again from investment income outside super as they made from withdrawals from it. They do alright.

Scott Morrison, much criticised for the generosity to high income earners of his Stage 3 tax cuts, moved in the right direction on super. Jim Chalmers is picking up where he left off.The Conversation

This article is republished from The Conversation under a Creative Commons license. Read the original article.

Read more >>

Tuesday, February 21, 2023

See when Australia’s biggest banks stopped paying proper interest on your savings – and what you can do about it

Whenever interest rates went up in the past, I used to get told it wasn’t all bad news. At least it was good for some people: savers – people with money in the bank.

I hear a lot less of that these days.

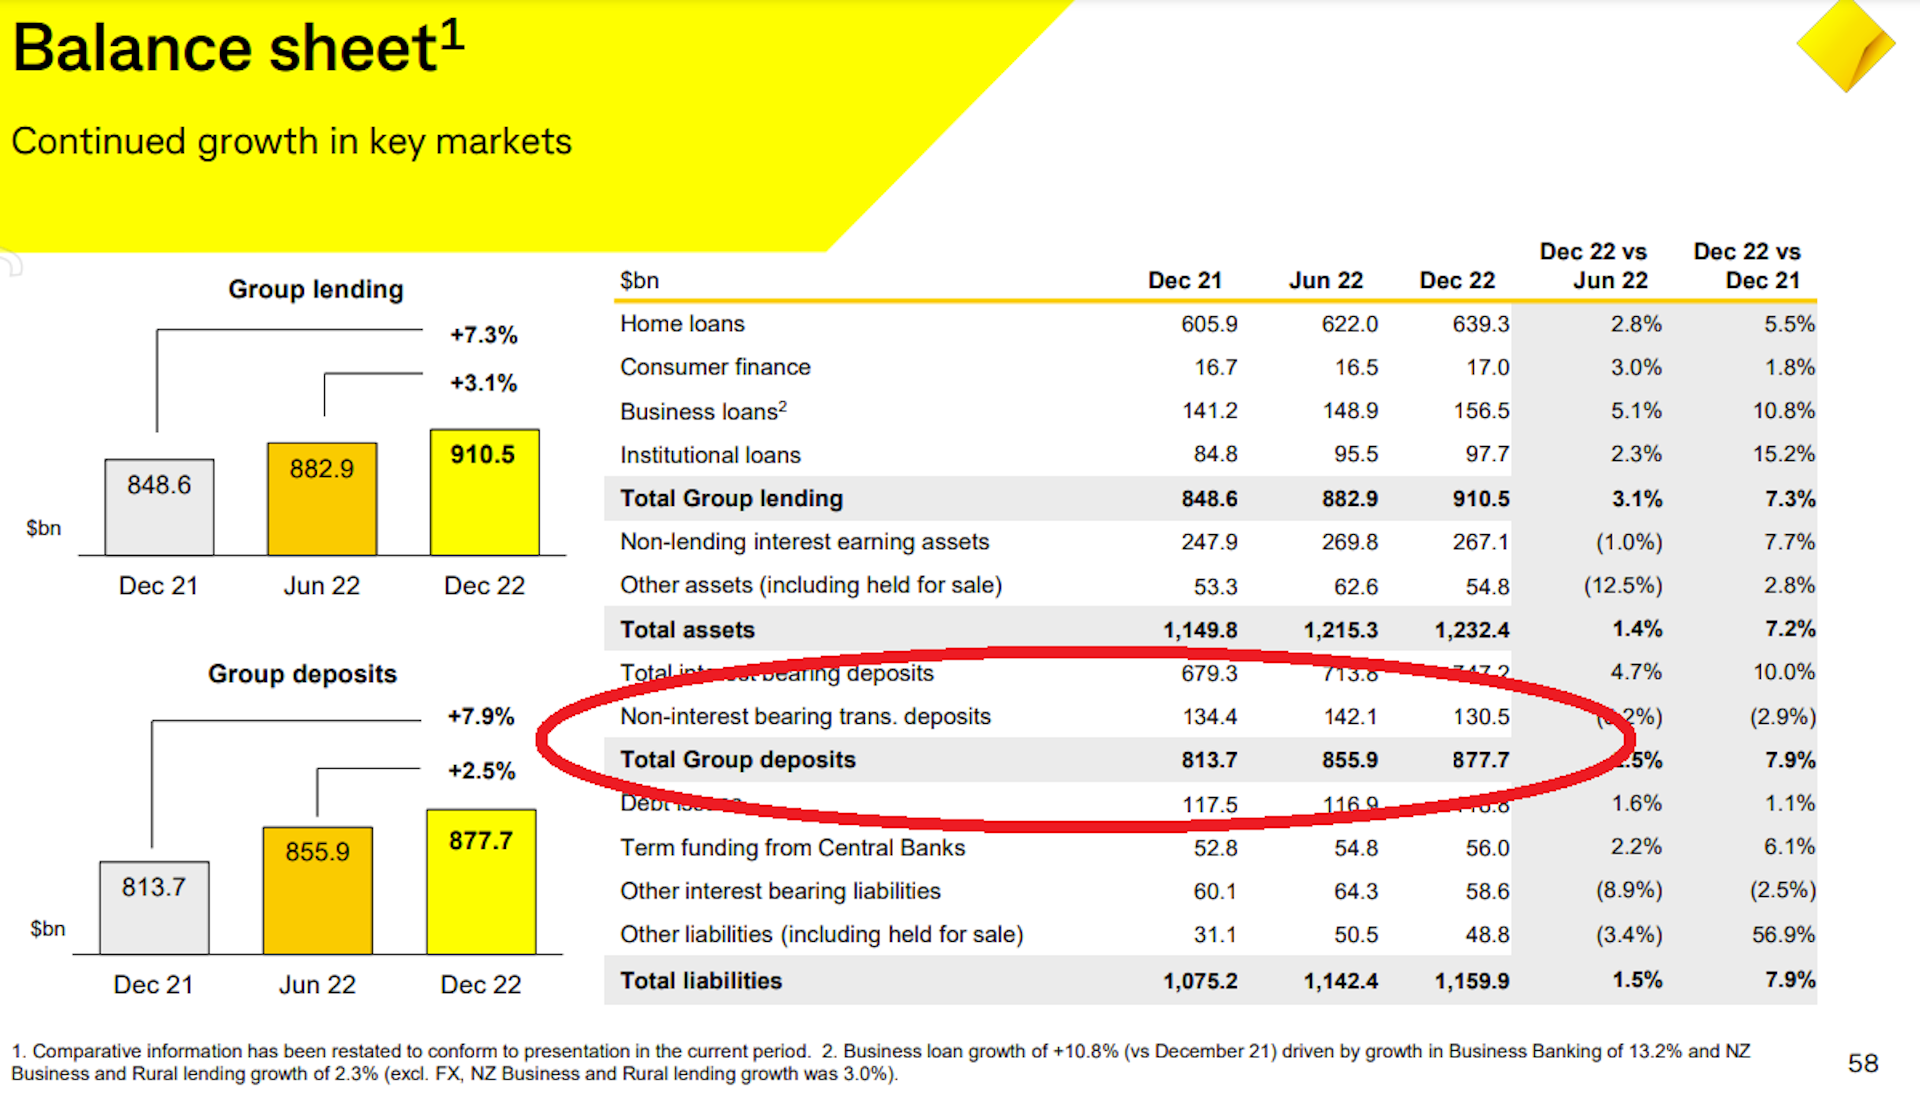
If you’ve got money in the bank, you’re now lucky to earn anything at all. One in seven of the deposit dollars held by the Commonwealth bank (Australia’s biggest for deposits) is in a “transaction account” on which it no longer pays interest.

Where interest is paid, it is so tiny compared to what it was that Treasurer Jim Chalmers this month directed the Australian Competition and Consumer Commission to conduct an inquiry, using its compulsory information-gathering powers.

The last time the commission conducted such an inquiry, into mortgage rates in 2018, it gained access to nearly 40,000 documents from the big four banks and more than 7,000 from the smaller banks.

Bad news for savers: when your rates began to fall

What the commission is likely to find is that whereas transaction accounts stopped paying interest some time ago, so-called online accounts offering interest on large deposits were paying very reasonable interest – up until five years ago.

How do I know that’s the likely finding? Here’s what I found, when I graphed the Reserve Bank’s measure of the average online rate for a $10,000 deposit against the Reserve Bank’s cash rate, going back to 2010.


What the graph shows is that, until about five years ago, the online rate for big deposits moved in line with the cash rate and (as it happened) almost exactly matched it. When the cash rate was 3%, the online deposit rate was 3%, and so on.

But from 2018, the deposit rate fell away. Except for the time when both rates were close to zero during the early years of COVID, the rate paid on large deposits has stayed well below the cash rate ever since.

That’s what the official figures say. But Anna Bligh, chief executive of the Australian Banking Association, sees them differently.

“This time last year, the four major banks, nobody, no bank was offering more than 0.3% on their savings account,” she told the Australian Financial Review this month. “Right now, they’re all offering at least 4% or more. So that’s a massive increase.”

But the rates Bligh quotes aren’t the standard ones.

The Commonwealth Bank is indeed paying 4% on its so-called NetBank Saver account, but the 4% is an introductory rate for new customers only – before slipping back to 1.6% after five months.

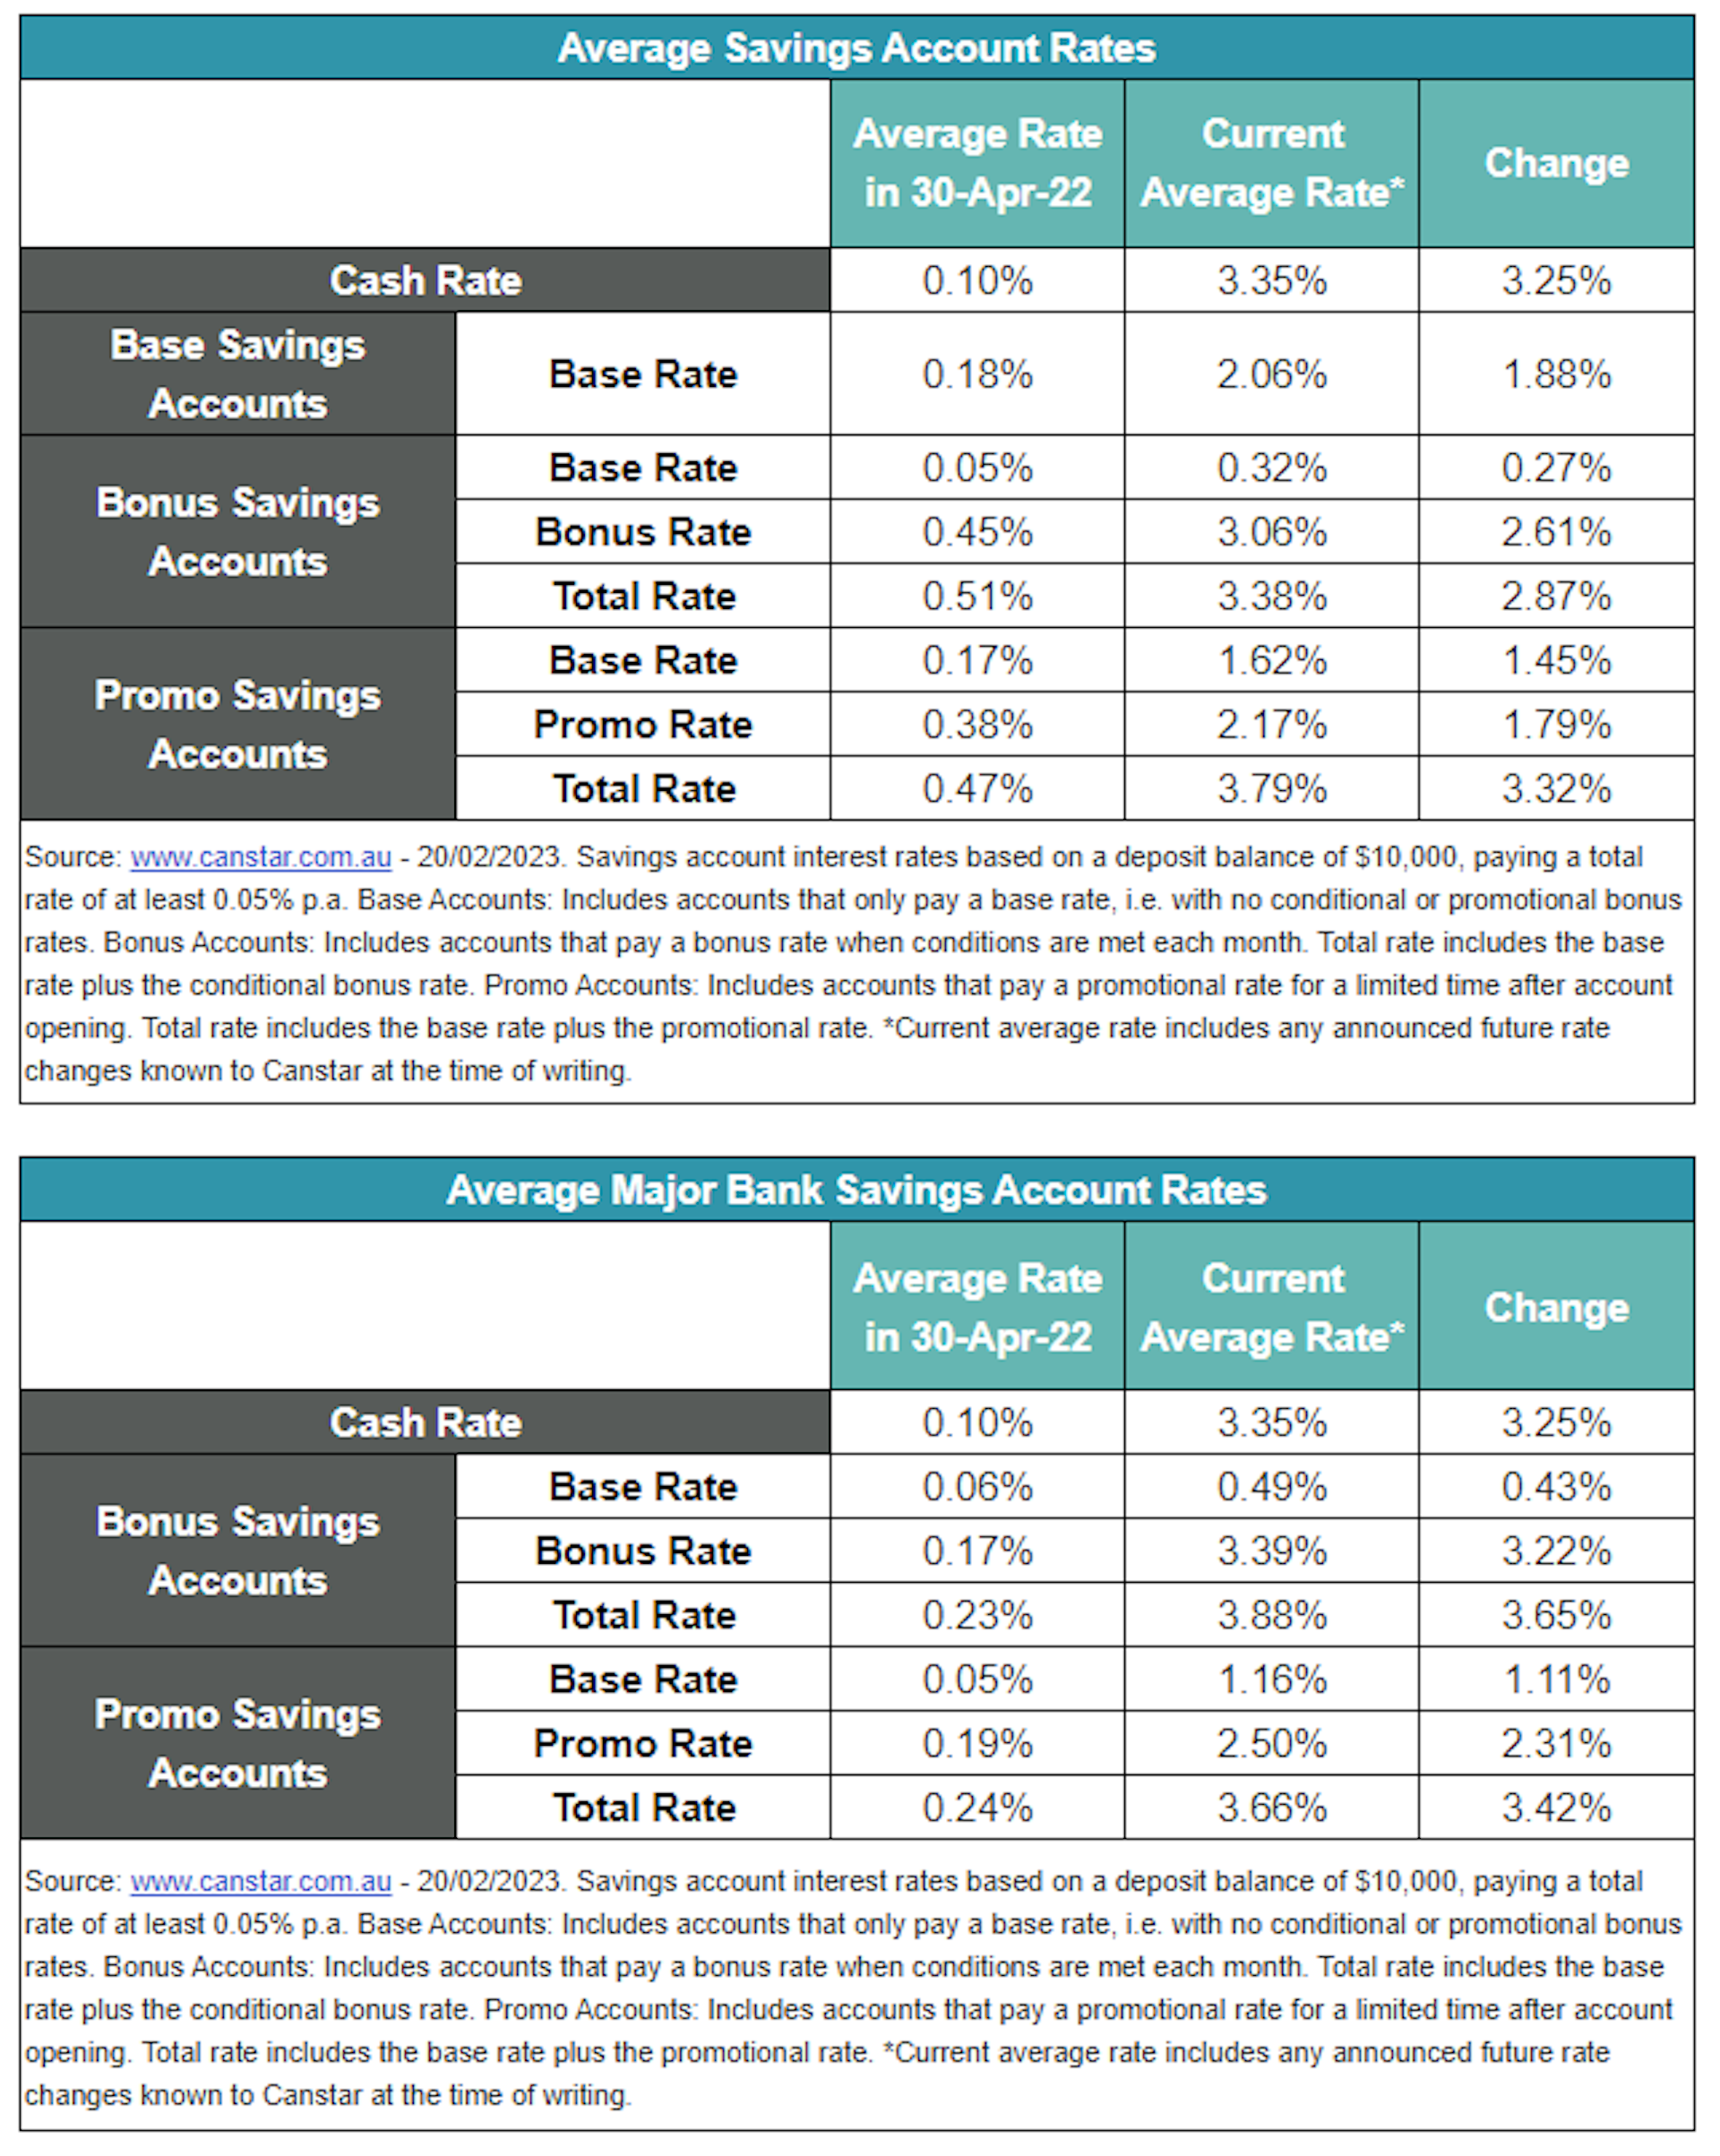
The web comparison site Canstar finds the average big bank introductory rate on $10,000 is 3.66%, up from 0.24% before the Reserve Bank put up the cash rate by a total of 3.25 points.

But the average rate offered when the introductory bonus wears off has climbed by much less, from 0.05% to just 1.16%.

Complexity and suspected collusion makes switching hard

And some of the high-looking rates have special conditions.

The Commonwealth’s GoalSaver account also offers 4%, but only if you put in more money in each month. If you can’t, or if you make a withdrawal, the rate plummets to 0.25%.

The Australian Competition and Consumer Commission’s inquiry is likely to find that the complex nature of the deals makes switching hard, just as does the complex nature of electricity and health insurance deals.

That’s what it found about the bank’s mortgage offerings in 2018.

It found the “opaque” nature of the offers inflated the costs of shopping around (including time and effort) and was one of the reasons why 70% of borrowers surveyed by one of the big banks said they signed up after getting just one quote.

It said the big four banks profited from the suppression of incentives to shop around and lacked strong incentives to make prices more transparent.

So why have the deposit rates offered by the big four banks dropped away?

When it came to mortgages, the ACCC suspected tacit collusion. Its 2018 report referred to a “synchronised” approach to rates seven times.

Why the banks won’t act – unless we make them

In very recent years, the banks have had less reason to offer high rates. During the first 15 months of COVID, the Reserve Bank made available A$188 billion of funding to banks at the extraordinarily low rates of 0.25% and 0.1%.

This meant banks had less need to attract deposits, and in any event, they were overwhelmed with deposits. Elevated savings rates during COVID pushed an extra $300 billion through their doors, as worried and locked-down households sought out safe places to stash cash.

Both of these things are changing. The last of the Reserve Bank’s cheap three-year loans to banks expires mid-next year, and households are stashing less into banks than they used to.

It is possible deposit rates might be about to improve, all the more so because the banks will be under scrutiny until the ACCC inquiry reports at the end of the year.

When announcing the inquiry, the treasurer invoked fairness. Chalmers called on the banks to “pass on the interest rate rises to savers as quickly as you pass on the interest rate rises to mortgage holders”.

But fairness has little to do with it. The banks will pay depositors more only when they need to, or when they are pressured to. Until then, for many of us, deposits will earn next to nothing, regardless of where the Reserve Bank moves rates.

So if you’ve got a savings account, why not call up your bank, quote this article – and ask them what they’re going to do about it.The Conversation

This article is republished from The Conversation under a Creative Commons license. Read the original article.

Read more >>