Monday, August 31, 2020

Australia's top economists oppose the next increases in compulsory super: new poll

The five consecutive hikes in compulsory super contributions due to start next July should be deferred or abandoned in the view of the overwhelming majority of the leading Australian economists surveyed by the Economic Society of Australia and The Conversation.

Two thirds – 29 of the 44 surveyed – want the increases deferred or abandoned. Only 13 think they should proceed as planned.

An even larger majority, including some economists who want the increases to proceed, believe they will hit wage growth. Several are concerned they will hit employment.

Compulsory superannuation contributions are paid by employers.

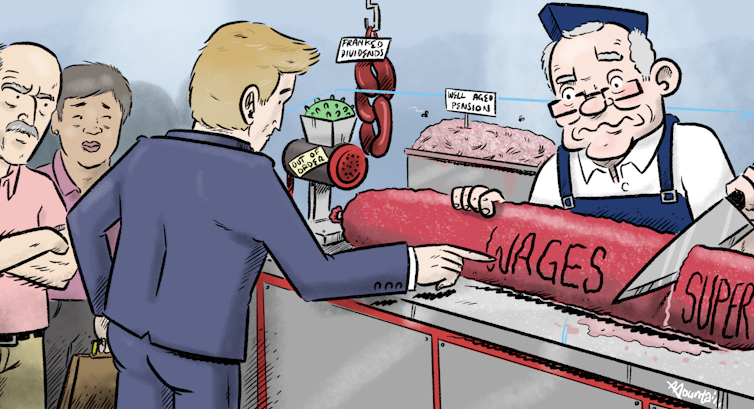
But ahead of the most recent increase in compulsory super, from 9% of salaries to 9.5% in 2013 and 2014, the then Labor superannuation minister Bill Shorten said the increase would cost employers nothing because it would be taken from wage rises.

“A portion of what would have been employees’ increases will go into compulsory savings,” he said.

That conventional wisdom has since been challenged in work funded by the superannuation industry and has been examined extensively in the retirement income review at present with the government.

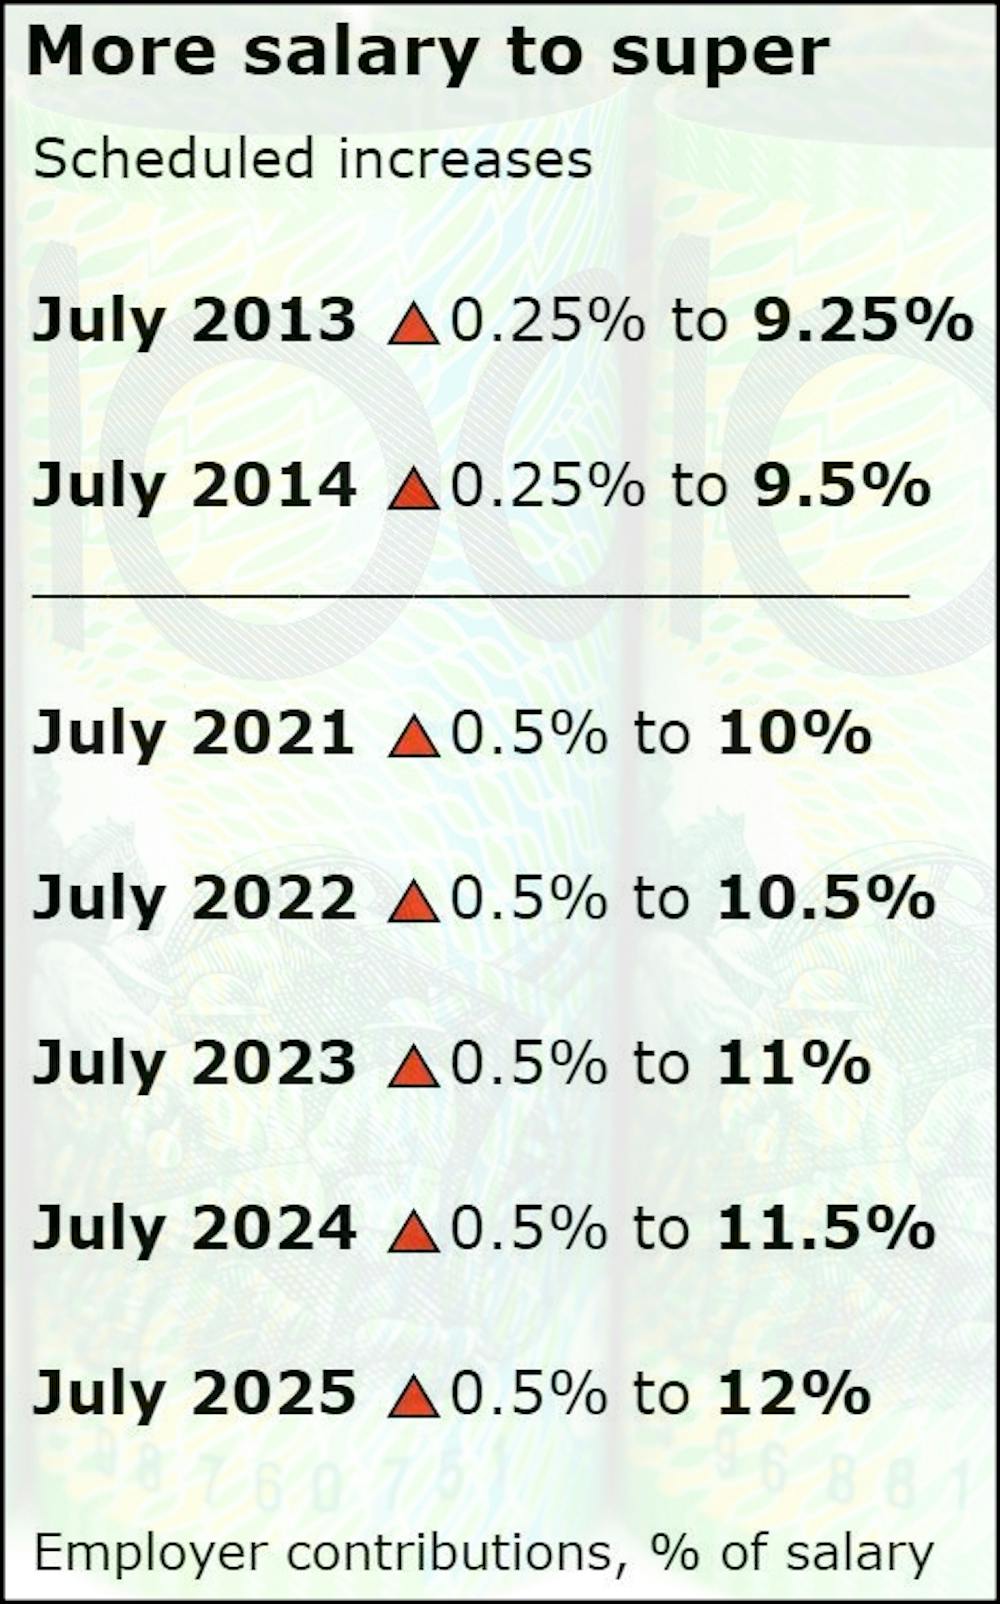
The two most recent increases in compulsory superannuation in 2013 and 2014 were small by design – 0.25% of salary each.

The next five increases, originally due to due to begin in 2015 but postponed to start in July 2021, are much bigger – 0.5% of salary each – at a time when wage growth is much smaller.

In 2012 Shorten was expecting wage increases of 3-4% and “assuming that a quarter of a per cent of that 3% to 4% may well go into your compulsory savings”.

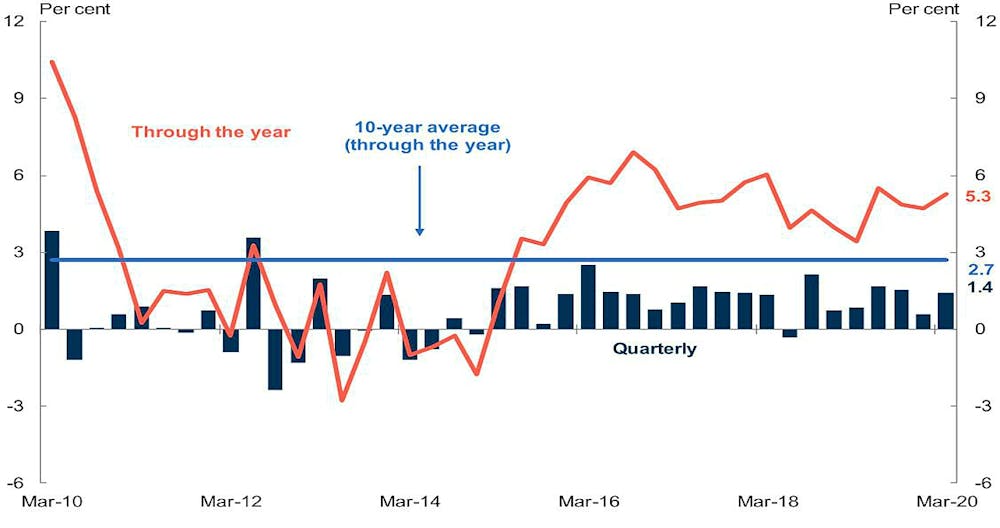
Wage growth has since slipped to 1.8%, the lowest on record. If the best part of 0.5% is taken out of that each year for the next five years it is unlikely to climb.


Wage growth has slipped to 1.8%

Wage Price Index annual growth, public and private, all industries, seasonally adjusted. ABS 6345.0

The 44 members of the Economic Society’s 57-member panel who responded include Australia’s preeminent experts in the fields of microeconomics, macroeconomics economic modelling, labour markets and public policy.

Among them are former and current government advisers and a former head of the Australian Fair Pay Commission and member of the Reserve Bank board and a former member of the Fair Work Commission’s minimum wage panel.


Read more: 5 questions about superannuation the government's new inquiry will need to ask


Each was asked whether the legislated increases in compulsory super contributions should proceed as planned, be deferred or be abandoned.

Only 13 of the 44 thought the increases should proceed as planned. 29 thought they should be deferred or abandoned, nine of them preferring they be abandoned altogether.
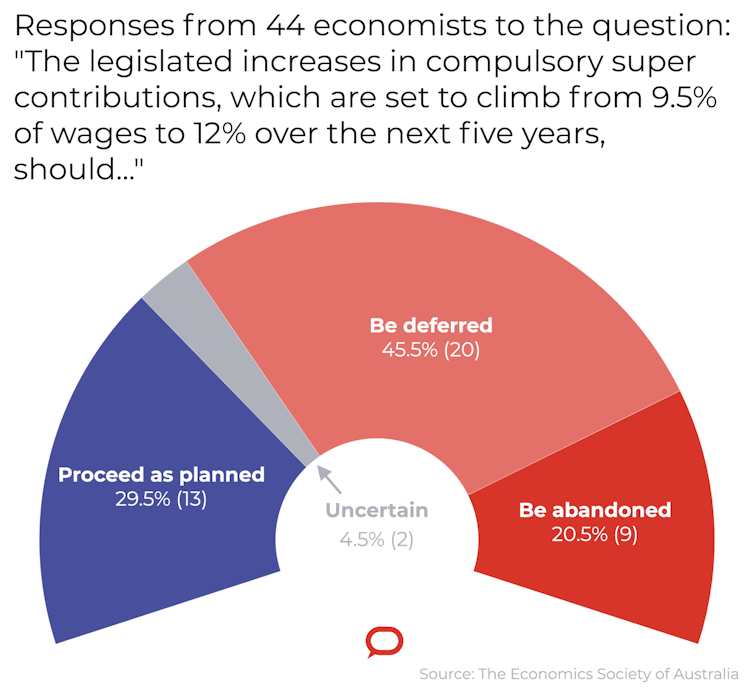

Charts showing that of 44 economists asked

Those who thought they should be deferred argued that now is “not a time to encourage saving”. In the current circumstances we should be “far more worried about spending power today than in the golden years of present-day workers”.

Economist Saul Eslake said he had changed his mind. The latest evidence (which will be updated in the retirement income review) suggests that the current 9.5% so-called super guarantee will be enough to provide most people with an adequate income in retirement .

“In saying that I acknowledge that there is still a significant problem with regard to the adequacy of superannuation savings for women relative to men, but I don’t see how raising the super rate for everyone to 12% solves that problem,” he said.

“Not a time to encourage saving”

Economic modeller Janine Dixon said it was not clear that the optimal contribution was 12% rather than 9.5%. The increase would force some households into greater debt. While this would pose a risk to economic stability at any time, Australia could “not afford to let the household sector weaken further at present”.

Economist Geoffrey Kingston said anyone who felt 9.5% was not enough remained “free to make voluntary contributions”.

Among those believing the increases should proceed as planned were two former politicians, Labor’s Craig Emerson and former Liberal leader John Hewson.

Emerson said 9.5% was “considered inadequate by the burgeoning retiree population”. Without an increase, that population “would successfully demand increased pension levels from the Commonwealth”.

Opponents more confident

Hewson said compulsory super had become a fundamental part of an effective retirement incomes strategy and, COVID and economic collapse notwithstanding, we should “finish the job”.

Sue Richardson, a former member of the Fair Work Commission’s wage panel, believed any deferral might lead to another deferral and be “hard to recoup”.

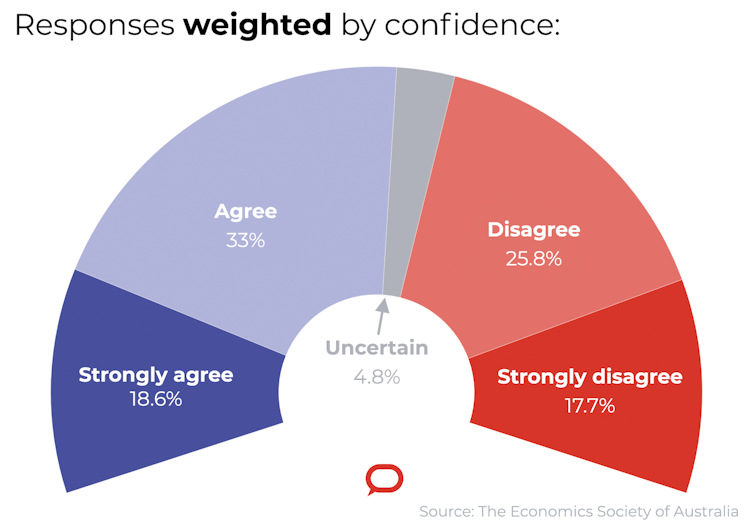
The economists were asked to rate their confidence in their responses on a scale of 1 to 10.

Unweighted for confidence, 20.5% of those surveyed wanted to abandon the increases altogether. When weighted for confidence, that proportion climbed to 21.6%. The proportion that wanted the increases either deferred or abandoned climbed to 67.1%
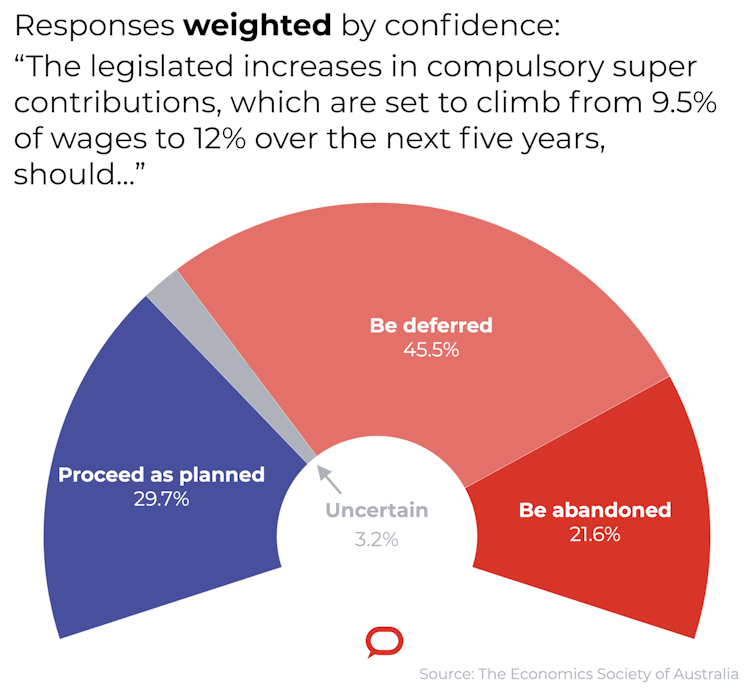

Weighted responses to the question,

Asked whether the increases were likely to be largely paid for via slower wage growth than otherwise, 30 of the 44 economists agreed. Only eight disagreed.

Economist Nigel Stapledon said this “should not be controversial”.

Private sector economist Michael Knox said: “unless one lives in an unreal world, increases in superannuation guarantees are funded by employers out of the total wage the worker might otherwise receive”.

Super and wages come from the same pool

Several enterprise bargains explicitly make a trade-off between wages and superannuation, providing for wage increases that will be 0.5 points higher should compulsory super contributions not climb by 0.5 points.

Economist Alison Booth said if employers weren’t able to trim wage rises to pay for the scheduled increases in super contributions, they might “attempt to adjust on other margins”.

In a recession, when workers lack bargaining strength, “employers could coerce them to accept other adjustments to their contracts”.
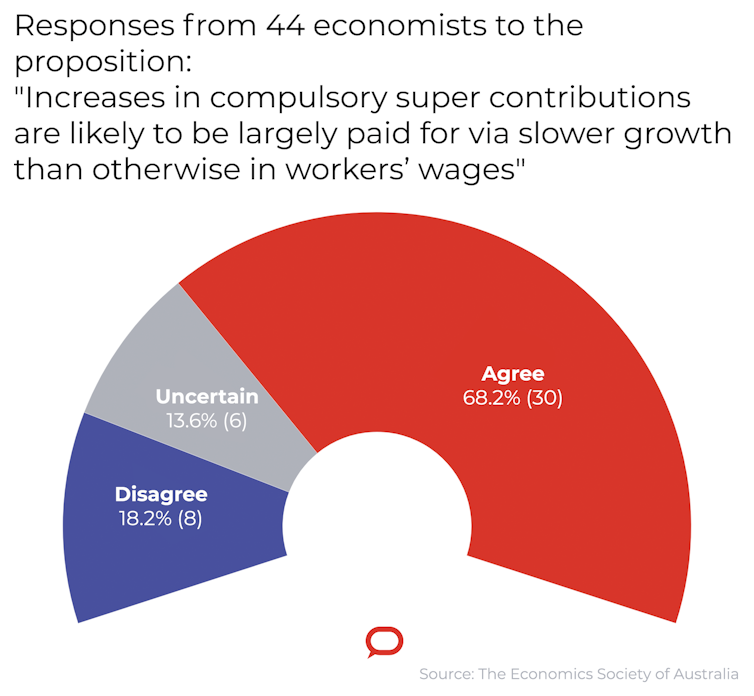

Responses from 44 economists to the proposition:

Two of the eight economists who disagreed with the proposition that the increases in compulsory super would come at the expense of wages thought that employers wouldn’t grant wage rises anyway. Increases in super contributions might be one way for employees to get something.

A concern among both those who agreed and disagreed was that if the increase didn’t come at the expense of wages, it would push up the cost of hiring and come at the expense of jobs.

“Inflation is very likely to be very, very low and wages to be sticky,” said government advisor Matthew Butlin.

A drag on jobs if not wages

“Higher superannuation payments in an environment where wages are unlikely to rise and cannot fall will raise real labour costs and reduce the incentive to employ.”

Economic modeller Janine Dixon said that while over time the increase in contributions would probably come from wages, the immediate impact would be to increase the cost of hiring, “which is an unacceptably large risk in the present climate”.

When adjusted for confidence, the proportion of those surveyed expecting the increases to largely paid for via slower wage growth climbed from 68.2% to 71%. The proportion disagreeing fell from 18.2% to 17.8%.
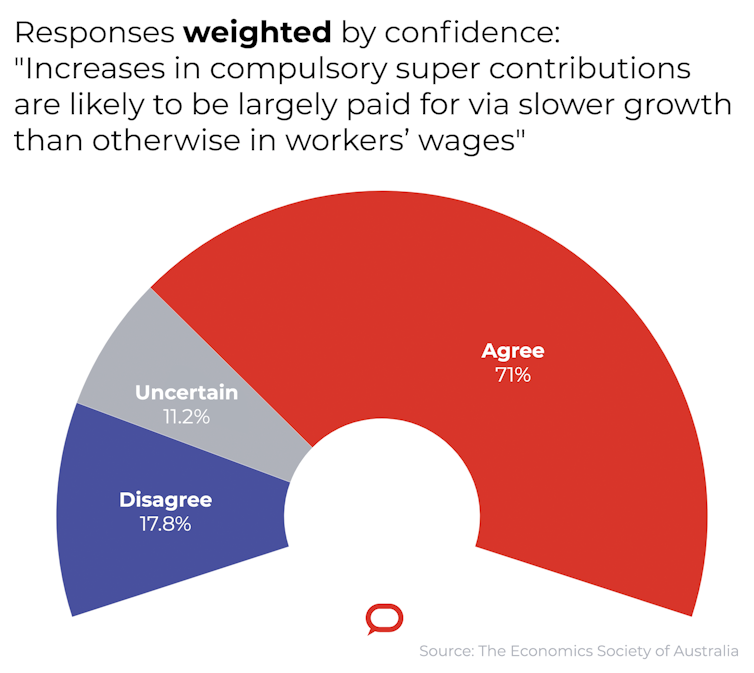

Weighted responses to the proposition:


Individual responses

The Conversation

Peter Martin, Visiting Fellow, Crawford School of Public Policy, Australian National University

This article is republished from The Conversation under a Creative Commons license. Read the original article.

Read more >>

Friday, August 07, 2020

No snapback: Reserve Bank no longer confident of quick bounce out of recession

The good news in the Reserve Bank’s latest quarterly set of forecasts is that the recession won’t be as steep as it thought last time.

The bad news is it now expects ultra-weak economic growth to drag on and on, pushing out the recovery and meaning Australia won’t return to the path it was on for years if not the end of the decade.

Its so-called baseline scenario, which is for the worst recession in 70 years, relies on a number of things going right:

the heightened restrictions in Victoria are in place for the announced six weeks and then gradually lifted. In other parts of the country, restrictions continue to be gradually lifted or are only tightened modestly for a limited time, although restrictions on international departures and arrivals are assumed to stay in place until mid 2021

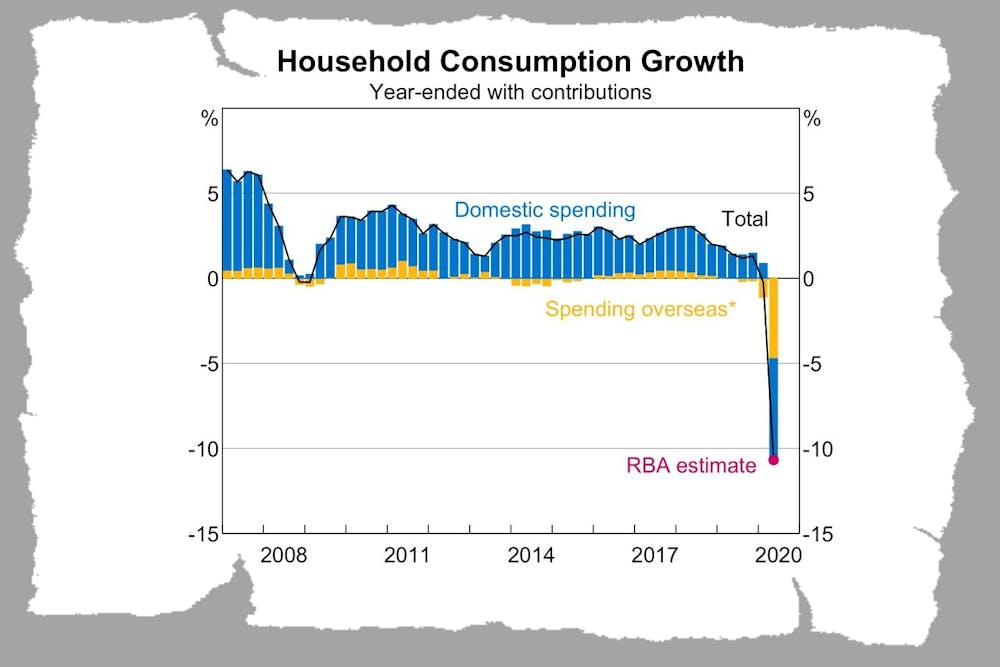
Whereas three months ago in its May update the Reserve Bank expected economic activity to collapse 8% in the year to June 2020 and then bounce back 7% over the following year, it now believes it collapsed a lesser 6% but will claw back only 4% in the year to come.

The direct impact of locked doors and shut shops was smaller than it expected, but the ongoing impacts are “likely to be larger”.

It’ll depend on households

What economic growth there is will be driven by household spending. Business investment, once a key economic driver, won’t be back to anything like where it was until well into 2023.

Business after business has been telling the bank’s liaison officers they have deferred or cancelled planned spending to preserve cash.

In usual times, household spending accounts for 60% of gross domestic product.


Read more: The Reserve Bank thinks the recovery will look V-shaped. There are reasons to doubt it


The Reserve Bank believes household spending fell 11% by the middle of the year and will start to edge back up, but it warns that household incomes are expected to slide and unemployment grow as government winds back JobKeeper and JobSeeker:

The JobKeeper program ensures that many more workers remain attached to their job than otherwise. However, it is expected some workers will be retrenched once they are no longer eligible for the subsidy in late 2020 and early 2021. Moreover, the reinstatement of job search requirements for the JobSeeker program outside of Victoria in the September quarter and the lifting of restrictions will result in more people looking for jobs

It will have been heartened by the Prime Minister’s recent decision to make the wind-back of JobKeeper less steep.

The bank says that the way businesses and households adjust to a lower income in the months ahead will be “an important determinant of the outlook over the rest of the forecast period”.

Reserve Bank of Australia

It expects employment to fall further over the rest of the year, as job losses from restrictions in Victoria and the tightening of JobKeeper more than offset a continued recovery in jobs elsewhere.

One in ten of the businesses it has contacted through its liaison program report wage cuts, most of them targeted towards senior management, but some implemented broadly.


Read more: The Reserve Bank thinks the recovery will look V-shaped. There are reasons to doubt it


The proportion reporting wage cuts is “significantly higher” than during the global financial crisis.

By the end of next year the bank expects the published unemployment rate to be somewhere between 11% and 7%.

The forecast range is an indication of how uncertain it is about what will happen.

Reserve Bank of Australia

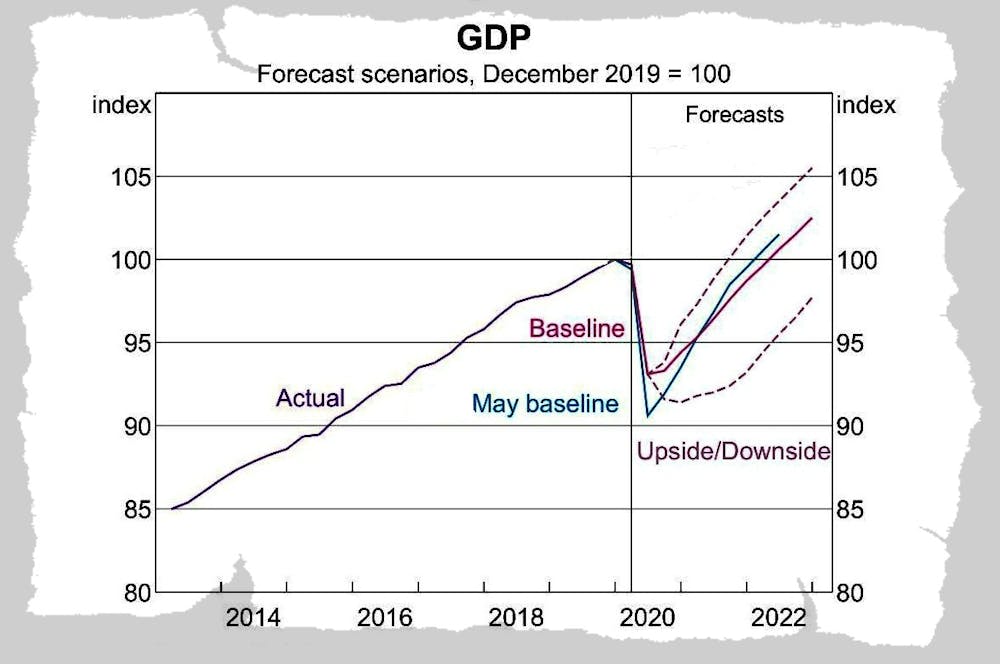
The bank’s forecasts for recession and recovery have a similarly wide range.

On one hand GDP might not be back to where it was until the middle of the decade, and not back to where it would have been until the start of the following decade.

On the other, it might have made up its losses by the end of next year.

Reserve Bank of Australia

The bank’s central “baseline” forecast points to a worse recession than any since World War II and the Great Depression.

Reserve Bank of Australia

Its upside scenario assumes quick progress in controlling the virus, improving consumer confidence as a result, a quick end to the outbreak in Victoria and no further major outbreaks.

The downside scenario assumes rolling outbreaks and rolling lockdowns along with a widespread resurgence in infections worldwide.

Risks a plenty…

It says if households conclude that low income growth will be more persistent than previously expected, they might “permanently adjust their spending” leaving the economy weaker for longer.

The uncertainty could lower firms’ risk appetite, prodding them to pay down debt and increase cash buffers rather than invest even when conditions recover.


Read more: It really is different for young people: it's harder to climb the jobs ladder


A sustained period of lower investment, combined with “scarring” as people unemployed or underemployed find themselves unable to improve their position could “damage the economy’s productive potential”.

…little harm in spending

The bank says there’s little more it can do. It has considered negative interest rates, and believes they would be of no real help.

It’ll be up to the government to support the economy with spending. Where needed the bank will buy government bonds with money it creates in order to keep borrowing costs low.

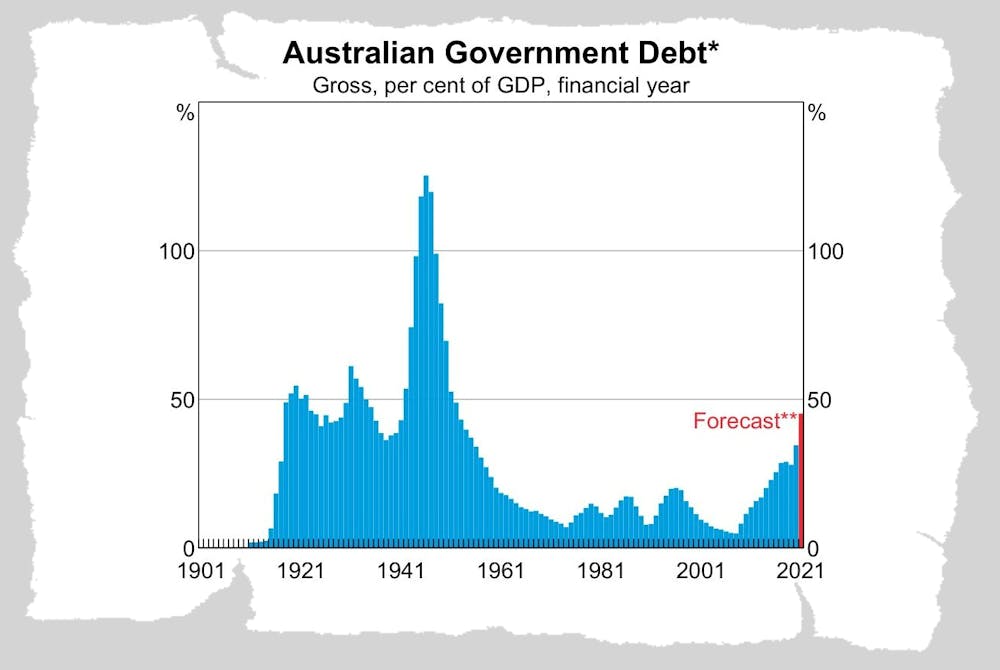
To make the point that government shouldn’t be afraid of borrowing, it includes a graph of government debt since Federation.

Reserve Bank of Australia

Its point is that as a proportion of the economy the government has borrowed and spent much much more in the past.

To the extent that it is needed to make households feel able to spend and businesses able to invest, it is worth it.The Conversation

Peter Martin, Visiting Fellow, Crawford School of Public Policy, Australian National University

This article is republished from The Conversation under a Creative Commons license. Read the original article.

Read more >>

Thursday, July 30, 2020

The government has just sold $15 billion of 31-year bonds. What's a bond?

There are the Boxing Day sales, and there was this week’s rush of extremely cashed-up investors desperate to get a slice of this week’s rare 31-year government bond auction.

What’s a bond? What’s a bond auction? We’ll get to those shortly.

First, just know that the government received A$36.8 billion of bids, $20 billion of them within hours of opening the two-day auction on Monday.

It had been wanting to move $15 billion, and could have moved that much again.

$15 billion makes it the third biggest bond sale in Australian history. The two bigger were recent – a $19 billion ten-year bond sale in May and a $17 billion five-year bond sale in July.

Each sale nets the government money it won’t have to pay back for five, ten or 31 years at rates of interest that until recently would have been unthinkably low.


Read more: More than a rate cut: behind the Reserve Bank's three point plan


The 31-year bond went for 1.94%. That means the foreign and Australian investors who bought them (including Australian super funds) were prepared to accept less than the usual rate of inflation right through until 2051 in return for regular government-guaranteed interest cheques.

Investors who bought ten year bonds were prepared to accept only 0.92% per year, investors who bought five year bonds, only 0.40%.

What’s a bond?

Even bond traders find it hard to get a handle on what bonds are. In his novel Bombardiers, author Po Bronson writes a scene where a bond trader refuses to work any more and demands to see an actual bond, “any kind of bond”.

He tells his boss he can’t sell bonds “if he’s never seen one”.

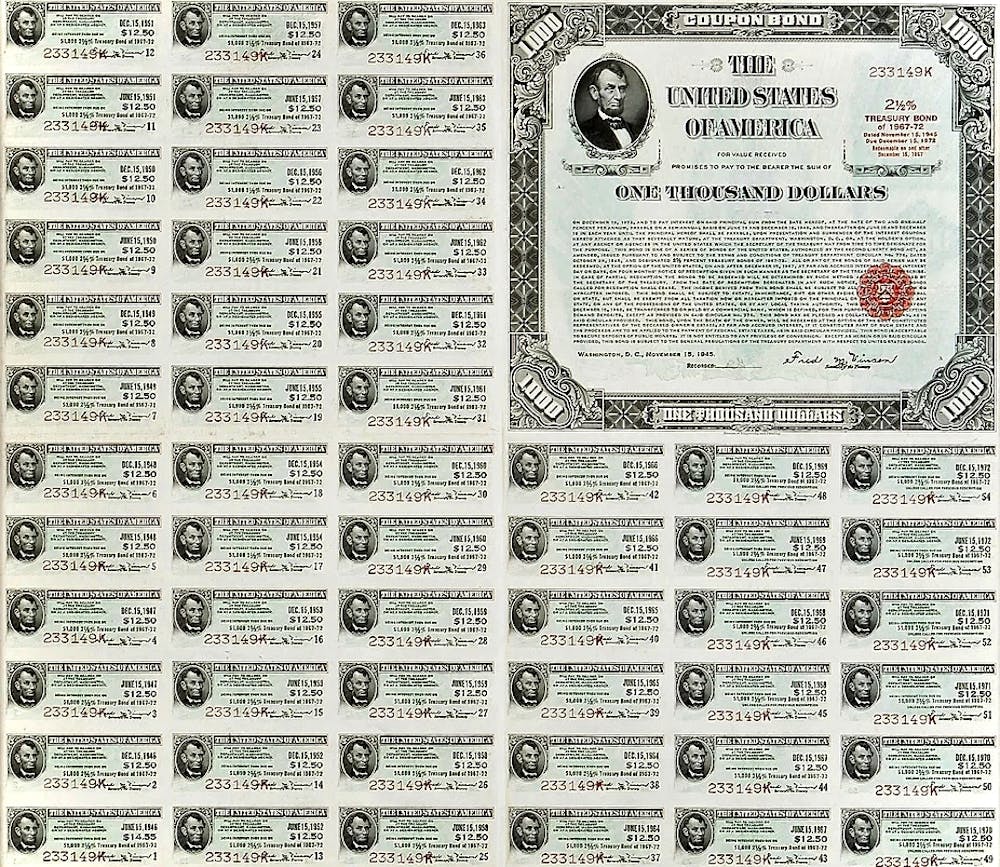
Like many things that used to exist physically, they’re now mainly numbers on screens, but it helps to get a picture.

This one is a US 27-year bond from 1945.

The Joe I. Herbstman Memorial Collection

The biggest part of the paper is a promise to repay the US$1000 it cost, in 27 years time.

The smaller rectangles are called coupons, and each year the owner can tear one off and take it in to get 2.5%.

If the owner wants to sell the bond to someone else (and bonds are traded all the time) it’ll be sold with one coupon missing after one year, two coupons missing after two years, and so on.

When rates fall, prices rise

The price of a bond will vary with what’s happening to interest rates. If they are falling, an existing bond, offering returns at old rates, will become more expensive and can be sold at a profit. If they go up, an existing bond will become worth less and have to be sold at a loss.

It leads to confusion. When bond rates fall, bond prices rise, and visa versa.


Read more: 'Yield curve control': the Reserve Bank's plan for when cash rate cuts no longer work


For half a decade now bond rates have been falling. They’ve fallen further during the COVID crisis, making bonds a doubly good investment. They offer superannuation funds and others certainty at a time when everything seems uncertain, and if rates continue to fall they increase in value.

It is an indictment of our times that so many investors want them. The government’s office of financial management is going to need to sell an extra $167 billion over the coming year. The rush to buy suggests it could sell more.The Conversation

Peter Martin, Visiting Fellow, Crawford School of Public Policy, Australian National University

This article is republished from The Conversation under a Creative Commons license. Read the original article.
Read more >>

Thursday, July 23, 2020

These budget numbers are shocking, and there are worse ones in store

Even if the government hadn’t spent A$5.9 billion on JobKeeper and other emergency measures last financial year and wasn’t planning to spend a further $12.2 billion this financial year, its budget position would have collapsed.

The economic statement released Thursday morning shows it collected $13.2 billion less company tax than it expected last financial year, and will collect $12.1 billion less this financial year.

It collected $9.2 billion less personal income tax last financial year and will collect $26.9 billion less this financial year.

That’s assuming the present lockdown in Melbourne, the Mornington Peninsula and the Mitchell Shire lasts only six-weeks followed by a gradual return to normal and no further lockdowns.

Reality bites

Goods and services tax and excise and customs duty collections are down by $7.3 billion last financial year and down by a forecast $10.7 billion this financial year.

Tax collections from super funds held up in the financial year just ended but are expected to halve in 2020-21, collapsing from $13.2 billion to $6.4 billion.

The collapse reflects what Treasurer Josh Frydenberg called “the reality of where the economy is at”.

Business are closed, planned investment has been axed (non-mining business investment is expected to fall 19.5% this financial year after falling 9% last financial year), consumers are staying at home, and spending on housing is expected to fall 16% after falling 10%.

It has to be lived with

Most of this can’t be undone. Nor can it be offset by increasing tax rates or cutting government spending. As Finance Minister Mathias Cormann noted, that would shrink private spending further.

Net government debt, which was expected to be close to zero last financial year (0.4% of GDP) instead blew out to 24.6% of GDP and is expected to blow out to 35.7% this financial year.

The only safe way to bring it down is to ramp it up as much as is needed to ensure the economy recovers.

As Cormann put it,

the way to get on top of this debt is by growing the economy more strongly and creating more opportunity for Australians to get ahead, get into jobs, better paying jobs and get ahead, because stronger growth leads to more revenue and lower welfare payments and that is the way that we can go back to where we were

It has worked before. Australian government debt blew out to more than 100% of GDP during the second world war but then shrunk year by year in relation to GDP in the economic growth that followed.

Debt didn’t shrink in absolute terms, it shrank in relation to the government’s ability to handle it, and that’s what will happen again if economic growth can be reignited.

The government has been borrowing at annual interest rates of less than 1%. If the economy can grow by more than 1% per year, which historically it has, the payments will eat into less and less of the budget.

Finances are holding up

Next week the government’s office of financial management launches an audacious bid to lock in ultra-low borrowing rates until the middle of the century.

It will issue an unusually long-dated bond (lone) lasting 31 years. It won’t need to be repaid until 2051.

It has appointed five lead managers to sell it – ANZ, Commonwealth Bank, Deutsche Bank, JP Morgan Securities and UBS – in the hope that it can bed down low annual interest payments for a generation.

In the unlikely event the market doesn’t support it, the Reserve Bank has undertaken to step in and use created money to buy as many bonds as are needed to keep the rates low. Since it made the commitment in March it hasn’t needed to spend much at all. Government bond issues have been up to five times oversubscribed by investors desperate for the certainty of a government revenue stream and uneasy about riskier alternatives.

Best case

The forecasts for what will be required need to be seen as best case. The budget deficit is believed to have blown out from an expectation of around zero to $85.8 billion in 2019-20 and $184.5 billion in 2020-21.

Those forecasts have the unemployment rate at 8.75% by this time next year, by which time the economy will have shrunk 2.5%

Economic activity slipped 0.3% in the March quarter, is believed to have shrank 7% in the June quarter, is expected to climb back 1.5% in the September quarter and to claw its way back after that.


Read more: Budget deficit to hit $184.5B this financial year, unemployment to peak at 9.25% in December: economic statement


That’s if restrictions aren’t reimposed, state borders are reopened and there are no further “second waves” of infections.

The treasury says its estimates take into account the effect of the Melbourne outbreak on consumer confidence and activity in the rest of Australia, but assume the outbreak does not spread.

In this way the numbers are a best case. The section in the document on risks to the outlook was unusually short – only three paragraphs.

It says the pandemic is still evolving and the outlook remains highly uncertain.

It will present a fuller assessment of the risks and four years of projections in the formal budget on October 6.The Conversation

Peter Martin, Visiting Fellow, Crawford School of Public Policy, Australian National University

This article is republished from The Conversation under a Creative Commons license. Read the original article.

Read more >>

Wednesday, July 22, 2020

Should the government keep running up debt to get us out of the crisis? Overwhelmingly, economists say yes

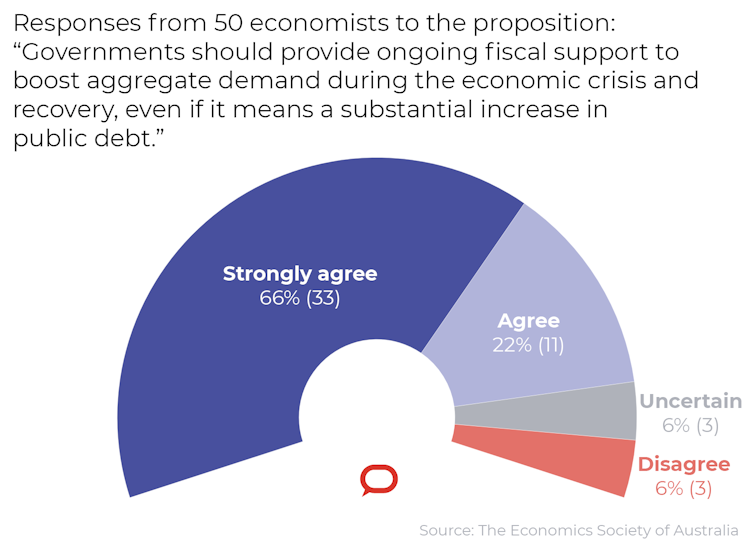
Overwhelmingly, the 50 leading Australian economists surveyed by the Economic Society of Australia and The Conversation ahead of Thursday’s economic statement want the government to keep spending to support the economy — even if it means a substantial increase in debt.

The question is the third asked in the Economic Society-Conversation monthly poll, which builds on a series of polls conducted by the society since 2015.

The economists polled were selected for their preeminence in the fields of microeconomics, macroeconomics, economic modelling and public policy. Among them are former and current government advisers and a former and current member of the Reserve Bank board.

Each was asked whether they agreed, disagreed, or strongly agreed or strongly disagreed with this proposition:

Governments should provide ongoing fiscal support to boost aggregate demand during the economic crisis and recovery, even if it means a substantial increase in public debt

Only three of the 50 economists polled disagreed with the proposition, none of them “strongly”.

It is one of the starkest results in the survey’s five-year history.

50 economists respond: Govs should provide ongoing fiscal support to boost aggregate demand during the economic crisis and recovery, even if it means a substantial increase in public debt. Strongly agree: 66%,  Agree: 22%, Uncertain: 6%, Disagree: 6%
The Conversation, CC BY-ND

Of the 50 economists polled, 44 supported the proposition, 33 of them “strongly”.

Of the remaining six, three were uncertain, and provided well-argued accounts of their reasoning which are published in full along the responses of each of the other participants at the bottom of of this article.

Debt now, concern later

Rachel Ong of Curtin University said the amount of public debt that has accumulated during the COVID-19 crisis was at a historical high and had to be repaid at some point. But she said governments had to be careful about removing support until the economy was clearly on a trajectory of recovery.

Nigel Stapledon of the University of NSW said while some level of on-going support was needed, at some point the cost would be larger than the benefit. Some sectors, including universities, will have to permanently adjust to lower incomes.


Read more: Bowing out gracefully: how they'll wind down and better target JobKeeper


The economists who strongly agreed said that if not enough support was provided or if it was withdrawn too early, the resulting recession would itself make the debt that had been run up less sustainable (Fabrizio Carmignani, Griffith Business).

Financial markets are keen to lend

Beth Webster of Swinburne University argued the only real limit to government spending was high and damaging inflation.

If the government was worried about debt, it could finance its spending in other ways, by borrowing from the Reserve Bank (which could itself create money and “monetise” the debt).

Sue Richardson from the University of Adelaide agreed, using a technical term to argue that the was economy was “so far inside its production possibility frontier” (producing so much less than it was capable of) and inflation was so dormant, that there was a case for creating money.

Saul Eslake said that wasn’t necessary. Even with the hundreds of billions committed, financial markets appeared to be comfortable with the debt and keen to lend.

Debt is how we do things

Reserve Bank board member Ian Harper said the Commonwealth could borrow for 30 years at about 1%. “Can we expect the economy to grow faster than 1% per annum in nominal terms over a 30-year horizon?” he asked rhetorically. “I would have thought that’s a shoo-in,” he answered. If so, then the debt would be easily serviced.

Consulting economist Rana Roy pointed out that public debt was “not an anomaly”. It was an enduring and defining feature of the modern economy, providing an enduring and defining asset class, sovereign bonds, which were in high demand.


Read more: Australia's first service sector recession will be unlike those that have gone before it


Of the three economists who opposed the proposition, Tony Makin of Griffith supported “supply side” measures such as JobKeeper that would keep firms in business but opposed “demand side” measures to boost consumer spending, saying they would ultimately prove counterproductive.

Escalating public debt would induce capital inflow, drive up the dollar and make Australian businesses less competitive. Although interest rates are at present low, they would increase when the debt had to be refinanced.

Doubts for differing reasons

Paul Fritjers of the London School of Economics said he would normally support running up government debt for the sake of the economy, but could not support it being run up to support an economy the government itself had run down.

The government should wean the population off of its “irrational fears” and letting “normal economic life return”.

Although strongly argued, these views were more weakly held than those of the majority.

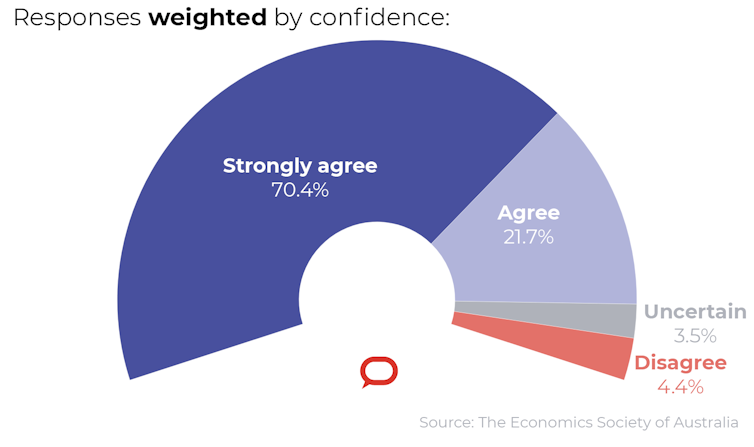
Previous responses weighted by confidence: Strongly agree: 70.4%,  Agree: 21.7%,  Uncertain: 3.5%,  Disagree: 4.4%
The Conversation, CC BY-ND

Participants were asked to rate the confidence with which they held their opinions on a scale of 1 to 10.

When adjusted for these ratings, the proportion prepared to countenance a substantial increase in public debt climbed from 88% to 92.1%.

The proportion opposing it fell from 6% to 4.6%.

Tommorrow’s economic statement will be the last budget and economic update before the budget itself on October 6.


Individual responses

The Conversation

Peter Martin, Visiting Fellow, Crawford School of Public Policy, Australian National University

This article is republished from The Conversation under a Creative Commons license. Read the original article.
Read more >>

Monday, June 29, 2020

No big bounce: 2020-21 economic survey points to a weak recovery getting weaker, amid declining living standards

The picture of economic recovery painted by Prime Minister Scott Morrison is looking like a mirage. The 22 leading economists polled by The Conversation from 16 universities in seven states on average expect historically weak economic growth in all but one of the next five years, with growth dwindling over time.

In June, Morrison promised to lift economic growth by “more than one percentage point above trend” through to 2025.

Growth one percentage point above trend would average almost 4% per year.

Instead, The Conversation’s economic panel is forecasting annual growth averaging 2.4% over the next four years, much less than the long-term trend, tailing off over time.


The results imply living standards 5% lower than the prime minister expects by 2025.

The panel expects unemployment to peak at around 10% and to still be above 7% by the end of 2021.

It expects wages to barely climb at all, by just 0.9% in 2020, the lowest increase on record and even less than the rate of inflation, which it expects to be only 1.2%. It expects the share market to sink further in the rest of this year before climbing a touch in 2021.

Non-mining business investment, on which much of Australia’s recovery depends, should bounce back only 3.3% in 2021 after slipping 9.5% in 2020.


Read more: The Reserve Bank thinks the recovery will look V-shaped. There are reasons to doubt it


The Conversation’s panel comprises macroeconomists, economic modellers, former Treasury, IMF, OECD, Reserve Bank and financial market economists, and a former member of the Reserve Bank board.

Several admitted to much greater uncertainty than usual. One pulled out, saying “it’s really a mug’s game right now”.

One, who did take part, despaired that forecasting had been reduced to “guessing, in the context of an unprecedented event”.

Several cautioned that climate change, along with the prospect of new waves of coronavirus, makes five-year forecasts especially difficult.

Economic growth

All of the panel expect incomes and production to shrink in the June quarter (the one finishing now) after shrinking in the March quarter, meaning we will be in a recession (if there was any doubt).

Some are expecting a small bounce in the September quarter, although they warn that if JobKeeper and the coronavirus JobSeeker Supplement end as planned when September finishes, economic activity will turn down again in the December quarter, creating what panellist (and former Labor politician) Craig Emerson describes as a “W-shaped economic trajectory”.

Panellist Julie Toth cautions there is “no magic V ahead”. Without government action on adaptation to climate change, productivity, industrial relations, inequality and other matters, the best that can be hoped for is a partial recovery of some of the growth that has been lost.

In in 2021 the panel expects the economy to recover only half of what it lost in 2020. After peaking at 2.9% in 2023, economic growth will slip back to less than it was before the crisis.


The panel expects China’s economy to shrink 2.3% this year before bouncing back 4% in 2021. It expects the US economy to shrink 5.6% before recovering only 2.2%.

Steve Keen suggests that the underlying US performance will be even worse. It will have attained its measured performance by being prepared to live with adverse health consequences.

Tony Makin notes that China’s near-term economic growth is likely to be hampered by a move towards deglobalisation in countries wanting to make their supply of goods and health equipment less reliant on China.


Unemployment

The forecasts for the peak in the unemployment rate range from the present 7.1% to 12%, with most of the panel expecting the peak before the end of the year.

Julie Toth points out that even with no further job losses, “which seems unlikely”, measured unemployment will continue to rise for some time as people who have stopped looking for work start looking again and return to being counted as unemployed.

Saul Eslake says this participation rate makes forecasting the unemployment rate a “crapshoot”. The rate will depend largely on how many people choose to define themselves as looking for or non longer looking for work.


Living standards

The panel expects household incomes and spending to fall by about 4% over the course of the year.

The best measure of living standards, real net national disposable income per capita, should fall 4.5%.


Real wages, a key component of living standards, are expected to fall.

Never in the 23-year history of the Australian Bureau of Statistics’ wage price index has annual wage growth been much below 2%. Until now the lowest annual growth rate has been 1.9%.

The panel is forecasting growth of just 0.9% throughout 2020, a mere half of the record low to date. The forecast calls into question the timing of the current legislated increases in compulsory superannuation contributions of 0.5% of salary per year for each of the next five years, scheduled to start next year and set to eat into wage growth.

Headline price inflation should be only 1.2%, and underlying (smoothed) inflation only 1%, but both would be more than wage growth, shrinking the buying power of wages.


Share market

The spectacular recovery in the Australian share market (up 29% since late March after sliding 36% since late February) is not expected to continue this year.

The panel expects the ASX 200 to end the year down 8% before climbing 2.3% in 2021.

But the forecasts for 2021 fan out over a wide range, from a fall of 10% to a rise of 10%.


Housing

Sydney and Melbourne house prices are expected to reverse their gains of 5% and 3% in the first half of the year to close about where they started (Sydney) and down 1.3% (Melbourne).


New home building is expected to plunge a further 10% in 2020 after sliding 10% in 2019.

On balance it is not expected to improve at all in 2021, although again the range of forecasts is wide, from a recovery of 10% (Renée Fry-McKibbin) to a further decline of 10% (Stephen Hail).


Business

Mining investment is expected to continue to recover in 2020 and 2021 after huge falls between 2014 and 2019 brought about by the collapse of the infrastructure boom and the completion of several large liquefied natural gas projects.

Non-mining business investment is expected to fall 9.5% throughout 2020 before inching back 3.3% in 2021.


The Australian dollar is forecast to end the year near its present 69 US cents.

After initially diving to a low of 59 US cents as the coronavirus crisis unfolded, it and other currencies climbed against the US dollar from late March as the US response to the crisis faltered.

The price of iron ore has climbed from late March to a high of US$103 per tonne, well above the US$55 assumed in last year’s budget papers.

The panel is expecting most of those gains to be kept, forecasting US$97 by the end of the year, enough to provide one of the few welcome pieces of news for framers of the October budget.

Again, the range of forecasts is wide, from US$64 a tonne (Stephen Anthony) to US$110 (Margaret McKenzie).


Government finances

After ending 2018-19 almost in balance, the budget deficit is expected to blow out to between A$130 billion and A$150 billion in 2019-20, weighed down by about the same amount of stimulus payments.

The forecasts for 2020-21 and 2021-22 are centred around $150 billion and $100 billion respectively.

It’s a hard outcome to pick, in part because it depends on both the needs of the economy and government decisions about how to respond to them. In a report issued on Monday the Grattan Institute called for the government to spend an extra $70 billion over two years.

Forecasts for the 2021-22 budget outcome range from a deficit of $200 billion (Rod Tyers) to a deficit of just $10 billion (Janine Dixon).


It’ll be easy to finance. The panel is forecasting a ten-year borrowing cost (bond rate) of just 1.4% per year, and it doesn’t expect it to climb that high until late 2021.

At the moment it’s 0.9%.

The Reserve Bank has committed itself to buy as many bonds as are needed to keep it low. The three major rating agencies have reaffirmed Australia’s AAA credit rating.


A survey of firsts

The 2020-21 survey is the first in 30 years not to ask for forecasts of the Reserve Bank cash rate, and the first since it has been published by The Conversation not to ask for the probability of a recession.

The Reserve Bank’s decision to push the cash rate as low as it conceivably could and leave it there for three years removed the need for the first. Australia’s descent into recession removed the need for the second.

The forecaster who proved to be the most farsighted on the recession was Steve Keen, who assigned a 75% probability to a recession in January at a time when Australia was dealing with bushfires and preparing to deal with coronavirus.

Other forecasters to assign a high probability to a recession (50%) were Julie Toth, Steven Hail, Warren Hogan and Richard Holden.


The Conversation 2020-21 Forecasting Panel

Click on economist to see full profile.

The Conversation


PDF OF RESULTS

Peter Martin, Visiting Fellow, Crawford School of Public Policy, Australian National University

This article is republished from The Conversation under a Creative Commons license. Read the original article.

Read more >>

Monday, June 08, 2020

Economists back wage freeze 21-19 in new Economic Society-Conversation survey

Australian economists narrowly back a wage freeze in the minimum wage case now before the Fair Work Commission, a freeze that could flow through to millions of Australians on awards and affect the wages of millions more through the enterprise bargaining process.

The annual case is in its final stages after having begun before the coronavirus crisis and been extended to take account of its implications.

In its submission, the Australian government called for a “cautious approach”, prioritising the need to keep Australians in jobs and maintain the viability of businesses.

The minimum wage was last frozen in 2009 amid concern about unemployment during the global financial crisis.


Read more: Economists back social distancing 34-9 in new Economic Society-Conversation survey


The Economic Society of Australia and The Conversation polled 42 of Australia’s leading economists in the fields of microeconomics, macroeconomics, economic modelling and public policy.

Among them were former and current government advisers, a former and current member of the Reserve Bank board, and a former head of the Australian Fair Pay Commission.

Each was asked whether they agreed, disagreed, or strongly agreed or strongly disagreed with this proposition:

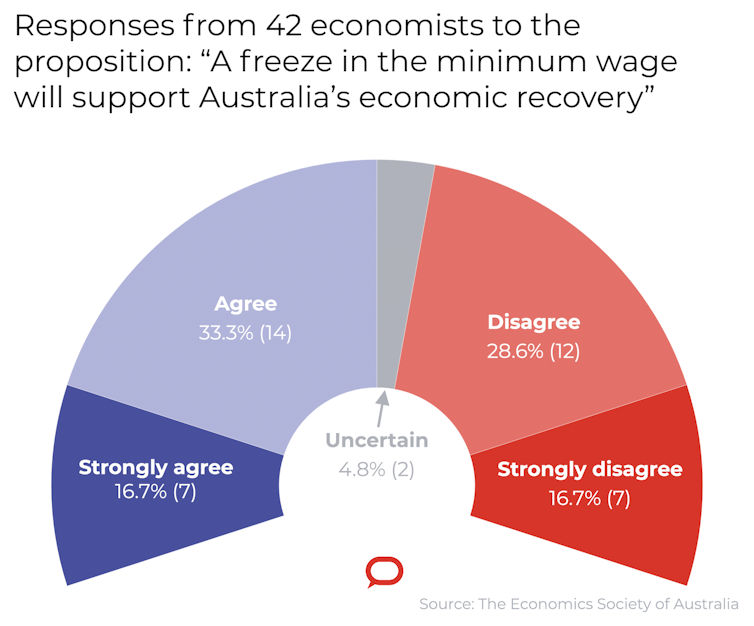
A freeze in the minimum wage will support Australia’s economic recovery

Each was asked to rate the confidence they had in their opinion, and to provide reasons, which are published in full in The Conversation.

Half of those surveyed – 21 out of 42 – backed the proposition, seven of them “strongly”.

Nineteen disagreed, seven strongly. Two were undecided.

The Conversation, CC BY-ND

The minimum adult wage is A$19.49 per hour.

There was agreement among most of those surveyed that, in normal times, normal increases in the minimum wage have little impact on employment – a view backed by Australian and international research.

But several of those surveyed pointed out that these are not normal times.

Bad times for employers…

Gigi Foster said many businesses were operating closer to the margin of profitability than ever before, and were likely to stay that way for many months.

Rana Roy quoted one the pioneers of modern economics, Joan Robinson, as observing in 1962 that the misery of being exploited by capitalists was “nothing compared to the misery of not being exploited at all”.

John Freebairn argued that a freeze of labour costs, together with very low expected inflation, could provide a key element of certainty in the uncertain world facing households, businesses and governments.

Robert Breunig and Tony Makin suggested that with prices stable or possibly falling, a freeze in the minimum wage might cost workers little or nothing in terms of purchasing power.

Guay Lim and several others said if the government wanted the economic stimulus that would come from an increase in the minimum wage, it had other ways of bringing it about without making conditions more difficult for employers.

…and bad times for workers

Those supporting an increase saw it as a way to bolster consumer confidence and redress unusually weak worker bargaining power.

Wage growth before the coronavirus hit was historically low at close to 2%, an outcome so weak for so long that in 2018 and 2019 the Commission awarded much bigger increases in the minimum wage, arguing employers could afford them.

James Morley was concerned that a freeze in the minimum wage would “mostly just lock in” inflation expectations that were already too low.

Peter Abelson said labour productivity rose with respect for workers and fell with disrespect. A wage freeze would disrespect workers.

Saul Eslake proposed a middle way, deferring a decision rather than granting no increase. He said the increase that was eventually granted should do no more than keep pace with inflation.


Read more: Why the coronavirus shouldn't stand in the way of the next wage increase


The economists were asked to rate their confidence in their responses on a scale of 1 to 10.

Unweighted for confidence, 45.3% of those surveyed opposed a wage freeze. When weighted for (relatively weak) confidence, opposition fell to 43.5%.

The Conversation, CC BY-ND

Unweighted for confidence, half of those surveyed supported the proposition that a freeze in the minimum wage would assist Australia’s economic recovery.

Weighted for confidence, support grew to 51.6%

The Fair Work Commission is required to complete its review by the end of this month.


Individual responses

The Conversation

Peter Martin, Visiting Fellow, Crawford School of Public Policy, Australian National University

This article is republished from The Conversation under a Creative Commons license. Read the original article.
Read more >>

Wednesday, June 03, 2020

The economy in 7 graphs. How a tightening of wallets pushed Australia into recession

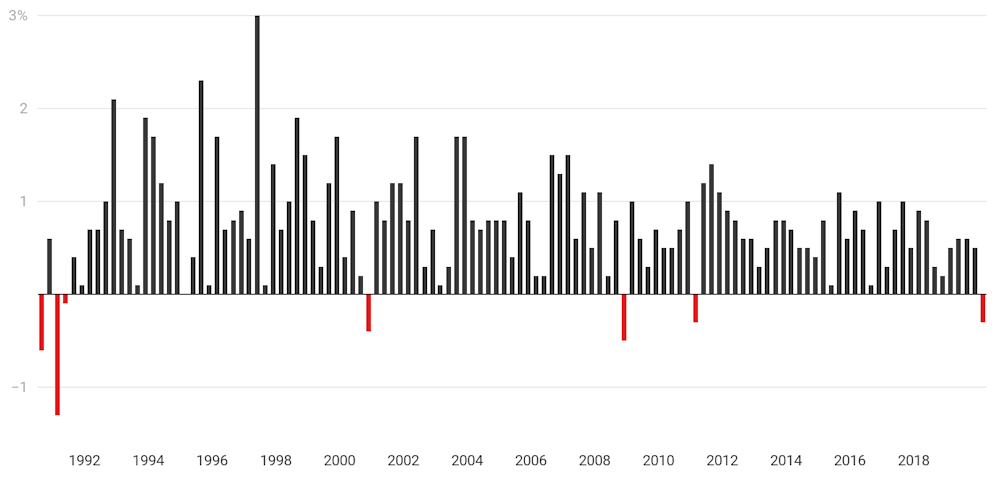
A go-slow on spending sent the economy backwards 0.3% in the first three months of this year, only the fourth such decline since Australia was last in recession in the early 1990s.

Treasurer Josh Frydenberg says Treasury has told him the next three months, the June quarter that we are in at present, will see a “far more severe” contraction, one private sector forecasters believe could be as high as 10%.

Asked whether that meant Australia was already in recession, he said it did.


Quarterly GDP growth since 1990

ABS 5206.0

Most unusually for an economic downturn, incomes rose throughout the quarter, pushed higher by a 6.2% increase in government payments related to COVID-19 and the bushfires, and an 11.1% increase in insurance payouts as a result of bushfires and hailstorms.

Household incomes even rose in per capita terms, by 0.1% after abstracting for population growth.

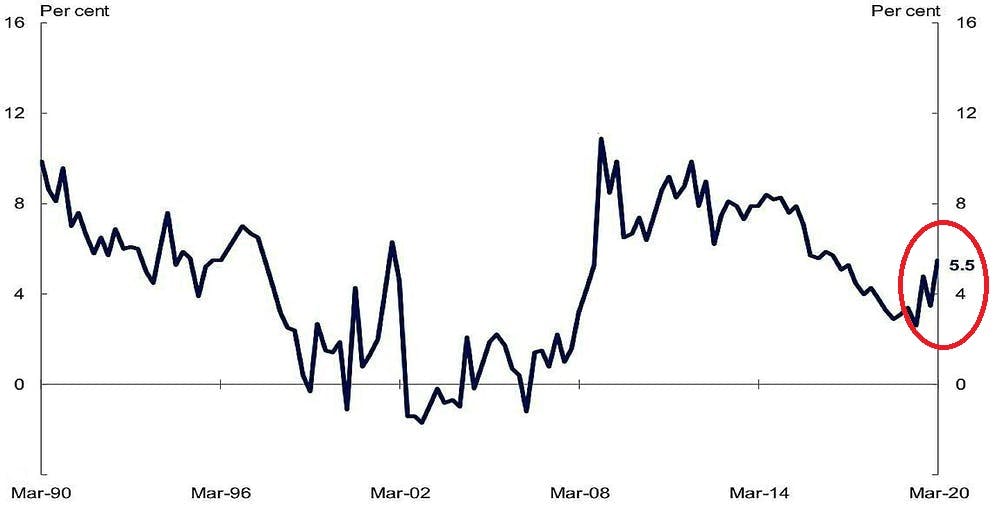
But rather than spend more, Australian households dramatically increased saving in the quarter, pushing the household saving ratio up from 3.5% to 5.5% and pushing down household spending 0.2%.


Household savings ratio

Commonwealth Treasury

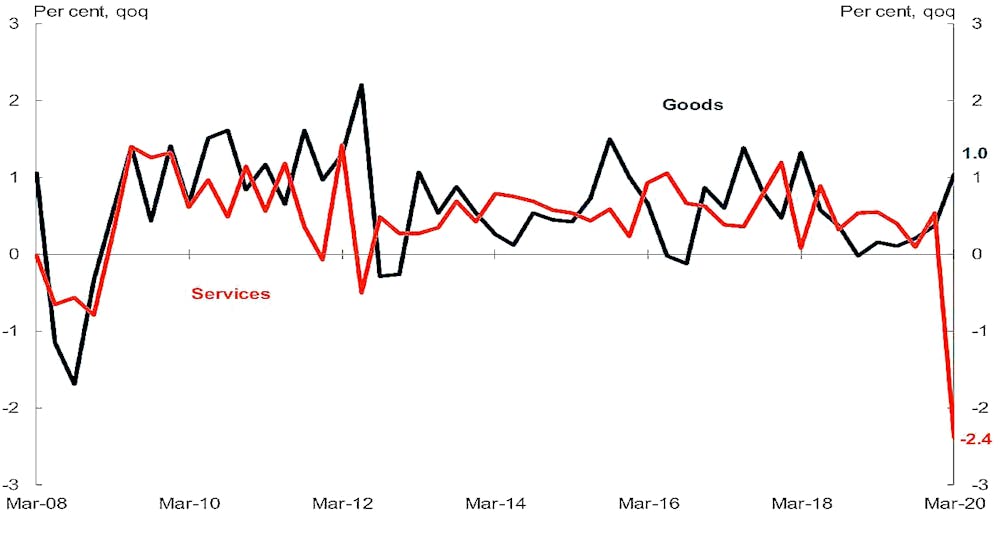
Spending on goods actually increased over the three months as Australians stocked up on essentials including toilet paper in March.

The production of “petroleum, coal, chemical and rubber products” surged 8.1% as consumers stocked up on cleaning and disinfectant products.

But spending on services plummeted, led down by dramatic falls in spending on transport and hotels, cafes and restaurants.


Household consumption, March quarter

Commonwealth Treasury

Spending on transport services (airlines and the like) fell 12.0%. Spending on hotels, cafes and restaurants fell 9.2%, each the biggest fall on record.

“Production” in these industries fell 4.9% and 7.5%. Profits fell 6.8% and 14.2%.

Spending fell on ten of the 17 consumption categories.


Household consumption by category, March quarter

Commonwealth Treasury

Most of the changes took place at the very end of the March quarter.

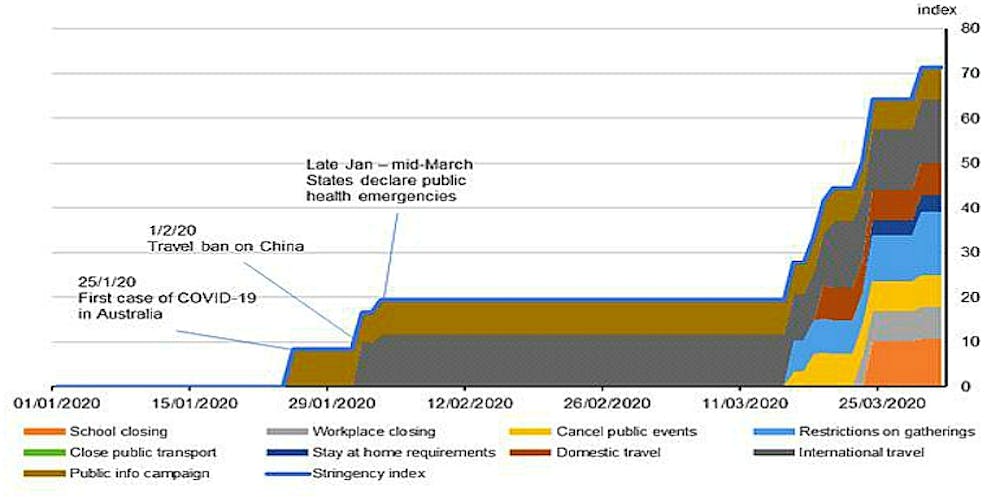
A new index of the “stringency” of COVID-19 containment measures released with the national accounts shows these ramped up only in the final two weeks.

Most have been in place for the entirety of the June quarter to date, suggesting the impacts on spending and production will be a “lot more substantial”, in the words the treasurer used in the national accounts press conference.


ABS stringency of containment measures index

ABS 5206.0

Were it not for government spending, which has climbed 6.2% throughout the year, the plunge in March-quarter GDP would have been much more severe.

Calculations of the Bureau of Statistics suggest it would have been twice as severe, a March quarter decline of 0.6% rather than 0.3%.


General government expenditure

Commonwealth Treasury

The treasurer described Australia as “on the edge of the cliff” in the March quarter, facing “an economist’s version of Armageddon”.

The treasury had been contemplating a fall in gross domestic product of 20% in the June quarter. Australia has avoided that fate by acting on health and the economy early.

Its fall in GDP of 0.3% in the March quarter was one-third the OECD average.


International comparisons, real GDP growth, March quarter

Commonwealth Treasury

The treasurer has scheduled an economic update for July 23 which will include the result of a review of the JobKeeper program.

Asked whether it could be referred to as a mini-budget, he said it could be.


Read more: Our needlessly precise definition of a recession is causing us needless trouble The Conversation


Peter Martin, Visiting Fellow, Crawford School of Public Policy, Australian National University

This article is republished from The Conversation under a Creative Commons license. Read the original article.

Read more >>